Opening: The underwriting challenge
How much of a $100 million private-credit portfolio is exposed to the same economic shock, even when no borrower exceeds a single-name limit? A borrower list sorted by industry may show acceptable diversification while the loans share a customer base, sponsor, refinancing window, critical input, or rate sensitivity. That hidden overlap can turn several apparently separate credits into one correlated loss event.
Portfolio concentration analysis starts with loan-level underwriting, but it cannot stop at the obligor. The lender needs a consistent view of funded and unfunded exposure, common risk drivers, covenant protection, and the likely recovery path if multiple credits weaken together. The objective is not to eliminate concentration. That can push a lender into unfamiliar sectors or structures. The objective is to identify where losses could cluster, set limits against the portfolio’s risk capacity, and decide in advance what action follows a limit breach.
Recent default data also argues against relying on a single market-wide rate. Fitch and Proskauer report materially different Q3 2026 measures because their covered portfolios and default definitions differ. A useful portfolio framework must therefore test the specific risks in the lender’s own book.
The framework: Map exposure before setting limits
Build a single exposure file at the facility and ultimate-obligor level. Record funded principal, undrawn revolver commitments, delayed-draw amounts, guarantees, and any exposure expected to remain from the underwriting pipeline. Link every facility to the legal borrower, parent, sponsor, industry, end market, geography, material customer or supplier dependencies, loan vintage, floating-rate status, maturity year, covenant package, and primary collateral or enterprise-value reliance. Use tags that permit overlapping views. A software vendor selling mainly to hospitals is both a software and healthcare exposure.
Measure concentration using at least three lenses. First, calculate each bucket’s share of total exposure: sector exposure divided by portfolio exposure. Second, report top obligors and sponsor groups, including related borrowers. Third, calculate the Herfindahl-Hirschman Index (HHI), the sum of squared portfolio shares. If a five-sector book has shares of 25%, 20%, 20%, 20%, and 15%, HHI is 0.21, or 2,100 on the 10,000-point scale. HHI summarizes dispersion, but it does not reveal correlation or dictate a safe limit.
Pair those exposure measures with credit-capacity metrics. For each borrower, track net leverage, cash interest coverage (EBITDA less maintenance capex, divided by cash interest, where that is the lender’s defined measure), minimum liquidity, and covenant headroom. At portfolio level, measure the share of exposure with thin headroom, near-term maturities, PIK or deferred interest, covenant relief, and enterprise-value-dependent repayment. Set limits by obligor, sponsor, sector, correlated end market, geography, and vintage as appropriate. Calibrate them to capital, liquidity, staffing expertise, and the loss the portfolio can absorb. There is no universal sector cap.
The supervisory framework provides a useful process reference. Federal Reserve, FDIC, and OCC leveraged-lending guidance calls for a risk appetite, concentration framework, reliable management information, and periodic portfolio and pipeline stress tests. OCC concentration guidance says stress tests should quantify correlated exposures and help calibrate limits. See the interagency leveraged-lending guidance and the OCC Comptroller’s Handbook on concentrations of credit.
The analysis: Convert overlap into loss and action
Consider an illustrative $100 million portfolio with $25 million of exposure to industrial manufacturers. The bucket includes one borrower that supplies several portfolio companies, so a demand shock could affect borrowers in adjacent sectors as well. In a sector stress, assume 40% of the industrial exposure defaults and the recovery rate is 50%. The simple loss estimate is: $25 million × 40% × (1 − 50%) = $5 million, equal to 5% of portfolio exposure. This is a scenario calculation, not an expected-loss forecast.
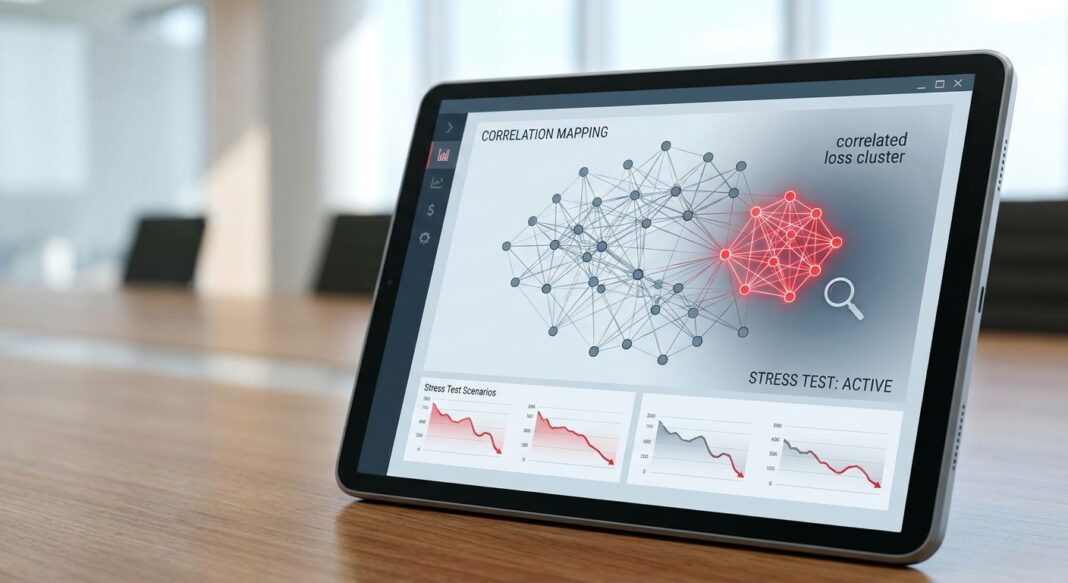
Now run a correlated case. If customer and supplier mapping shows another $10 million of exposure is vulnerable to the same shock, the at-risk pool becomes $35 million. Applying the same assumed default and recovery rates produces a $7 million loss, or 7% of the portfolio. Do not add overlapping industry and customer buckets as though they were independent exposures. Assign each loan once in the loss calculation, then show the risk-driver tags that explain why it is included.
Stress the borrowers’ ability to avoid default as well as the loss after default. Reduce sales or gross margin for the affected cohort, then recalculate EBITDA, leverage, cash interest coverage, liquidity runway, and covenant headroom using each credit agreement’s definitions. Run a separate rate or refinancing shock where relevant. Record which borrowers breach maintenance tests, need a waiver, or cannot repay at maturity. Compare aggregate stress loss with the approved risk budget. If it exceeds that budget, the response may include tighter underwriting, lower new commitments, a sector or sponsor exposure cap, more frequent reporting, or a documented reduction plan.
Industry standards: Read performance data by definition
Institutional practice is built around a clear risk appetite, consolidated exposure data, documented limits, independent review, and stress scenarios that management can act on. The federal leveraged-lending guidance specifically calls for periodic stress testing of held loans and pipeline exposures, with results relevant to asset quality, earnings, liquidity, and capital. It also expects timely reporting of concentrations and portfolio performance. For private lenders, the same disciplines are useful even where bank supervisory rules do not directly apply.
Recent Q3 2026 releases show why definition control matters. Fitch reported a U.S. private-credit trailing-12-month default rate of 6.3% at Q3 2026, versus 6.0% at Q2, and counted 27 Q3 default events involving 20 new unique defaulters. Its trailing-12-month total was 91 unique defaulters, up from 84 at Q2. Fitch’s reported events include stressed maturity extensions, interest deferrals, and PIK introductions, as described in its November 11, 2026 release.
Proskauer’s October 27, 2026 index reported a 2.41% Q3 default rate for 746 U.S. senior-secured and unitranche loans representing $205.7 billion of original principal, down from 2.51% in Q2. Proskauer also reported a 2.2% Q3 rate for borrowers below $25 million EBITDA, up from 1.9% in Q2. These figures are not directly comparable with Fitch’s broader measure. The gap is a reason to track payment defaults, amendments, PIK conversions, maturity extensions, non-accruals, and restructurings separately, not to select whichever headline rate appears reassuring. Source: Proskauer’s Q3 2026 Private Credit Default Index.
Common control failures include setting limits only by formal industry codes, omitting unfunded commitments, treating sponsor-backed companies as independent when their cash flows share risk drivers, and allowing exceptions without owners or expiry dates. A low current default rate also does not establish that a portfolio can withstand simultaneous stress. Concentration limits should reflect loss severity and liquidity needs, not just historical defaults.
Underwriting checklist
- Reconcile exposure: Tie funded balances, undrawn commitments, guarantees, and pipeline positions to current source systems. Identify related obligors and parent entities.
- Tag shared risk drivers: Record sector, end market, sponsor, geography, customer and supplier links, floating-rate exposure, maturity year, vintage, collateral, and covenant type. Document the source and date for each material tag.
- Calculate limits and headroom: Report top obligors, sector and sponsor shares, HHI, limit utilization, and exceptions. Define warning thresholds below the hard limit and assign an accountable owner.
- Run scenarios: Test borrower-level EBITDA, leverage, cash-interest coverage, liquidity, and covenant headroom under a common shock. Aggregate default and recovery assumptions without double counting overlapping tags.
- Document decisions: Retain the exposure file, stress assumptions, loan-level calculation, approval record, exception rationale, remediation action, and next review date. Ask what common shock could impair several borrowers at once, what covenant or collateral control gives early notice, and what exposure can actually be reduced in a stressed market.
Review triggers should include acquisitions, new commitments, amendments, PIK elections, covenant waivers, ratings changes, and material shifts in customer or supplier concentration. Update the analysis at least on the portfolio’s regular risk-review cycle and promptly after a material change.
Key takeaways
- Aggregate common economic exposures, not only legal borrowers or industry labels.
- Use HHI as a dispersion indicator, not a substitute for correlation analysis.
- Translate scenarios into borrower-level coverage, liquidity, covenant, and recovery outcomes.
- Interpret default rates only with their cohort, period, and event definition attached.
- Set limits with explicit thresholds, exception owners, and corrective actions.