
The Financing Problem That Closes Deals, or Kills Them
You have a signed letter of intent. You have a target with $2.3M in normalized EBITDA and a $15M enterprise value. Your senior lender will extend to 3.5x leverage, approximately $8M. A seller note absorbs another $1M. That leaves $6M unfunded, and the equity cost of filling it outright is unacceptable to your existing cap table.
This is the defining capital challenge of the growth stage: the business has outgrown venture equity terms but has not yet earned its way into broadly syndicated leveraged finance. The gap between what senior lenders will fund and what the deal requires is not a structuring failure; it is a structural reality. The question is not whether it exists, but how precisely you fill it.
That $6M is your gap capital quantum. Mezzanine debt (subordinated, higher-yield, and equity-adjacent) is frequently the instrument that closes it. Understanding when to use it, how to structure it, and how to negotiate it is the core competency this article addresses.
Step 1: Map the Full Capital Stack Before Approaching Any Lender
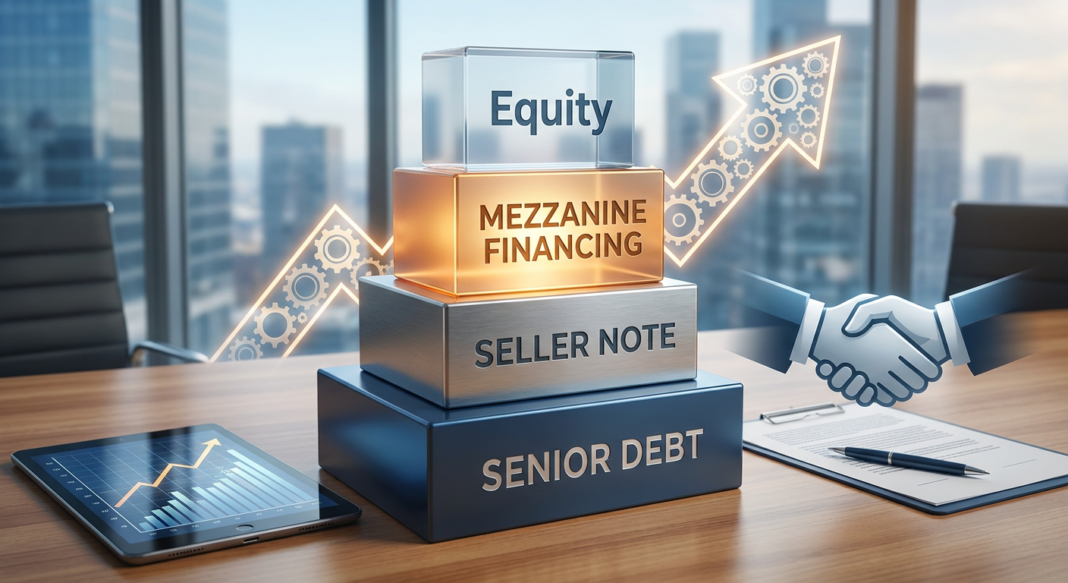
Effective acquisition financing begins with a use-of-proceeds schedule, not a lender call. Every layer of the capital stack carries a distinct cost, a distinct risk tolerance, and a distinct set of structural expectations. Moving from most senior to most junior, the stack for a growth-stage acquisition typically comprises four layers, as outlined in bondtv.vaultai.ca:
- Senior secured debt: Lowest cost, highest restriction. In the current direct lending environment, all-in pricing typically runs 7%–10% for growth-stage borrowers. Sized to 3.0x–4.0x normalized EBITDA for established cash flows, lower for earlier-stage businesses. First lien on all assets, most restrictive covenant package.
- Mezzanine / subordinated debt: The gap capital layer. All-in pricing typically ranges from 13%–18%, structured as a cash-pay coupon plus a PIK (payment-in-kind) component, and often paired with warrant coverage of 1%–5% of fully diluted equity. Subordinated to senior lenders; senior to all equity.
- Seller notes / earnouts: Frequently used to bridge valuation disagreements. Typically priced at 5%–8% with a payment holiday in years one through two. Can anchor 5%–10% of total deal value.
- Equity: Most expensive in dilution terms. Sized as the residual after debt capacity and seller participation are fully deployed. Minimizing the equity contribution, without over-levering the business, is the central structuring objective.
For the $15M acquisition example above, the stack resolves as follows: $8M senior debt, $1M seller note, $6M mezzanine, with equity as the residual based on sponsor contribution and rollover. Build this schedule before you make a single lender call.
Step 2: Understand How Mezzanine Is Priced and Structured
Mezzanine is not a monolithic product. Its structural features vary materially across providers, and the total cost of constraint, not just the coupon rate, is the correct comparison metric when evaluating competing term sheets.
Core Structural Components
- Cash-pay coupon: The portion of interest paid quarterly or semi-annually in cash. Typically 8%–12% of the principal balance.
- PIK component: Interest accrued and added to principal rather than paid in cash. Preserves liquidity during integration but compounds the principal balance. Typical PIK rates run 2%–5%, bringing total coupon to 13%–18% all-in.
- Warrant coverage: The right to purchase equity at a fixed strike price, representing 1%–5% of fully diluted shares. This is the lender’s equity upside, and the borrower’s dilution cost. Warrants issued at a below-market strike carry meaningful economic consequence at exit.
- Maturity: Typically five to seven years, with a bullet repayment. Mezz providers underwrite to enterprise value creation and a credible exit or refinancing pathway, not to near-term cash flow coverage alone.
- Prepayment fees: Standard mezz facilities carry call protection of 2%–3% in years one through three, stepping to zero thereafter.
Covenant Design: The Binary That Matters Most
Covenant structure is frequently the most consequential (and most negotiated) element of a mezz facility. The choice is binary:
- Maintenance covenants are tested quarterly against a live financial ratio (e.g., total leverage, fixed charge coverage). A business with lumpy cash flows can trip a maintenance covenant even when fundamentally solvent. This creates the most operational risk for growth-stage companies.
- Incurrence covenants are tested only when a specified action is taken: drawing additional debt, making a distribution, or executing an acquisition. They provide substantially more operating room and are the preferred structure for borrowers with variable revenue profiles.
Negotiate covenant design in the term sheet, not the definitive agreement. Once legal drafting begins, this point is structurally locked.
Step 3: Prepare the Materials That Move Gap Capital Providers
Mezzanine providers underwrite to a fundamentally different thesis than senior lenders. Senior lenders underwrite to downside asset coverage. Mezz providers underwrite to enterprise value creation and equity coverage. Your materials must speak directly to their framework. The four documents that define a credible gap capital process are:
- Use-of-proceeds memo: A precise, one-page schedule mapping every dollar from sources to uses. Demonstrates how the acquisition creates EBITDA accretion. This is not a narrative; it is arithmetic.
- Three-year integrated financial model: Revenue, EBITDA, debt service, and free cash flow, with sensitivity tables on two variables: revenue growth rate and EBITDA margin compression. Providers need to see how much degradation the structure can absorb before covenants trip or cash runs short.
- Management presentation: Strategic rationale, competitive moat, customer concentration risk, and a clearly articulated exit pathway. Mezz providers hold for five to seven years and need to underwrite your eventual refinancing or sale event.
- Clean cap table: Pre- and post-transaction ownership, fully diluted. Ambiguity in the cap table extends diligence timelines significantly.
Step 4: Run a Parallel, Competitive Process
The most common tactical error in gap capital raises is approaching providers sequentially. Sequential outreach eliminates price tension, signals desperation, and extends timelines. The correct approach is parallel and structured.
Approach four to six gap capital providers simultaneously. Issue a structured term sheet request with a defined response window of 10 to 15 business days. Require each provider to specify five dimensions in their response, as detailed in bondtv.vaultai.ca: coupon structure (cash pay versus PIK split), warrant coverage percentage, covenant package design, board observer rights, and change-of-control and prepayment provisions.
Evaluate competing term sheets across all five dimensions simultaneously. A 14% all-in mezz facility with 3% warrant coverage and quarterly maintenance covenants can be structurally more constraining than a 16% preferred equity instrument with no covenants and no scheduled amortization. Total cost of constraint is the correct lens, not headline rate alone.
Before committing to any structure, model three scenarios: (a) fill the gap with mezz debt, (b) fill it with preferred equity, (c) blend both. For each scenario, stress-test your post-close Fixed Charge Coverage Ratio (FCCR), total leverage multiple, and pro-forma equity dilution. The target zone that serves as a structural benchmark: FCCR above 1.20x, total leverage below 5.0x EBITDA, equity dilution below 15% of common. The scenario that meets all three thresholds in your base case (and survives in your downside case) is the optimal structure.
Step 5: Negotiate the Five Structural Levers That Move the Most Value
Once competing term sheets are in hand, negotiation narrows to five specific structural points:
- PIK toggle flexibility: Negotiate the right, not the obligation, to PIK interest in years one through two. This preserves cash during integration without triggering default. The distinction between a mandatory PIK and a borrower-elected toggle is economically significant.
- Warrant strike price and coverage cap: Warrants issued at a below-market strike dilute common equity holders at exit. Push for above-market strikes or a hard cap on total warrant coverage as a percentage of fully diluted shares. This is a negotiable point and frequently conceded in competitive processes.
- Maintenance vs. incurrence covenants: As noted above, this is a binary negotiation. Incurrence-only covenants provide substantially more operational room for growth businesses with variable revenue. Get the covenant design confirmed in the term sheet, in writing, not deferred to definitive documentation.
- Prepayment and call protection: Standard mezz facilities carry 2%–3% prepayment fees in years one through three, stepping to zero thereafter. Negotiate a make-whole carve-out for change-of-control events initiated by the lender, not the borrower.
- Board observer rights and information covenants: Many gap capital providers require board observer rights as a funding condition. Define precisely what triggers the right, what information is shared in advance of board meetings, and what confidentiality protections apply to the observer. Vague drafting here creates ongoing governance friction.
Key Takeaways
- Build the stack before you build the story. Map every layer (senior debt, mezzanine, seller note, equity) against your EBITDA, leverage limits, and dilution tolerance before approaching any capital provider.
- Quantify the gap with arithmetic, not intuition. The gap capital quantum is the residual after senior debt capacity and seller participation are fully deployed. Model it precisely and stress-test it in your downside scenario.
- Mezz providers underwrite to equity value creation, not asset coverage. Your materials must demonstrate EBITDA accretion, free cash flow durability, and a credible exit or refinancing pathway.
- Run a parallel process, never a sequential search. Competitive tension among four to six simultaneous providers is the primary tool for improving both price and structural terms.
- Negotiate on total cost of constraint, not coupon rate alone. Covenant design, warrant structure, PIK flexibility, and prepayment terms collectively determine how much operational freedom the capital stack preserves after close.


