
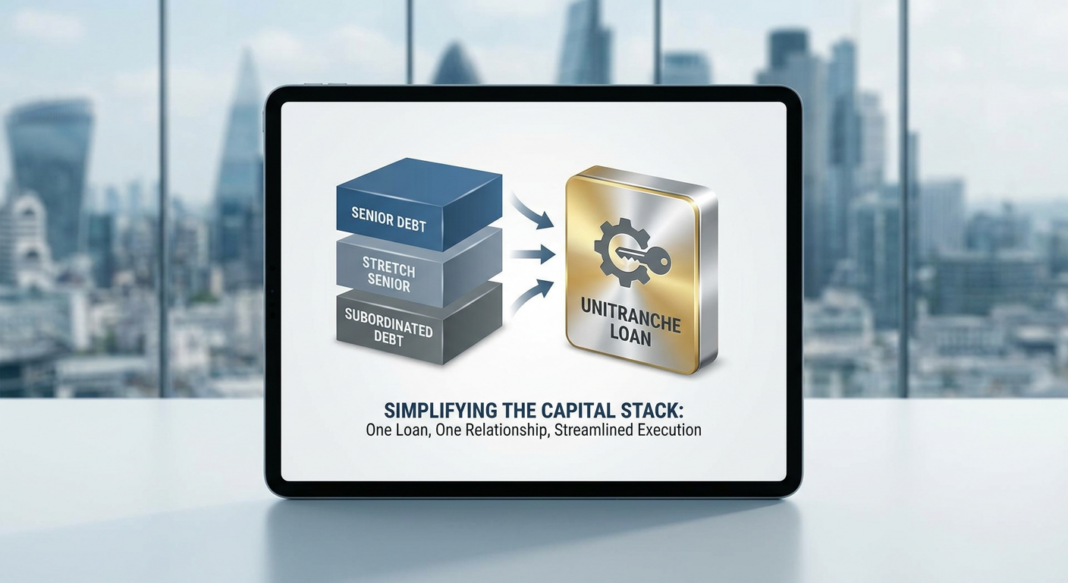
Why One Loan Changed Everything
Picture a mid-market business owner closing a $150 million leveraged buyout. Under the traditional playbook, their financing team would spend weeks negotiating with a senior lender, a second-lien lender, and possibly a mezzanine provider: three separate sets of documents, three pricing conversations, three intercreditor agreements, and three competing interests the moment anything goes wrong. Then along came the unitranche loan, and the entire conversation changed.
The unitranche is arguably the most consequential structural innovation in modern private credit. It collapsed multiple layers of the capital stack (senior debt, stretch senior, and sometimes subordinated debt) into a single facility with one interest rate, one set of covenants, and one lending relationship. For business owners, it dramatically simplified the borrowing process. For private credit funds, it unlocked a dominant position in middle-market deal financing that banks have struggled to reclaim ever since.
Understanding how the unitranche works (and why it has become the preferred instrument for sponsor-backed transactions) is foundational knowledge for anyone operating in or evaluating private credit today.
The Mechanism: One Loan, Two Realities
A unitranche loan is a single-facility debt structure that combines what would traditionally be separate senior and subordinated debt layers into one loan with one set of documents, one interest rate, and one lender relationship. The borrower signs one credit agreement, negotiates one set of covenants, and makes one interest payment. What happens behind the scenes is a different story entirely.
When multiple lenders participate in a unitranche, they often split the facility into a “first-out” and “last-out” tranche through a confidential document called the Agreement Among Lenders (AAL). The borrower never sees this agreement. First-out lenders receive priority on scheduled interest, principal amortization, and prepayments, functioning like a senior lender. Last-out lenders absorb losses first in a default scenario but receive a higher blended yield in exchange for bearing that additional risk.
The AAL establishes the waterfall payment schedule and allocation of fees and interest between the lender groups. In a bankruptcy, the loan still appears as a first-lien facility, the two lender groups must settle their relative recovery rights privately according to the AAL terms.
The pricing borrowers see is a single blended rate: typically higher than pure senior debt but lower than or equal to what second-lien debt would cost. This is why the structure is often called a “stretch senior” in practice: the lender is stretching further up the leverage curve than a traditional senior lender would, and pricing the incremental risk into a single blended coupon.
A Concrete Example: The Numbers in Practice
Consider a private equity sponsor acquiring a software business with $20 million in EBITDA at a 10x multiple, a $200 million enterprise value. The sponsor contributes $80 million in equity (40% equity cushion) and needs $120 million in debt financing at 6.0x EBITDA.
Under a traditional two-lender structure, the deal might look like this:
- First-lien term loan: $80 million at SOFR + 400 bps (4.5x EBITDA)
- Second-lien term loan: $40 million at SOFR + 775 bps (2.0x incremental EBITDA)
- Two separate credit agreements, two sets of covenants, an intercreditor agreement, and a closing timeline of 8–12 weeks
Under a unitranche structure, the same deal consolidates into:
- Single unitranche facility: $120 million at SOFR + 550 bps (blended rate)
- One credit agreement, one maintenance covenant, one lender group, and a closing timeline as short as 3–4 weeks
- The lead lender’s AAL privately splits the facility into, say, $80 million first-out at SOFR + 425 bps and $40 million last-out at SOFR + 800 bps
The borrower pays a modest premium in spread, perhaps 25 to 75 basis points more than the blended cost of a bifurcated structure, but gains certainty of execution, simplicity of documentation, and speed to close. For sponsors in competitive auction processes, that speed premium is often worth far more than the extra basis points.
Current Market Relevance
The unitranche structure has moved from niche innovation to market standard. The data tells a compelling story about both its scale and its current pricing dynamics.
Scale of the market: According to Private Equity Bro (October 2025), global private credit assets under management reached approximately $2.1 trillion in 2025, with unitranche dominating direct lending for cash flow leveraged buyouts in the core and upper middle market. According to S&P Global Market Intelligence (November 2025), Preqin projects private credit AUM to nearly double to $4.5 trillion by 2030 from an estimated $2.3 trillion in 2025.
Pricing in 2025–2026: According to PitchBook LCD (April 2025), in February 2025, nearly 45% of market participants said a unitranche loan to a $50 million EBITDA business in a non-cyclical industry would price below SOFR + 500 bps. By early April 2025, following tariff uncertainty and equity market volatility, only 8% said such a loan would price below that threshold, a dramatic shift in lender expectations. According to PitchBook (March 2026), the WWEX Group’s $4.815 billion unitranche led by Ares Capital priced at SOFR + 575 bps in Q1 2026, reflecting the lender-friendly repricing now underway in large-cap unitranche deals.
Bank retreat creates the opening: According to the Federal Reserve April 2026 SLOOS, banks reported tighter lending standards for commercial and industrial loans across firms of all sizes during Q1 2026, with significant net shares of banks also citing higher premiums on riskier loans, stricter covenants, and lower maximum credit line sizes. This sustained tightening cycle, documented across multiple consecutive SLOOS surveys, is the structural tailwind that keeps private credit lenders in the driver’s seat on middle-market transactions.
Returns outlook: According to Northleaf Capital (May 2026), direct lending continues to generate high single-digit unlevered asset returns, with new loans repricing approximately 25 basis points higher in Q1 2026 than in Q4 2025. According to Morgan Stanley Investment Management (December 2025), asset yields on directly originated first-lien loans are expected to trough in the 8.0%–8.5% range in 2026, even accounting for modest spread compression.
| Metric | Data Point | Source |
|---|---|---|
| Global Private Credit AUM (2025) | ~$2.1 trillion | Private Equity Bro, Oct 2025 |
| Projected Private Credit AUM (2030) | ~$4.5 trillion (Preqin est.) | S&P Global / Preqin, Nov 2025 |
| Large-cap unitranche pricing (Q1 2026) | SOFR + 575 bps (WWEX / Ares) | PitchBook LCD, Mar 2026 |
| Direct lending unlevered yield (2026 est.) | 8.0%–8.5% trough (first-lien) | Morgan Stanley IM, Dec 2025 |
| Bank C&I lending standards (Q1 2026) | Net tighter for all firm sizes | Federal Reserve SLOOS, Apr 2026 |
Decision Framework
For Investors Evaluating Unitranche Exposure
Investors considering unitranche exposure through a business development company (BDC), direct lending fund, or private credit fund-of-funds evaluate several structural dimensions:
- First-out vs. last-out position: Investors analyze whether the fund holds first-out paper (lower yield, higher recovery priority) or last-out paper (higher yield, absorbs first loss behind the equity cushion). Some BDCs disclose their last-out concentration: Ares Capital’s portfolio, for instance, carries meaningful unitranche concentration across its loan book.
- Leverage attachment point: How far up the capital structure does the unitranche stretch? A facility attached at 4.0x EBITDA through 6.0x carries different risk than one from 3.0x through 5.0x. Investors examine leverage multiples, interest coverage ratios, and free cash flow conversion rates as core underwriting metrics.
- Spread-to-risk compensation: In the current repricing environment, investors consider whether widening spreads are adequately compensating for incrementally higher leverage or sector-specific risk, particularly in technology-exposed and consumer-facing businesses.
- Documentation quality: The strength of the AAL (its default waterfall, voting rights, and amendment thresholds) matters enormously. AALs have been tested in fewer bankruptcy proceedings than traditional intercreditor agreements, which investors treat as a structural risk factor.
For Operators Deciding Whether to Use a Unitranche
Business owners and CFOs evaluating a unitranche against traditional bifurcated structures weigh the following:
- Speed and certainty: Unitranche financing can close 30 to 45 days faster than a syndicated alternative, a meaningful advantage in competitive acquisition processes or time-sensitive recapitalizations.
- Simplicity of ongoing management: One lender relationship, one amendment process, and one reporting counterparty reduces operational complexity across the life of the loan.
- All-in cost premium: Operators evaluate whether the 25–75 basis point premium over a bifurcated structure is justified by execution certainty. For many middle-market borrowers in the current bank-tightening environment, the math often favors the unitranche.
- Covenant structure: Unitranche facilities typically include a single maintenance financial covenant (commonly a total leverage or interest coverage test), compared with potentially multiple covenant packages in a traditional multi-lender structure.
Key Takeaways
- Structure, not just rate: The unitranche’s value proposition is structural simplicity and execution certainty, not just pricing. Operators and investors evaluate all-in economics including closing speed, covenant flexibility, and relationship management.
- One loan, hidden complexity: The Agreement Among Lenders (AAL) creates a synthetic senior/subordinated structure invisible to the borrower. Investors in unitranche paper must understand whether they hold first-out or last-out exposure, the risk and return profiles differ significantly.
- Bank retreat is structural, not cyclical: Consecutive quarters of tightening C&I lending standards documented by the Federal Reserve SLOOS confirm that banks are not temporarily absent from middle-market lending, private credit has filled a structural gap, not just a cyclical one.
- Spreads are repricing in 2026: After plateauing near multi-year lows through much of 2025, unitranche spreads are widening materially in the current risk-off environment. Investors entering the asset class now face a more lender-friendly dynamic than at any point in the past two years.
- Market scale demands discipline: With private credit AUM approaching $2.1 trillion and projected to nearly double by 2030, the volume of capital chasing unitranche transactions creates its own risk. Investors evaluate whether managers are maintaining underwriting discipline on leverage multiples, equity cushions, and covenant protections, not just deploying capital to put money to work.


