
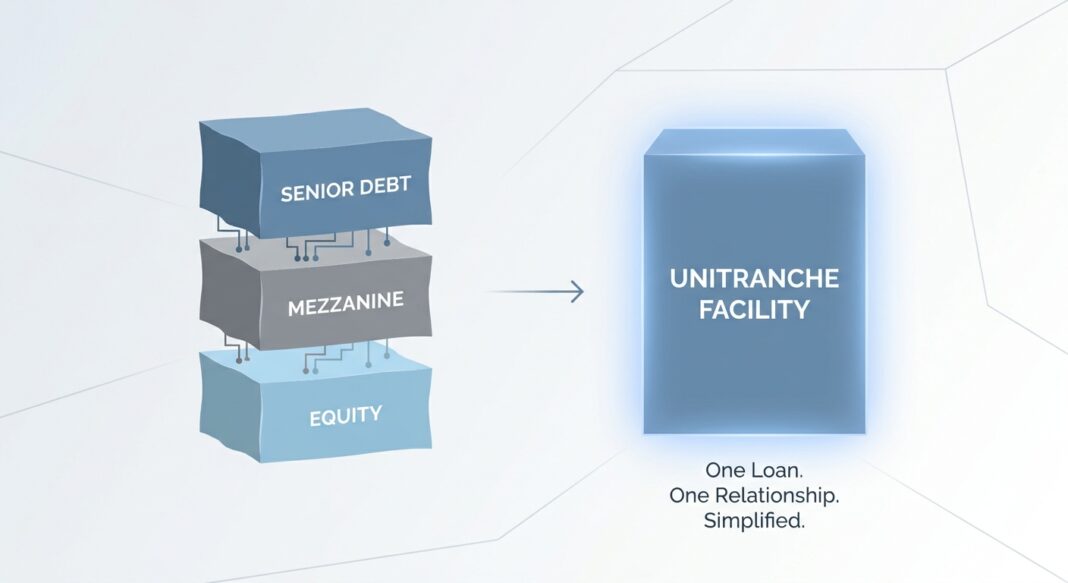
Why the Capital Stack Just Got Simpler
For decades, the rulebook of middle-market lending read like a layer cake: a bank provides senior secured debt, a mezzanine fund fills the gap, and a private equity sponsor supplies equity at the top (or rather, the bottom) of the risk spectrum. Each layer came with its own lender, its own lawyer, its own intercreditor agreement, and its own closing timeline. For a business owner trying to fund a $75 million acquisition, the process could take months and generate hundreds of pages of conflicting documentation.
Then came the unitranche: a single-facility structure that collapses senior and subordinated debt into one loan, one interest rate, one agreement, and one lending relationship. What was once a niche product pioneered by a handful of Business Development Companies (BDCs) has become the dominant financing instrument in the U.S. middle market. Understanding how it works (and when it serves investors and operators best) is foundational knowledge for anyone operating in or allocating to private credit today.
What a Unitranche Loan Actually Is
A unitranche facility combines what would otherwise be a first-lien senior term loan and a subordinated mezzanine note into a single credit instrument issued by one direct lender or a coordinated club of private credit managers. The borrower sees one interest rate, signs one credit agreement, and manages one lending relationship. Behind the scenes, when multiple lenders participate, they govern their relative seniority through an internal document called an Agreement Among Lenders (AAL): invisible to the borrower but critical to how recoveries are allocated in a workout.
As defined in SEC filings from funds like Nuveen Churchill Private Capital Income Fund, unitranche loans are first lien instruments that may extend deeper into a company’s capital structure than traditional first lien debt, with security interests typically comprising first-priority liens on substantially all of the borrower’s assets, including the equity interests of domestic subsidiaries. Total leverage commonly runs 4x to 6x EBITDA, with blended all-in interest rates in the lower middle market currently ranging from approximately 8% to 11% (equivalent to roughly SOFR + 500 to 700 basis points in 2026 pricing environments).
Three structural features define the unitranche and differentiate it from layered alternatives:
- Single credit agreement: One set of representations, covenants, and default triggers rather than competing documents from senior and mezzanine lenders.
- Blended pricing: The borrower pays one interest rate that blends the cost of what would have been first-lien and second-lien capital, typically priced below standalone mezzanine but above standalone senior bank debt.
- Retained covenant protection: Unlike broadly syndicated loans where covenant-lite structures now represent 21% of direct lending deals (up from 4% in 2023 per McKinsey’s 2025 Private Credit analysis), the core middle market unitranche still typically retains at least one financial maintenance covenant, usually a total leverage or interest coverage test.
How It Works: A Concrete Example
Consider a private equity sponsor acquiring a specialty manufacturing business with $10 million in EBITDA at a 7x enterprise value multiple, a $70 million total transaction.
Under the traditional layered approach, the structure might look like this:
- Senior bank debt: $30 million at 3x EBITDA, priced at SOFR + 275 bps (~7.5% all-in)
- Mezzanine note: $15 million at 1.5x EBITDA incremental leverage, priced at 13–14% (often part cash, part PIK)
- Sponsor equity: $25 million
- Total: Three parties, two intercreditor agreements, 90–120 days to close, and a borrower managing two very different sets of lender expectations post-close.
Under the unitranche approach, a single direct lender provides:
- Unitranche facility: $42 million at 4.2x EBITDA, priced at SOFR + 550 bps (~9.2% all-in in today’s rate environment)
- Sponsor equity: $28 million
- Total: One party, one agreement, 30–45 days to close.
The borrower pays a higher rate than they would on the senior tranche alone, but meaningfully lower than the blended cost of senior plus mezzanine stacked. The sponsor gains speed, certainty of close, and simplicity of ongoing covenant management. The lender, in exchange for that convenience premium, takes on slightly deeper structural risk but holds first-lien collateral across the entire facility.
The speed advantage is real and operationally significant. Unitranche facilities simplified ongoing portfolio management, particularly during covenant modifications or add-on acquisitions, a key reason sponsors have embraced the structure for their platform companies executing buy-and-build strategies.
Current Market Relevance
The unitranche is no longer an innovation; it is the infrastructure of the U.S. middle market. The structural forces driving its dominance are accelerating in 2026, not receding.
Bank retrenchment is structural, not cyclical. The Federal Reserve’s April 2026 SLOOS reported that banks tightened standards across all categories of commercial and industrial loans in Q1 2026, with significant net shares reporting higher premiums on riskier loans, stricter covenants, and shorter maximum maturities. This is consistent with a multi-year pattern: bank lending standards tightened for businesses of all sizes through Q4 2025 as well, citing economic uncertainty and reduced risk tolerance.
Direct lending has filled the vacuum, at scale. The U.S. private credit market exceeded $1.6 trillion as of year-end 2024, according to the Office of Financial Research, larger than the combined domestic markets for broadly syndicated loans and high-yield corporate bonds. Moody’s projects AUM exceeding $2 trillion in 2026 and approaching $4 trillion by 2030.
Unitranche pricing has become a lender’s market, again. After a period of tight spreads driven by excess capital chasing limited deals, conditions are shifting. Spreads have widened roughly 50 to 100 basis points since late 2025 according to PitchBook data cited by Lord Abbett, as M&A activity surged and deal flow improved. New private credit loans priced approximately 25 basis points higher in Q1 2026 relative to Q4 2025, per Northleaf Capital’s Q1 2026 market update.
The deal machine is running. Leveraged buyout financings above $500 million hit a record 189 deals in Q4 2025, up from 118 in the same period of 2024, per Octus data, with large unitranche facilities anchoring many of the largest transactions. The unitranche market grew from approximately $20 billion in annual issuance in 2015 to over $200 billion in 2025, as direct lenders systematically displaced bank syndication for sub-$1 billion EBITDA borrowers.
| Metric | Data Point | Source |
|---|---|---|
| US Private Credit AUM (YE 2024) | >$1.6 trillion | OFR Brief 26-02, March 2026 |
| Unitranche All-In Rate (Lower Middle Market, 2026) | SOFR + 500–700 bps (~8–11%) | CT Acquisitions, June 2026 |
| Upper Middle Market Unitranche Pricing | SOFR + 425–475 bps | ABF Journal / Capstone Partners, Aug. 2025 |
| Spread Widening Since Late 2025 | ~50–100 bps higher | Lord Abbett / PitchBook, June 2026 |
| Covenant-Lite Share of Direct Lending (2025) | 21% of deals (up from 4% in 2023) | McKinsey Global Private Markets Report, June 2026 |
Decision Framework: Investors and Operators
For Investors Evaluating Unitranche Exposure
Unitranche loans occupy a distinct risk-return position in a private credit portfolio. Investors considering exposure through BDCs, direct lending funds, or separately managed accounts may evaluate several dimensions:
- Structural seniority vs. stated seniority: A unitranche is classified as first-lien, but the facility may extend to leverage levels (5x–6x EBITDA) where traditional senior lenders would stop. Investors evaluate whether the collateral coverage justifies the leverage multiple, a 4x unitranche on a stable cash-flow business is structurally very different from a 5.5x unitranche on a growth-oriented software company with high EBITDA adjustments.
- Covenant quality as a leading indicator: The drift toward covenant-lite documentation at the upper end of the market warrants scrutiny. Most middle market unitranche facilities retain at least one financial maintenance covenant, that covenant is an early warning system. Investors may consider whether a fund’s portfolio retains meaningful maintenance tests or has migrated toward incurrence-only protections.
- Manager concentration and deal flow: Blackstone Credit closed 225 deals in 2025 with a 5.4% share of direct lending market volume. Scale creates origination advantages, but investors also evaluate whether concentration risk at the manager level (or the portfolio company level) is appropriately diversified.
- Return vs. spread compression: Global new-issue direct loan median spreads fell from 716 bps in March 2023 to 544 bps by year-end 2025. The recent spread widening of 50–100 bps may partially restore yield, but investors compare current all-in returns against the historical baseline tracked by indices like the Cliffwater Direct Lending Index, which recorded 9.3% total returns in 2025 with 10.4% interest income.
For Operators and Business Owners
For a business owner or CFO evaluating a unitranche for a recapitalization, acquisition, or growth financing, the framework centers on cost, flexibility, and covenant fit:
- When unitranche wins: Speed and certainty matter most: competitive auctions, add-on acquisitions, and founder liquidity events where a 90-day bank process creates unacceptable risk. Unitranche financing combines senior and subordinated debt into a single credit facility governed by one loan agreement, simplifying the borrowing process and often accelerating deal timelines versus multi-tranche structures.
- When to weigh alternatives: If a business qualifies for competitive bank pricing and timeline pressure is low, the blended unitranche rate will likely exceed what a bifurcated bank senior + seller note or subordinated SBA structure could deliver. Operators evaluate the cost premium of unitranche convenience against the operational complexity of managing multiple lender relationships.
- Covenant negotiation is leverage: With lenders competing for mandates in a supply-rich market, covenant packages are negotiable. Operators benefit from understanding exactly which financial maintenance tests are included, what the cure rights are, and whether the agreement allows for EBITDA add-backs that give headroom during integration periods.
Key Takeaways
- One loan, one relationship: Unitranche structures collapse the traditional senior-mezzanine capital stack into a single facility, offering borrowers simplicity, speed, and certainty of execution in exchange for a blended interest rate above standalone senior debt.
- Bank retrenchment is the structural tailwind: Persistent tightening in bank C&I lending standards, confirmed across multiple consecutive Federal Reserve SLOOS surveys through Q1 2026, continues to push middle-market borrowers toward direct lenders offering unitranche financing.
- Pricing is moving in lenders' favor: After years of spread compression, unitranche pricing has widened roughly 50–100 basis points since late 2025, improving return prospects for disciplined private credit investors entering at current levels.
- Covenant quality is a hidden variable: As covenant-lite structures grow (from 4% to 21% of direct lending deals between 2023 and 2025) investors should scrutinize whether maintenance covenants remain in place, as these are the primary early-warning mechanism for detecting borrower stress before a default materializes.
- Scale matters at the manager level: The unitranche market has become dominated by large-platform direct lenders with origination scale, relationship networks, and workout infrastructure. Manager selection, not just strategy selection, is a primary determinant of risk-adjusted outcomes in this asset class.


