
The $3.5 Billion Lesson: When Debt Holders Become Owners
In the world of corporate finance, there remains a persistent myth: equity is where the power lies, and debt is merely a utility, a silent partner that provides fuel and asks only for interest payments in return.
The saga of Pluralsight, a workforce development company, shatters this illusion. It stands as a definitive case study of the mid-2020s correction, illustrating exactly what happens when a capital structure designed for perfect weather meets a high-rate storm.
For founders and operators, the story of Pluralsight is not just high finance gossip; it is a structural warning about the absolute priority of credit and the binary nature of leverage.
The Setup: A Classic Buyout
In 2021, the market was awash in liquidity. Valuations were high, and debt was cheap. In this environment, Vista Equity Partners acquired Pluralsight in a take-private deal valued at roughly $3.5 billion. The thesis was standard for the era: take a high-growth software company private, apply operational discipline, and use leverage to amplify returns.
The capital stack was heavy on debt, provided by a consortium of heavyweight private credit lenders including Blue Owl Capital, Ares Management, and Golub Capital. At the time, this was hailed as a victory for private credit, proving that non-bank lenders could write massive checks to rival Wall Street banks.
But then the macroeconomic tide turned. Interest rates climbed aggressively through 2022 and 2023, increasing the cost of floating-rate debt. Simultaneously, the tech sector cooled, compressing growth rates. Pluralsight found itself caught in a pincer movement: rising debt service costs and slowing revenue growth.
The Decision: Engineering vs. Economics
By early 2024, the math wasn’t working. The company faced a liquidity crunch. In a high-stakes attempt to preserve its equity value, the sponsor initiated a controversial financial maneuver known as a “drop-down.”
In this scenario, a company moves valuable assets (like intellectual property) into a new subsidiary that isn’t bound by the original loan agreements. This subsidiary can then borrow new money against those assets to pay the old lenders or fund operations. It is a piece of financial engineering designed to buy time.
According to reports from Goodwin Law and market analysis in 2024, Pluralsight moved IP into a restricted subsidiary to facilitate a cash injection. It was a play to stay alive and keep the equity option open.
However, unlike passive bank syndicates of the past, modern private credit lenders are sophisticated, active asset managers. They did not sit idly by while their collateral was diluted.
The Outcome: The Keys Handed Over
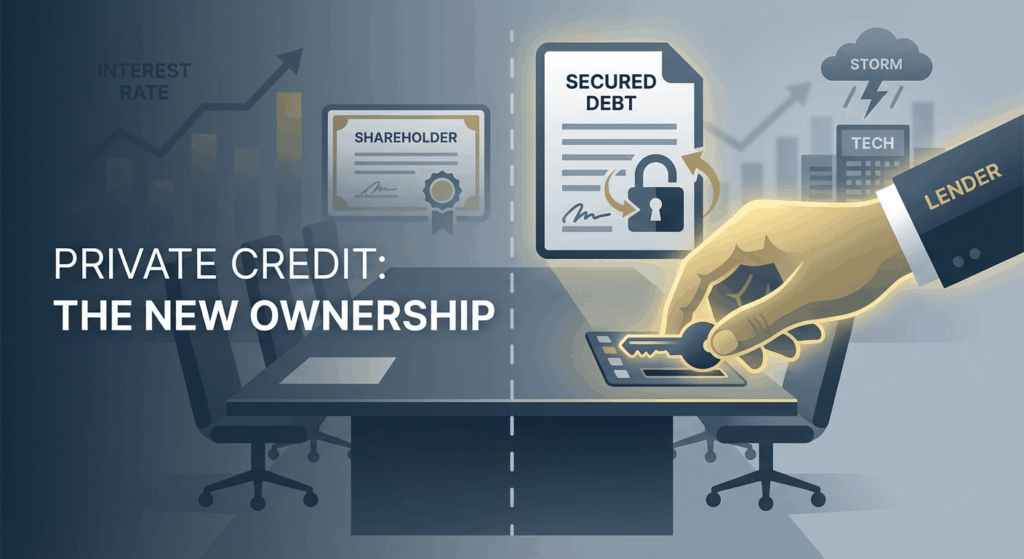
The maneuver triggered a confrontation. The lenders, led by Blue Owl, held the ultimate trump card: the senior secured claim on the business.
By August 2024, the standoff ended decisively. As reported by BNN Bloomberg, the lender group agreed to a recapitalization that wiped out the sponsor’s equity entirely. The lenders exchanged their debt for 100% equity ownership of the company.
The result was stark:
- Sponsor Outcome: Total loss of the original equity investment.
- Lender Outcome: The debt was extinguished, but they now owned the company, effectively converting their loan into a control position. They also injected new capital to stabilize the balance sheet.
- Company Outcome: Pluralsight continued to operate, but with a new board and new owners focused on recouping their principal through operations rather than financial engineering.
The Lessons: Absolute Priority Rules
This case elucidates the fundamental difference between the “soft” pressure of venture dilution and the “hard” wall of debt covenants.
1. Debt is Binary
When a venture-backed company misses targets, it raises a down-round. The founders suffer dilution, but they live to fight another day. When a leveraged company breaks its covenants or runs out of cash, the game ends. The ownership transfers instantly to the creditors. In the hierarchy of capital, debt always eats first.
2. The “Loan-to-Own” Dynamic
Founders often view private credit funds merely as sources of capital. Pluralsight demonstrates that these funds are also asset managers. If a deal goes south, they have the operational capability to take the keys and run the business. As recent analysis on credit markets suggests, the distinction between lending and owning is becoming increasingly porous in distressed scenarios.
3. Valuation Discipline is a Solvency Issue
Leverage acts as a magnifier. A 5x leverage ratio on a company growing at 30% is a rocket ship. The same ratio on a company growing at 5% is an anchor. The Pluralsight deal was underwritten at peak valuations; when the multiple compressed, the equity value evaporated, leaving the debt as the only real value in the capital stack.
The Founder’s Framework
If you are a founder considering debt (whether a small term loan or a massive recapitalization) understand the incentives of your counterparty.
- Know Your Covenants: Understand exactly what triggers a default. It isn’t just missing a payment; it can be a dip in EBITDA or a breach of liquidity ratios.
- Align Duration with Reality: Never use short-term or floating-rate debt to fund long-term, uncertain growth. The duration mismatch is what kills companies during rate hike cycles.
- Respect the Seniority: Remember that in a downside scenario, your equity is the buffer that protects the lender. If that buffer wears thin, the lender will act to protect their principal, even if it means washing you out.
Pluralsight serves as a reminder that capital structure is strategy. It is not just about how much money you raise, but the terms on which you accept it, and the strict discipline required to service it.
Key Insights
- Equity is a cushion: Once equity value drops below the debt value, the lenders are the de facto owners.
- Smart lenders don’t blink: Private credit funds are increasingly willing to “take the keys” rather than extend-and-pretend on bad loans.
- Financial engineering has limits: tactics like “drop-downs” can backfire if they antagonize the creditor class holding the senior security.
- Rate risk is real: Floating rate debt can turn a healthy P&L into a distressed one rapidly; hedging or fixed rates are effectively insurance premiums.
- Control is contractual: You only control your company as long as you seek no permission from creditors; once covenants trip, control moves to the credit agreement.


