
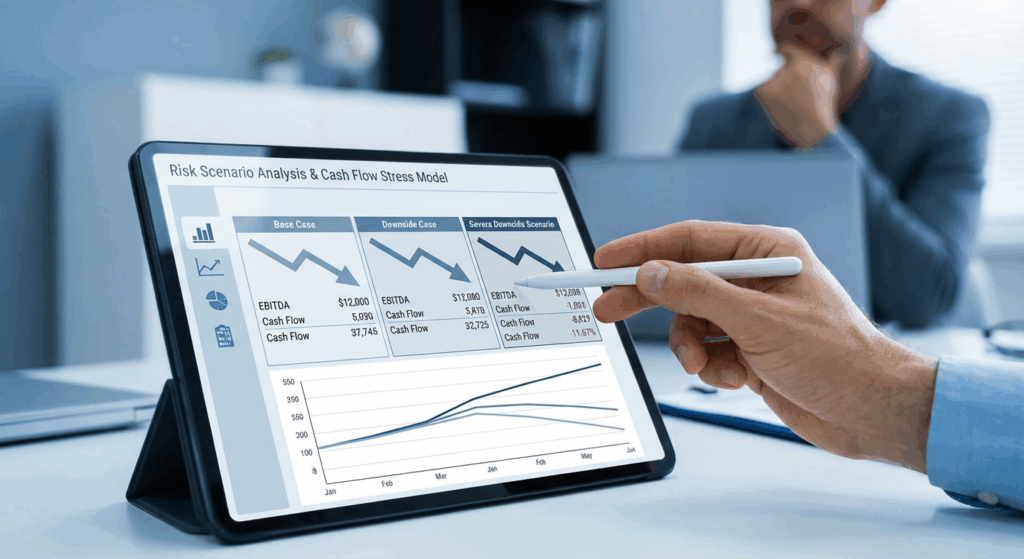
The Underwriting Question Every Credit Officer Must Answer
Before a single dollar is deployed into a private credit transaction, one question must be answered with precision: How much revenue decline, margin compression, or working capital disruption can this borrower absorb before it cannot service its debt?
In today’s private credit environment, that question is more urgent than ever. According to data cited by ainvest.com, the share of “bad PIKs”, retroactive conversions of cash interest to payment-in-kind, surged from 36.7% in Q4 2021 to 57.2% by Q3 2025. These conversions are not structural features; they are distress signals. They indicate that borrowers who looked credit-worthy at origination could not sustain cash interest payments as conditions tightened. The failure, in most cases, begins with underwriting that did not stress the cash flow model hard enough.
Stress testing is not a regulatory checkbox. It is the analytical core of sound private credit underwriting, the discipline that separates recoverable credits from impaired ones before capital is at risk.
The Analytical Framework: Three-Scenario Cash Flow Stress Testing
Institutional-quality stress testing is built on a three-scenario model applied consistently across the underwriting period: a Base Case, a Downside Case, and a Severe Downside Case. Each scenario must be independently justified, not simply a percentage haircut applied uniformly to revenue.
Step 1: Anchor to Normalized EBITDA
Begin with a carefully normalized EBITDA figure. Strip out all non-recurring items, management add-backs that lack economic substance, and one-time cost savings that have not yet been demonstrated in the financial statements. The private credit market has suffered from aggressive EBITDA normalization; the discipline here is to be conservative and documented. Current debt capacity benchmarks, per ibinterviewquestions.com, place total leverage in most private credit deals at 4.0x to 5.0x EBITDA, a compression from the 6.0x+ levels seen in prior cycles, reflecting market-wide recognition that inflated EBITDA creates structural fragility.
Step 2: Build the Driver-Based Revenue Model
Do not stress revenues at the top line. Instead, decompose revenue into its constituent drivers: unit volume, average selling price, customer retention rate, and contract renewal cadence. Stress each driver independently with justified assumptions. For a B2B SaaS borrower, for example, the key drivers are net revenue retention and logo churn, not blended revenue growth.
Step 3: Model the Three Scenarios
Apply the following structure to a $10M EBITDA manufacturing company carrying 4.5x leverage ($45M total debt):
Scenario Analysis: $10M EBITDA / $45M Debt Manufacturing Borrower
| Metric | Base Case | Downside Case | Severe Downside |
|---|---|---|---|
| Revenue Growth | +5% | -8% | -20% |
| EBITDA Margin | 22% | 18% | 13% |
| Stressed EBITDA | $10.5M | $6.6M | $3.7M |
| Total Leverage (Debt/EBITDA) | 4.3x | 6.8x | 12.2x |
| Interest Coverage (EBITDA/Cash Interest) | 2.9x | 1.8x | 1.0x |
| Covenant Headroom (DSCR vs. 1.20x floor) | Ample | At Risk | Breach |
The severe downside scenario, a 20% revenue decline paired with meaningful margin compression, produces a leverage profile exceeding 12x. At that level, the credit is functionally impaired. The underwriter’s job is to determine whether that scenario is plausible, not merely theoretical, before committing capital.
Identifying Issues: Where the Model Breaks Down
The stress test is most valuable not as a pass/fail gate but as a diagnostic tool. Three calculations deserve particular scrutiny:
Free Cash Flow Conversion Under Stress
Calculate free cash flow as: Stressed EBITDA – Cash Interest – Mandatory Amortization – Maintenance CapEx – Change in Working Capital. In a downside scenario, working capital typically becomes a use of cash as inventory builds and receivables stretch. A borrower with 80% EBITDA-to-FCF conversion at baseline may convert as little as 40% under stress, a critical distinction when evaluating whether the company can self-fund through a downturn without drawing on its revolver.
Debt Service Coverage Ratio (DSCR)
Institutional lenders commonly set a DSCR maintenance covenant floor of 1.10x to 1.25x. When the stress model shows DSCR falling to 1.0x in the downside case, as in the example above, the covenant provides almost no early-warning buffer. The underwriter should either tighten the covenant trigger or require a larger equity cushion at close.
Liquidity Runway Analysis
Project the revolver draw timeline under the severe downside scenario. If the borrower exhausts its revolving credit facility within 12 months of revenue contraction, the lender has no time for operational intervention before a restructuring event. The private credit market has seen precisely this dynamic play out as “bad PIK” conversions accelerate, borrowers defer cash interest not by design but because revolver availability has been consumed. Per ainvest.com, this pattern of retroactive PIK conversion signals deteriorating credit quality rather than a planned capital structure feature.
What Institutional Lenders Require, and Where Underwriting Fails
The highest-performing private credit platforms consistently apply the same disciplines at origination. According to market data cited by ainvest.com, private credit delivered 8.6% net IRR against only 0.4% in losses versus 1.1% for leveraged loans, a performance differential attributable in large part to senior secured structuring and underwriting rigor. That edge erodes when competitive pressure drives covenant-lite structures and aggressive EBITDA normalization.
Private Credit Risk Data Points (2025–2026)
- Bad PIK share of private credit: 57.2% in Q3 2025, up from 36.7% in Q4 2021, ainvest.com
- Private credit AUM: $1.67 trillion in 2025, projected to reach $2.9T by 2030 at an 11.62% CAGR, ainvest.com
- Current LBO leverage benchmarks: 4.0x–5.0x EBITDA, compressed from 6.0x+ in the prior cycle, ibinterviewquestions.com
- Private credit loss rate: 0.4% vs. 1.1% for broadly syndicated leveraged loans (net, historical), ainvest.com
- TPG–OneMain $2.4B forward-flow consumer agreement reflects private credit’s expansion into asset-based consumer lending, requiring new stress frameworks beyond corporate EBITDA-based models, ainvest.com
Common Red Flags That Underwriters Miss
- Normalized EBITDA exceeds reported EBITDA by more than 15–20%: Aggressive add-backs signal management’s willingness to present an optimistic picture. Each add-back must be independently verified.
- Covenant headroom below 15% in the base case: If the maintenance covenant triggers at 5.5x leverage and the borrower closes at 4.7x, there is effectively no structural protection in even a mild downturn.
- Working capital as an afterthought: Seasonal or growth-driven working capital needs can consume more free cash flow than debt service in stressed periods. Model it explicitly.
- Single-scenario underwriting: Presenting only a base case is not underwriting; it is underwriting theater. Any credit memo without a documented downside scenario should be returned for revision.
- Covenant-lite structures in cyclical industries: The absence of maintenance covenants removes the lender’s contractual right to intervene before a credit deteriorates to the point of restructuring.
The Stress Testing Underwriting Checklist
- Confirm normalized EBITDA: Independently verify each add-back against third-party documentation (QoE report, audited financials, tax returns).
- Decompose revenue by driver: Volume, pricing, customer concentration, contract duration, and renewal rates, stress each independently.
- Build all three scenarios: Base, Downside, Severe Downside. Document the economic justification for each assumption.
- Calculate FCF under each scenario: EBITDA minus cash interest, mandatory amortization, maintenance capex, and working capital change.
- Map covenant triggers to downside scenario: Identify exactly which scenario breaches each maintenance covenant and at what quarter.
- Model revolver availability timeline: Under severe downside, project when liquidity is exhausted and the lender’s intervention window begins.
- Benchmark leverage to current market: Confirm total debt does not exceed 4.5–5.0x normalized EBITDA without explicit structural mitigants (e.g., strong asset coverage, contracted revenues).
- Document the PIK risk: If the structure includes a PIK toggle, model the cumulative balance accrual under a 24-month PIK scenario and confirm enterprise value provides adequate coverage.
- Request management’s own downside plan: A borrower who cannot articulate how they would respond to a 15–20% revenue decline has not stress-tested their own business.
- Present all scenarios to the credit committee: No single-scenario memos. Require sign-off on the downside case assumptions, not just the base case returns.
Key Takeaways for Credit Officers
- 🔍 Stress testing is the underwriting product: The base case return analysis is secondary. The downside scenario determines whether the credit survives a real-world shock.
- 📉 Bad PIK conversions are a stress-test failure: When 57% of PIK provisions are retroactive conversions rather than planned features, it reflects systemic underwriting that did not adequately model liquidity risk at origination.
- 📐 EBITDA normalization must be conservative and documented: Every add-back not supported by third-party evidence should be excluded from the underwriting EBITDA used to size the debt.
- 🔒 Covenant structure must reflect the stress scenario: Set maintenance covenant triggers at levels that provide at least two to three quarters of warning before cash flow becomes impaired.
- 🏗️ Liquidity runway is as important as leverage: A borrower with high leverage but 18+ months of revolver runway under a severe downside gives a lender time to act. A borrower with moderate leverage and six months of liquidity does not.


