
Market Headline: The Repricing Has Arrived, But It Is Not Uniform
After two years in which private credit spreads ground relentlessly toward multi-decade tights, Q1 2026 marked a credible inflection. The convergence of geopolitical shock, the U.S.-Iran military conflict in late February, AI-driven credit-quality reassessment in software, and a wave of retail-channel redemptions at major Business Development Companies (BDCs) pushed the market into what analysts at Valuation Research Corp. describe as “a renewed phase of price discovery.” Source: Valuation Research Corp., April 2026
The macro frame is unambiguous: the Federal Reserve held its target range at 3.50%–3.75% in Q1 2026, and market participants now price in limited easing for the remainder of the year. With base rates anchored at elevated levels, all-in yields on directly originated first-lien senior secured loans are forecast to floor in the 8.0%–8.5% range (Morgan Stanley Investment Management), still in the upper half of their 12-year historical range. For borrowers, this is a meaningfully different cost-of-capital environment than 2021–2023. For disciplined lenders, it is a structural gift.
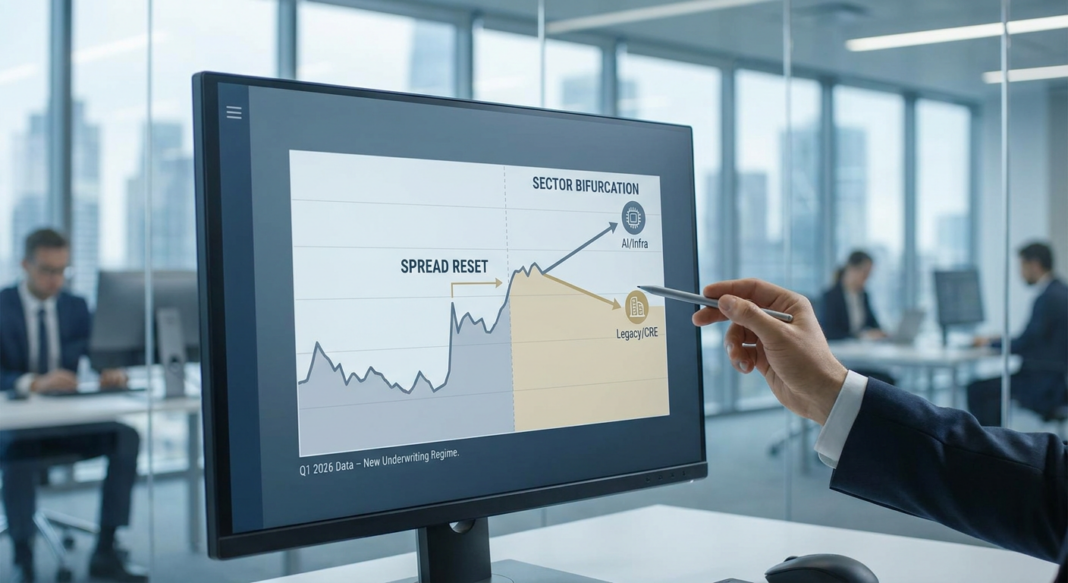
Critically, the repricing is not symmetrical. Hamilton Lane reports that private credit spreads have moved back into the S+500 context, up from the mid-400 bps level that prevailed through much of 2025. The approximately 50–75 bps of spread expansion has been concentrated in AI-exposed, tariff-sensitive, and energy-intensive credits, while defensive infrastructure, asset-based finance (ABF), and healthcare-adjacent lending remain competitive. The implication: borrower quality and sector position now determine credit access more acutely than at any point since the post-pandemic rate-hike cycle.
Quantitative Market Snapshot
The following data box consolidates the most critical current market metrics. All figures reflect Q1 2026 reported or estimated actuals unless otherwise stated.
| Metric | Current Value (Q1 2026) | Prior Period (Q4 2025) | Direction | Source |
|---|---|---|---|---|
| Private Credit Middle Market Spread | S+500 bps (approx.) | S+450–475 bps | ↑ Widening ~25–50 bps on new issues | Hamilton Lane, April 2026 |
| Direct Lending All-In Yield (First Lien) | 8.0%–8.5% | ~9.0%–9.5% peak (2024) | ↓ Normalizing but elevated vs. history | Morgan Stanley IM, December 2025 |
| IG Corporate Bond Spread (OAS) | +89 bps (end Q1 2026) | ~+78 bps (near 20-year tights, Jan 2026) | ↑ +11 bps in Q1 2026 | Breckinridge Capital Advisors, April 2026 |
| BSL / HY New Issue Spread Change | +15 to +30 bps (Q1 vs Q4 2025) | Near century lows (end 2025) | ↑ Early repricing signal | Northleaf Capital / PitchBook LCD, May 2026 |
| U.S. M&A / LBO Deal Volume (Q1 2026 YoY) | +30% vs Q1 2025 (volume $); transaction count ↓ | Q1 2025 base | Fewer, larger transactions | Northleaf Capital, May 2026 |
| Full-Year 2025 Direct Lending Volume | $247B (842 transactions) | $278B (2024 record high) | ↓ 11% YoY; 2nd busiest year on record | PitchBook LCD via DLA Piper, Q1 2026 |
| Private Credit Default Rate (Direct Lending, 2025) | ~1.6%–4.7% (range incl. soft credit events) | ~1.5% (KBRA 2025 base estimate) | ↑ KBRA projects rise to ~2.0% by YE 2026 | KBRA / Northleaf, May 2026; Moody’s, April 2026 |
| Fed SLOOS: Net % Banks Tightening C&I Standards (Large & Middle Market) | Positive net tightening (Q1 2026) | ~5.3% net tightening (Jan 2026 SLOOS) | ↑ Continued tightening bias | Federal Reserve SLOOS, April 2026; FRED / Fed Board of Governors |
Note: S+ denotes spread over 3-month SOFR. SOFR reference rate approximately 3.7% as of publication. All figures sourced from institutional research and regulatory data as cited. Past performance is not indicative of future results.
Sector Analysis: Lender Appetite & Structural Shifts
🟢 Hot: AI Infrastructure & Asset-Based Finance (ABF)
The single most consequential structural shift in private credit in 2026 is the rapid institutionalization of AI infrastructure as a lendable asset class. There are already more than $200 billion of outstanding private credit loans to AI-related companies, with the Bank for International Settlements projecting that total could reach $300–$600 billion by 2030. The financing mechanism is structurally distinct from traditional corporate cash-flow lending: structures typically involve dedicated SPV vehicles capitalized by sponsor equity, raising debt through private placements backed by long-term operating leases and capacity offtake agreements from hyperscalers.
Asset-based finance is now larger than all other private credit markets combined, driven by structural tailwinds including bank retrenchment, insurance demand for rated assets, and AI and data center financing needs. As of May 2026, 695 infrastructure funds were in active fundraising, targeting an aggregate $555 billion of capital, reflecting institutional conviction that this is a durable cycle, not an episodic theme.
🟡 Cautious: Healthcare
Despite healthcare’s traditionally defensive appeal (demographic tailwinds, non-cyclical service models, and stable cash flows attracting lenders) credit performance has deteriorated materially at the portfolio level. Morgan Stanley IM maintains a significant underweight to healthcare, which has led all sectors in loans placed on non-accrual status over the last year. Reimbursement compression, staffing cost inflation, and aggressive leveraging from the 2021–2022 buyout cycle have structurally impaired FCCR coverage ratios across subsectors, prompting lenders to demand tighter covenants, lower leverage multiples, and more robust equity cushions before committing capital.
🔴 Cold: Software / Legacy SaaS & Office CRE
Secondary spreads widened materially in Q1 2026, particularly for technology and software-exposed credits, following the AI-driven reassessment of legacy SaaS business model durability. Lenders are now requiring explicit AI disruption analysis as a core underwriting component for any software credit. An AI strategy and an evaluation of AI’s potential risk on a business have emerged as a critical analytical component both in underwriting new transactions and in ongoing monitoring.
In commercial real estate, the retreat is similarly structural. Private credit lenders are retreating from office property exposure as uncertainty around future demand intensifies, with appetite for office assets having diminished relative to infrastructure-linked segments. New CRE loans that do get done reflect meaningfully improved lender economics: lenders are extending credit at lower LTV ratios of 60–65% versus 70%+ in past cycles, with all-in returns on new senior CRE loans now mathematically capable of reaching 8% or more.
Structural Shift: Underwriting Discipline Returns
Lord Abbett’s mid-2026 outlook flags that non-accruals, PIK usage, sector concentration, and 2021–2022 vintage exposure are now the critical portfolio differentiation indicators, a stark contrast from the covenant-lite, spread-compressed market that prevailed through 2024. Private credit lenders are no longer willing to extend and pretend without significant equity injections or structural enhancements at refinancing, and borrowers with loans maturing from the 2021 peak are confronting a materially reset cost-of-capital environment.
Strategic & Operational Implications
For Borrowers & Operators
The operational implications of the current credit environment are direct. The era of borrower-friendly terms (covenant-lite structures, aggressive leverage multiples, and execution certainty priced below intrinsic risk) has structurally closed. The April 2026 Fed SLOOS confirmed tighter lending standards and basically unchanged or weaker demand for C&I loans across firms of all sizes, limiting the bank channel as an escape valve. For operators navigating near-term refinancings, the message from lenders is unambiguous: demonstrate FCCRs comfortably above 1.2x (with a growing preference for 1.5x+ in cyclical sectors), present credible AI strategy and disruption mitigation plans, and expect enhanced covenant packages as standard rather than exceptional.
Lenders have tightened underwriting standards for energy-intensive industries and businesses whose leverage was predicated on stable energy costs, a direct consequence of geopolitical-driven oil price volatility. Manufacturing, transportation, and industrial operators with high energy cost-pass-through risk should proactively model debt service sensitivity scenarios and engage lenders early, rather than waiting for covenant triggers. The window for voluntary restructuring on favorable terms remains open; it will narrow materially if macro conditions deteriorate further.
For Institutional Investors & Lenders
The repricing creates a genuine lender-favorable window. Elevated redemptions at retail-oriented private credit vehicles have led some large lenders to moderate deployment, creating more attractive supply-demand dynamics for well-capitalized lenders backed by institutional capital. Simultaneously, more deal flow and wider spreads are constructive, but the most durable advantage may come from better documentation, more conservative leverage, and time for thorough stress analysis before deployment.
Allocation strategy should distinguish between (a) senior secured direct lending to sponsor-backed, non-cyclical middle-market businesses (core; FCCR >1.5x; net leverage <5.0x), where the risk-return is currently compelling; (b) ABF and AI infrastructure debt, where specialized underwriting and hard-asset collateral generate structurally differentiated yield; and (c) legacy software and CRE office exposure, where active monitoring and reduced concentration are warranted. Across multiple rate cycles, private credit has delivered 200–400 bps of excess return over liquid credit markets, but that premium is now being earned through genuine underwriting rigor, not market beta.
Forward-Looking View: Next 3–6 Months
A growing wave of new deal demand combined with a large refinancing cycle is expected to gradually overtake private credit supply, allowing disciplined lenders to preserve terms and capture the illiquidity premium over public markets. The critical variable is the trajectory of the federal funds rate: with the Fed on hold at 3.50%–3.75% and geopolitical risk sustaining inflation pressure, any SOFR base rate relief is limited. The combination of elevated base rates and potentially widening spreads presents an attractive outlook for gross private credit yields through year-end. For investors able to deploy at current terms, with appropriate selectivity, vintage 2026 may prove to be among the more attractive entry points of the decade.
Key Market Insights: Actionable Takeaways
- Spread Re-anchoring Is Real, Not Transitory: Middle-market private credit spreads have repriced approximately 50+ bps higher to the S+500 context from mid-2025 lows. New direct lending transactions are pricing ~25 bps higher than pre-Q1 2026 agreement terms. Borrowers locking in refinancings now should benchmark carefully against where the market was twelve months ago, the difference is material at scale. (Hamilton Lane; Northleaf Capital)
- Bank Tightening Is a Durable Tailwind for Private Credit Supply: The April 2026 SLOOS confirmed net tightening of C&I lending standards for Q1 2026, with banks citing uncertain economic outlook, reduced risk tolerance, and regulatory concern as primary drivers. This is not a short-term aberration; it structurally redirects borrower demand toward private lenders. (Federal Reserve SLOOS, April 2026)
- AI Infrastructure Is Rewriting Private Credit 2.0: ABF has surpassed all other private credit sub-strategies in size. With $200B+ in outstanding AI-related private credit loans and a BIS-projected trajectory toward $300–600B by 2030, specialized lenders treating GPUs, data centers, and power facilities as financeable hard assets are operating in a structurally under-supplied capital segment. (DLA Piper Q1 2026; Insurance Journal / BIS)
- Underwriting KPIs Are Being Ratcheted Up Across Sectors: FCCR thresholds, leverage multiples, and covenant intensity are tightening across the board. Lenders are requiring explicit scenario analysis for AI disruption risk, energy cost sensitivity, and 2021-vintage refinancing exposure. Borrowers presenting clean balance sheets (net leverage <4.5x, FCCR >1.5x) are accessing competitive terms; those below those thresholds face meaningfully wider spreads and structural subordination. (Lord Abbett, June 2026; Capstone Partners Q1 2026)
- Capital Concentration Risk Is Bifurcating the Manager Landscape: Total capital raised by non-top-5 private credit GPs fell approximately 50% year-over-year in Q1 2026, while opportunistic strategies surpassed direct lending in fundraising for the first time on record. Goldman Sachs’ $13B mezzanine fund and Benefit Street’s $10B CRE opportunistic fund illustrate where institutional LP capital is flowing: toward scale, optionality, and multi-strategy platforms with proven through-cycle underwriting. (Credit Crunch / PitchBook, April 2026)


