
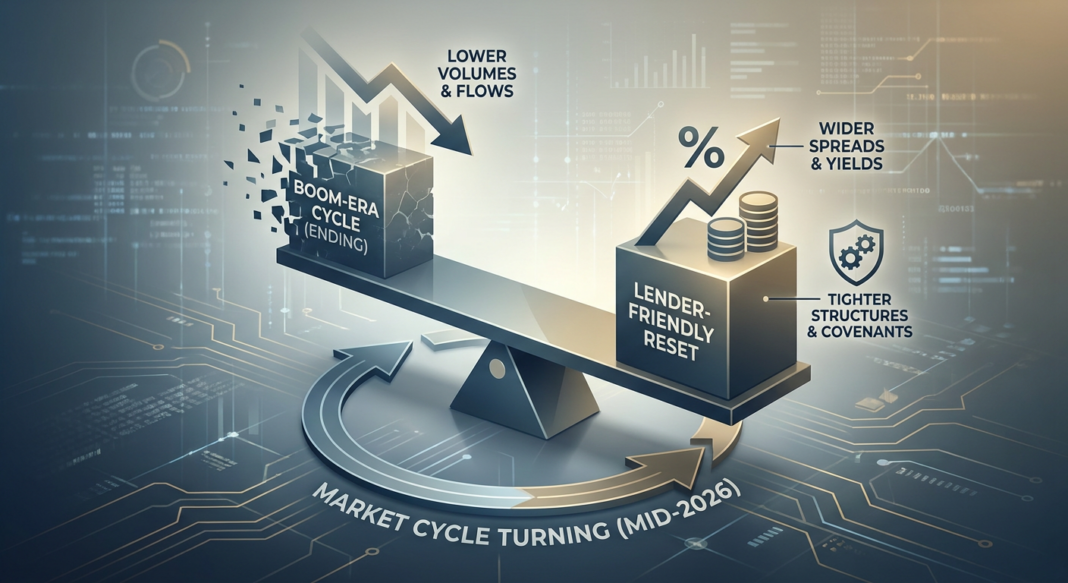
The Cycle Has Turned, and It’s Moving Faster Than Expected
Private credit’s multi-year expansion is undergoing a structural reset in mid-2026, and the data is unambiguous. Deal issuance has fallen sharply, retail capital flows have buckled, and managers at the largest funds are gating redemptions. At the same time, spreads are widening, covenants are returning, and leverage demands are moderating, a combination that marks a meaningful shift in the negotiating balance between borrowers and lenders.
This is not a crisis, but it is a recalibration. The easy-money origination environment of 2021–2024, characterized by compressed spreads, aggressive leverage multiples, and PIK-heavy structures, is giving way to a more disciplined, selective, and structurally sound credit market. For lenders with dry powder and disciplined underwriting, lordabbett.com characterizes today’s environment as potentially more attractive than the tighter conditions that prevailed just six months ago. For borrowers, especially those carrying legacy structures from 2019–2022 vintage deals, the margin for error is narrowing rapidly.
The macro backdrop compounds the challenge. Five-year SOFR has nudged higher to approximately 3.6%, and both the Bank of England and ECB held rates steady at their March meetings as renewed inflation risk pushed rate-cut expectations further out, according to alixpartners.com. In a higher-for-longer environment, floating-rate borrowers who failed to hedge carry meaningfully elevated interest burden, squeezing fixed charge coverage ratios (FCCR) and pressuring debt-service capacity across leveraged portfolios.
Quantitative Market Snapshot
The following data box captures the current state of the private and public credit markets as of June 2026, benchmarked against prior-period comparisons where available.
| Metric | Current Value (Jun 2026) | Prior Period | Change | Source |
|---|---|---|---|---|
| U.S. Private Credit Issuance (3-Month Rolling) | $44.76B (Feb–May 2026) | $74.56B (Q1 2026) | ▼ ~40% | marketscreener.com |
| PE-Backed Borrower Issuance | $28.5B (Feb–May 2026) | ~$45.2B (Q1 2026 est.) | ▼ ~37% | marketscreener.com |
| Direct Lending LBO Volume | $15.15B (Feb–May 2026) | ~$22.9B (Q1 2026 est.) | ▼ ~34% | marketscreener.com |
| Private Credit Spread Movement | +50 to +100 bps wider | Late 2025 baseline | Lender-Favorable | lordabbett.com |
| Leveraged Loan Market Spreads (Active Segment) | ~+100 bps wider (Q1 2026 peak) | January 2026 baseline | ▲ vs. borrowers | sikich.com |
| Private Credit Fundraising (Jan–Apr 2026) | $45B | $52.2B (Jan–Apr 2023) | ▼ 14% vs. 2023 peak | marketscreener.com |
| Target First-Lien All-In Yield (Direct Lending) | 8.0%–8.5% (2026 trough est.) | Upper historical range | Elevated vs. 12-yr avg. | morganstanley.com |
Taken together, these figures paint a picture of a credit market that has materially repriced risk since late 2025: widening spreads, tightening structures, and compressing volumes simultaneously. All-in first-lien yields in the 8.0%–8.5% range remain well above historical medians, according to morganstanley.com, offering yield-seeking institutional capital a structurally sound entry point, provided underwriting discipline is maintained.
Sector Analysis: Software Under Siege, Defensives Gain Lender Favor
The most acute stress in private credit portfolios today is concentrated in software-sector debt, a segment that saw enormous capital deployment in 2021–2022 at aggressive leverage multiples and thin covenants. The Morningstar LSTA U.S. Leveraged Loan Index shows software loans down 4.7% year-to-date through May 31, 2026, compared with a 1.2% gain for the broader index, per marketscreener.com. This underperformance is not merely mark-to-market noise; it reflects genuine revenue model stress in an environment where software growth multiples have compressed and EBITDA quality is under scrutiny from lenders and auditors alike.
The knock-on effect is significant: managers with meaningful software exposure are facing harder questions about non-accruals, PIK usage, and interest coverage. Lenders are responding not just by widening spreads, but by demanding better credit structures across all sectors: fewer PIK elections, reduced leverage, and tighter maintenance covenants, a shift confirmed by lordabbett.com.
In contrast, sectors with durable cash flow visibility (healthcare services, infrastructure-adjacent businesses, and essential consumer) are attracting stronger lender appetite. Lenders are increasingly rewarding borrowers with high fixed charge coverage ratios (FCCR ≥ 1.5x being a more common threshold in current underwriting conversations) and conservative debt-to-equity structures. Meanwhile, borrowers from high-leverage 2021–2022 vintages who have seen flat EBITDA are facing a bifurcated market: refinancing is available, but at materially higher cost and with structural concessions required.
In European mid-markets, the dynamics are similar. Five-year SONIA has jumped approximately 80 basis points to 4.3%, and EURIBOR is up roughly 50 basis points to approximately 2.8%, per alixpartners.com. In that environment, refinancing continues to dominate deal flow, and borrowers without hedged floating-rate exposure are seeing all-in funding costs rise even as spreads compress in certain segments, a toxic combination for FCCR.
One structural wildcard: UK bank re-engagement. The Bank of England’s Financial Policy Committee voted in late 2025 to lower the Tier 1 capital benchmark from 14% to 13%, per alixpartners.com. On large balance sheets, a 1% reduction in required risk-weighted assets is meaningful and may accelerate bank re-entry into mid-market lending, incrementally increasing competition for private credit lenders in that segment through 2027.
Implications for Institutional Investors and Operators
What This Means for Borrowers
Operators and PE-backed borrowers approaching the credit markets today face a bifurcated reality. Higher-quality credits (those with strong FCCR (generally above 1.5x), conservative leverage, and sector tailwinds) retain access to capital at competitive terms. However, the era of borrower-friendly documentation and PIK flexibility is fading. Borrowers who deferred refinancing decisions expecting rate cuts should reassess: with SOFR stable around 3.6% and rate cuts pushed further out, the window of relative optionality is narrowing. For 2019–2022 vintage deals with flat operating performance, proactive capital stack renegotiation may be preferable to waiting for maturity pressure to force the issue, especially as sikich.com notes that maturity pressure is increasingly concentrated among weaker, lower-rated credits with limited near-term relief options.
What This Means for Lenders and Investors
For institutional investors and private credit allocators, the current reset offers a rare combination: spreads that are 50–100 basis points wider than six months ago, alongside improving credit structures (more covenants, less PIK, better documentation). First-lien all-in yields in the 8.0%–8.5% range remain in the upper half of the 12-year historical range, per morganstanley.com. However, not all private credit exposure is equal. Portfolio differentiation will accelerate: managers with 2021–2022 vintage concentration, software exposure, and aggressive original underwriting will see non-accruals rise. Manager selection, vintage diversification, and rigorous sector underwriting are critical filters.
Redemption Risk and Liquidity Management
The redemption pressure emerging at flagship funds, with investors seeking to redeem 10% of Blackstone Private Credit Fund shares and 17% of Cliffwater’s $31.3 billion fund, per marketscreener.com, is an important systemic signal. Funds facing redemption pressure may preserve cash rather than deploy into new loans, creating a secondary effect of reduced origination capacity precisely when deal flow is most critical. Investors in semi-liquid vehicles should model liquidity scenarios carefully against their own redemption timelines.
Forward Look: Selective Deployment in a Structurally Improving Market
The next three to six months are likely to be defined by continued bifurcation rather than a broad market correction. A recovering M&A pipeline (if PE sponsors and acquirers can bridge valuation gaps) combined with a substantial refinancing wave creates an opportunity set for lenders with dry powder and disciplined origination capacity. Industry consolidation is accelerating this dynamic: scaled platforms with deep sponsor relationships and diversified origination are increasingly setting terms, while smaller managers face pressure on both the fundraising and deployment fronts.
Retail capital flows remain a watch item. With private wealth flows in tracked retail alternatives falling 17% month-on-month in May and private credit flows down 35% in that month alone, and Q2-to-date flows down 70% from the Q1 average, per marketscreener.com, the retail bid that inflated AUM and compressed spreads during the boom phase is structurally retrenching. That is a headwind for asset growth and fee income at manager level, but a tailwind for institutional lenders deploying new capital at better terms with less competition from yield-hungry retail flows.
Bottom line: the credit cycle has turned in a lender-friendly direction. The opportunity is real, but it is selective. Disciplined underwriting, sector avoidance of over-levered software, and a focus on credit quality over volume is the appropriate posture for the balance of 2026.
Key Market Insights
- Volume correction is real and sharp: Private credit issuance fell approximately 40% in the three months through May 2026, signaling the end of boom-era origination pace and the start of a more selective lending cycle, per marketscreener.com.
- Spreads and structures are improving simultaneously: Spreads are 50–100 bps wider than late-2025 levels while covenants, documentation, and leverage demands are all moving in lenders’ favor, a combination that has historically marked the best vintage entry conditions, per lordabbett.com.
- Software sector stress is a portfolio differentiator: Software loans are down 4.7% YTD vs. a 1.2% gain for the broader leveraged loan index, managers with heavy 2021–2022 software vintage exposure face elevated non-accrual and PIK risk, per marketscreener.com.
- Higher-for-longer rates are the critical FCCR threat: With SOFR at approximately 3.6% and rate cuts delayed, unhedged floating-rate borrowers from 2019–2022 vintage deals face compressing interest coverage, a key underwriting variable lenders are now scrutinizing more aggressively, per alixpartners.com.
- Retail flow reversal is structurally significant: Private credit retail flows in Q2 are down 70% from Q1 averages: reducing the yield-hungry capital that compressed spreads during the boom, and rebalancing the market toward institutional lenders with structural advantages in selectivity and underwriting, per marketscreener.com.


