
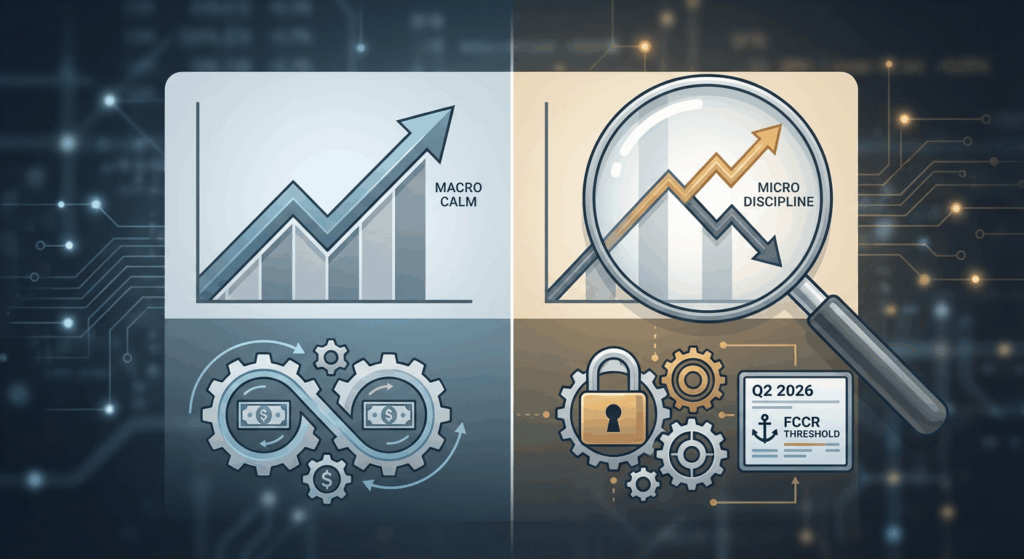
The Macro Signal: A Credit Market Running Two Stories at Once
Entering Q2 2026, the private credit complex is telling two stories simultaneously, and institutional participants must read both carefully. On the surface, credit markets remain functionally open, spreads are trading near cyclical tights, and deal activity is accelerating off a strong year-end 2025. Beneath that, a quieter repricing is underway: underwriting discipline is tightening around cyclical exposures, tariff-sensitive industries, and software credits with deteriorating cash flows, while liquidity mismatches inside semi-liquid wealth-channel vehicles are drawing increasing regulatory and investor scrutiny.
According to kkr.com, credit markets entered 2026 in better shape than many anticipated: defaults remained contained in aggregate, income compounded steadily, and markets stayed open through persistent macro uncertainty. Yet KKR’s own credit team flags that defaults are expected to rise from historically low levels, and dispersion between stronger and weaker borrowers is widening. The macro calm, in other words, is masking a micro sorting event.
This dispersion dynamic is being amplified by the Federal Reserve’s rate posture. Three 25-basis-point cuts in September, October, and December 2025 compressed all-in yields even as base spreads held, creating a subtler but real erosion in lender returns. For operators and borrowers, this is a window. For lenders and investors, it is a moment requiring heightened underwriting precision.
Quantitative Market Snapshot
The following data box captures key market metrics as of Q1 2026, benchmarked against prior-period readings:
| Metric | Current (Q4 2025 / Q1 2026) | Prior Period (Q3 2025) | Direction | Source |
|---|---|---|---|---|
| Middle Market Credit Spreads (band range) | Unchanged QoQ; low-to-mid band pricing dominant | Same band range held | → Flat (competitive pressure) | valuationresearch.com |
| Original Issue Discount (OID), Middle Market | ~98.75–99.25 (issuance price) | ~98.50–99.00 | ↑ Tightening (borrower-favorable) | valuationresearch.com |
| U.S. Leveraged Loan New-Issue Volume (Full Year 2025) | $709.0 billion | $661.2 billion (FY 2024) | ↑ +7.2% YoY (second-highest since 2021) | kpmg.us |
| Refinancing Share of Total Leveraged Loan Volume | 44% of total volume | Higher share in prior years | ↓ Declining; new-money LBO/M&A gaining share | kpmg.us |
| Global Private Credit AUM (U.S. estimate) | ~$1.34 trillion (U.S.); ~$2.5 trillion (global, BIS AUM basis) | ~$2.1 trillion (IMF framing, assets + committed capital) | ↑ Continued expansion; definition-dependent | atlaspeakresearch.com |
| Pricing Grid Step-Downs (e.g., S+475 → S+450) | Increasingly common; leverage-linked step-downs embedded at close | Less prevalent in 2024 vintages | ↑ Structural feature becoming standard | valuationresearch.com |
Sources: Valuation Research Corporation (VRC), KPMG Corporate Finance, Atlas Peak Research, KKR. Data as of Q4 2025 – Q1 2026.
Sector Analysis: Where Lender Appetite Is Expanding, and Contracting
Technology & Software (Cautionary Yellow): Software credits that entered the private credit boom on elevated ARR multiples are now facing a meaningful reassessment. Per atlaspeakresearch.com, software is identified as a specific pressure point in Q1 2026’s liquidity and underwriting repricing, with cash flow stress emerging in cohorts underwritten on growth assumptions that have since moderated. Lenders are revisiting fixed charge coverage ratio (FCCR) minimums for software credits, with new floors increasingly demanded at 1.15x–1.25x for unitranche structures where previously 1.0x was tolerated. AI-adjacent infrastructure plays remain an exception, attracting notable sponsor and lender interest.
Cyclical & Tariff-Exposed Industrials (Restricted): valuationresearch.com explicitly flags that the upper end of middle market spread bands is now reserved for lower-quality credits (including cyclical and tariff-exposed businesses) and that these names may struggle to access capital at any spread level in the near term. Lenders are requiring enhanced covenant packages, tighter leverage caps (debt/EBITDA held to 4.5x–5.0x versus 5.5x–6.0x in peak 2021–2022 vintages), and step-down pricing grids tied to deleveraging milestones.
Sponsor-Backed M&A & LBO (Active): The long-anticipated M&A rebound is materializing, albeit unevenly. Per kpmg.us, new-money issuance from LBO and M&A activity led the leveraged loan market in 2025, and momentum is expected to accelerate into early 2026. Private equity dry powder remains elevated, and funds holding legacy assets with seven-to-eight-year hold periods are facing mounting exit pressure, creating a pipeline of refinancing and recapitalization opportunities for direct lenders.
Wealth-Channel Private Credit Vehicles (Structural Watch): A structural fault line is emerging within the private credit ecosystem itself. atlaspeakresearch.com details that semi-liquid perpetual BDCs and evergreen interval funds, which hold illiquid middle market loans but offer periodic redemption windows, carry elevated liquidity mismatch risk. Liquid sleeves in these vehicles range from 10%–40% of assets, and synchronized redemption pressure could force asset liquidation at discounts. Classic closed-end direct lending funds, by contrast, carry low run risk given structural capital lock-up matching loan duration.
Implications for Institutional Investors and Business Operators
For Borrowers and Operators
The current environment represents a selective but genuine window of opportunity for high-quality borrowers. OID tightening, spread stability, and increased use of leverage-linked pricing grids mean that well-positioned sponsors and operators (particularly those with clean FCCR profiles above 1.20x, manageable debt/EBITDA at or below 5.0x, and limited tariff exposure) can access capital at competitive all-in costs. However, operators should not mistake lender competition for lender indifference: covenants are tightening in cyclical sectors, and documentation quality is under renewed scrutiny. The window may narrow if macro conditions deteriorate or if the Fed pivots more slowly than expected.
For Lenders and Institutional Investors
The spread-near-historic-tights environment demands more rigorous underwriting discipline, not less. As kkr.com notes, dispersion between stronger and weaker borrowers is widening, meaning portfolio-level default statistics are increasingly misleading as a signal of individual credit health. Investors in closed-end direct lending funds remain better insulated from redemption-driven liquidity events than those allocated to semi-liquid vehicles. Vintage selection matters acutely: 2026 vintages underwritten with current spread discipline and realistic growth assumptions may outperform 2021–2022 cohorts on a risk-adjusted basis.
Forward-Looking View: The Next 3–6 Months
The 2028 refinancing wall, heavily concentrated in B-rated and below borrowers, per kpmg.us, is emerging as the medium-term structural risk most likely to drive spread volatility. Near-term, the constructive backdrop for higher-quality credits is expected to persist, supported by Fed accommodation and elevated private equity dry powder. The key variables to watch are: (1) the pace and scope of tariff impacts on GDP and corporate margins; (2) Fed policy trajectory under a leadership transition; and (3) whether wealth-channel redemption pressure in semi-liquid vehicles escalates into a systemic liquidity event or remains vehicle-specific. For now, the credit cycle remains in a late-expansion, early-repricing phase, not a full-blown contraction, but the margin for underwriting error is compressing.
Key Market Insights
- Spread stability is deceptive: Middle market credit spreads are flat QoQ, but the composition of who is pricing in the low-to-mid band versus the upper band has shifted sharply, higher-quality credits are winning disproportionately, while weaker names face access constraints.
- OID tightening signals borrower leverage: OIDs moving from ~98.50–99.00 to ~98.75–99.25 is a direct transfer of economic value from lender to borrower, compressing total returns even where headline spreads appear unchanged.
- Pricing grids are the new covenant: Leverage-linked step-down grids (e.g., S+475 → S+450) are increasingly functioning as an underwriting discipline mechanism, aligning lender return expectations with borrower deleveraging performance.
- Software and tariff-exposed credits face a two-tier market: Lender appetite is bifurcating sharply by sector; FCCR floors and leverage caps are being reset higher for stressed industry cohorts, effectively creating a restricted-access tier within the middle market.
- Vehicle structure matters as much as credit selection: The liquidity mismatch risk embedded in semi-liquid wealth-channel vehicles is a systemic watch item for Q2–Q3 2026, institutional allocators should evaluate vehicle type alongside underlying credit quality in portfolio construction.


