
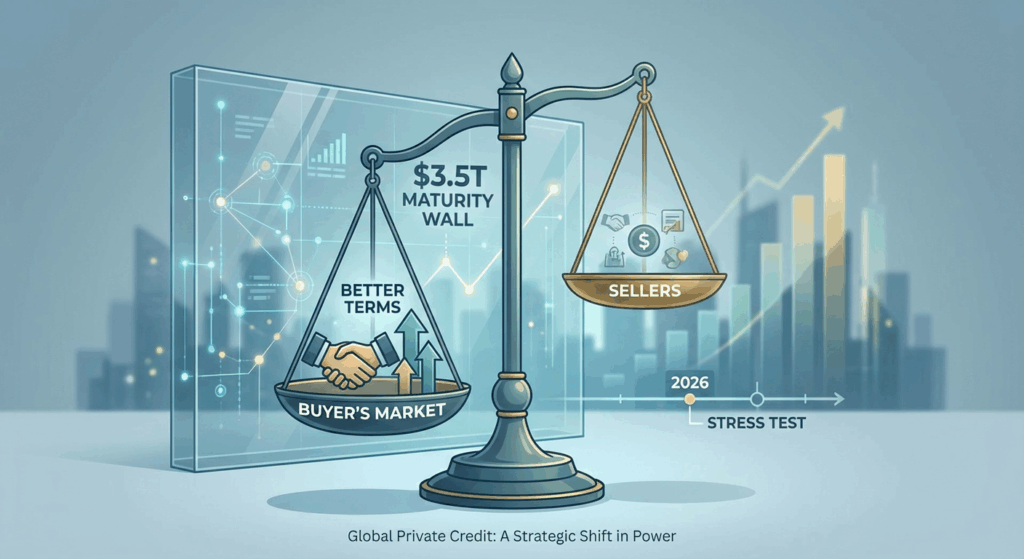
Market Overview: The Great Shift to a Buyer’s Market
As of May 2026, the global private credit market has officially surpassed the $3.5 trillion threshold, marking a definitive transition from a niche alternative asset class to a mainstream systemic force. However, for the first time in over a decade, the market is facing a synchronized stress test. Following a period of aggressive capital deployment, reaching nearly $593 billion in 2024 alone, the industry is grappling with “margin compression” and the emergence of distinct cracks in corporate credit coverage.
The defining narrative of Q2 2026 is the shift from a seller’s market to a buyer’s market. According to recent analysis by Apollo and Private Markets Insights, borrowers are now commanding better terms as competition intensifies between direct lenders and a resurgent syndicated loan market. While deal flow remains robust, underwriting discipline is being tested by a legacy of loose covenants from the 2024-2025 vintage.
Institutional activity highlights a structural evolution: traditional banks have moved from pure competition to strategic partnership. Major institutions have committed upwards of $96 billion to private credit vehicles, signaling that the “bank retreat” narrative has evolved into a “bank convergence” reality.
Quantitative Snapshot: May 2026
The following metrics highlight the current state of liquidity, leverage, and stress in the private credit ecosystem.
| Metric | Current Level / Trend | Comparison / Context | Implication |
|---|---|---|---|
| Global AUM | $3.5 Trillion | Surpassed $3.5T in Q1 2026 | Mainstream asset class status achieved; saturation risks rising. |
| LBO Deal Volume | +40% YoY Growth | Acceleration in late 2025/early 2026 | M&A revival driving deployment, reducing dry powder drag. |
| Distressed Capital | $100 Billion+ Raised | New funds raised over last 24 months | Market preparing for default cycle; “vulture” capital ready to deploy. |
| Margin Outlook | Compressing | Negative outlook from Morningstar DBRS | Intense competition driving down yield spreads for borrowers. |
Sector Analysis: Rotation into Real Assets
Asset-Based Finance (ABF)
The most significant sector rotation in 2026 is the pivot toward Asset-Based Finance (ABF). With corporate direct lending margins squeezing, managers are hunting for yield in complexity. Approximately 65% of managers now identify ABF as having the highest growth potential, with estimates placing the total addressable market at $40 trillion. This includes infrastructure debt, equipment finance, and consumer receivables, offering a counter-cyclical hedge against corporate default risk.
Tech & AI: Caution Emerges
While technology remains a core vertical, lenders are becoming increasingly selective. Concerns regarding an “AI bubble” and late-cycle valuation excesses have led to tighter scrutiny on recurring revenue loans. Lenders are demanding lower attachment points and stricter covenants for software businesses that have not yet demonstrated profitability, diverging from the “growth-at-all-costs” underwriting of previous years.
Investment Grade Private Credit
Despite headlines focusing on distressed assets, the investment-grade (IG) private placement market remains resilient. SLC Management reports that placement volumes remained healthy through Q4 2025 and into 2026, powered by insurance demand. This segment continues to offer a safe harbor for allocators seeking duration without the volatility of public credit spreads.
Implications for Market Participants
For Borrowers
The Window is Open: Borrowers with high-quality EBITDA and reasonable leverage profiles currently face the most favorable financing environment in three years. The “buyer’s market” dynamic means tighter spreads and more flexible documentation are available as funds compete to deploy capital before year-end. However, firms with “story credits” or excessive PIK (Payment-in-Kind) structures will find the market bifurcated and expensive.
For Lenders & Investors
The Great Differentiation: The gap between top-tier managers and average performers is widening. With Intelligence notes that the use of PIK toggles is rising, a classic late-cycle signal of borrower stress. Investors must scrutinize fund vintages from 2023-2025 for embedded portfolio weakness. The easy money has been made; returns in 2026 will come from workout capabilities and sector specialization (specifically ABF and Infrastructure) rather than beta.
Forward Outlook: The Next 6 Months
- Default Cycle Realization: Expect the “shadow default” rate to become explicit. As interest coverage ratios remain strained, the rising use of PIK will convert into actual restructurings, validating the $100B+ raised by distressed funds.
- Europe as a Growth Engine: While the US market saturates, Europe now represents 30% of global AUM. We expect capital to flow disproportionately to European direct lending strategies where bank retrenchment is more acute than in the US.
- M&A Super-Cycle: With PE hold times reaching a median of 3.8 years, pressure to return capital to LPs will drive a sustained surge in deal flow, providing a floor for deployment volumes despite macro headwinds.
- Regulatory Watch: With private credit entering 401(k) plans and retail adjustments, expect heightened regulatory scrutiny on valuation methodologies and liquidity mismatches in semi-liquid funds.


