
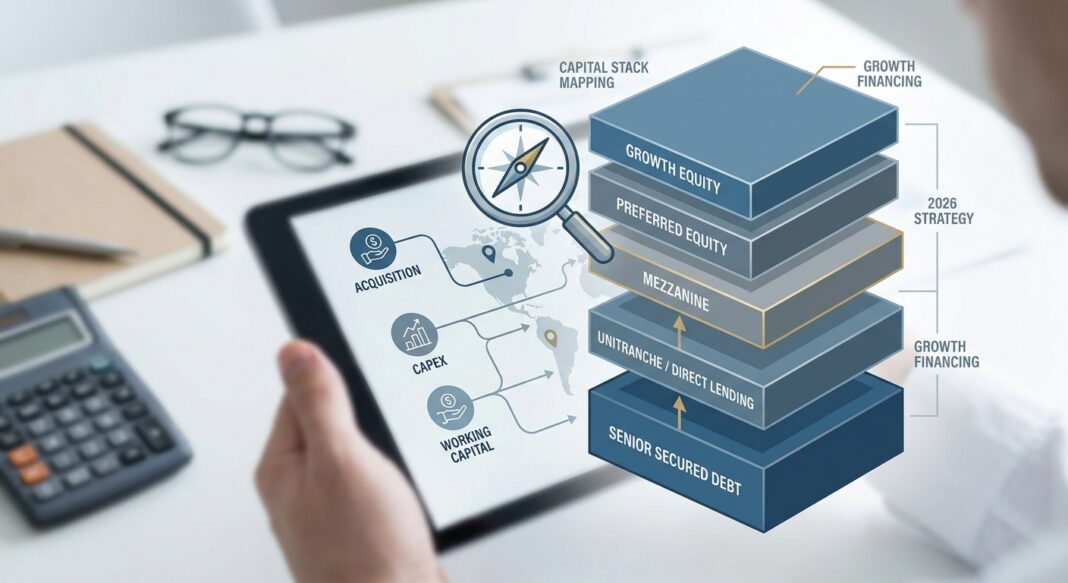
The Growth-Stage Financing Gap: Why the Wrong Capital at the Right Time Can Cost You Everything
You have scaled past the startup phase. Revenue is predictable, EBITDA is real, and the next move (whether an acquisition, a new facility, a geographic expansion, or a partial liquidity event) requires outside capital. This is where the growth-stage financing gap bites hardest.
The challenge is not access. Access to capital remains strong in 2026, but priorities have evolved: business owners are moving beyond a singular focus on cost and instead emphasizing flexibility, timing, and certainty of execution. The challenge is match quality: putting the right layer of capital against the right use-of-proceeds, at a cost the business can absorb without surrendering strategic control or compressing equity returns below the threshold that makes the whole exercise worthwhile.
This article is a practitioner’s guide to exactly that problem. We will map the capital stack from bank revolvers to growth equity, show how use-of-proceeds should drive the structural decision, and walk through the gap capital playbook (quantify, prepare, run the process, negotiate the structure) for a mid-market operator sitting at $5M–$15M EBITDA trying to fund a $25M–$75M strategic initiative.
The Cost-of-Capital Spectrum: Banks Through Equity
Every growth-stage capital decision starts with the same map. Understand where each instrument sits on the cost-and-control spectrum before you decide which layer to pull from.
Layer 1: Bank Senior Secured (Lowest Cost, Highest Restriction)
Traditional bank revolvers and term loans remain the cheapest source of capital for operators with clean balance sheets and predictable cash flows. Banks still provide relationship continuity and low-cost capital for core operations. The trade-off is covenant intensity: a maintenance covenant requires the borrower to meet certain financial metrics on a regular basis, such as quarterly, while an incurrence covenant is only tested if the borrower takes a specific action like attempting to take on more debt. Bank facilities almost always carry the former, meaning a single bad quarter can trigger a technical default even if the business is fundamentally sound. Use bank capital for working capital, revolving liquidity, and capex that generates hard-asset collateral.
Layer 2: Unitranche / Direct Lending (Mid-Cost, Maximum Flexibility)
Unitranche debt combines senior and subordinated debt into a single tranche from one direct lender, typically offering 4x to 6x leverage at blended rates of 8 to 11 percent in the lower middle market. Unitranche dominates the lower middle-market direct lending channel in 2026. The pricing benchmark for a $10M EBITDA target: SOFR plus 500 to 650 basis points is the working 2026 pricing band for unitranche, per Lincoln International's Q1 2026 Senior Debt Facility. Critically, if unitranche financing can close 30 to 45 days faster than a syndicated alternative, sponsors often justify 50 to 100 basis points of extra spread by avoiding financing gaps, broken syndications, or delayed closings that jeopardize purchase agreements. Use unitranche for acquisitions, platform-build financing, and growth initiatives with a clear 3–5 year payback tied to EBITDA expansion.
Layer 3: Mezzanine (Higher Cost, Equity-Like Features)
Mezzanine debt is a hybrid form of capital that combines features of both debt and equity financing; it fills the gap between the amount a traditional bank will lend and the firm's existing equity base. The 2026 cost structure: 8–12% cash interest plus 2–4% PIK (paid-in-kind, accruing to principal) plus warrants or equity co-investment of 1–5%, creating a 16–22% all-in IRR for the lender. In 2025–2026, mezzanine funds have seen renewed interest as investors seek strategies with built-in cash yields in a higher-rate environment. Use mezzanine when senior leverage is maxed out, equity dilution is unacceptable, and the business generates the free cash flow to carry the additional fixed charge.
Layer 4: Preferred Equity (Highest Cost Before Common, Minimal Cash Burden)
Preferred equity sits between mezzanine and common stock. It carries a negotiated dividend (often PIK-able), a liquidation preference, and in many cases participation rights on exit proceeds. Participating preferred reappeared in 31 percent of Q2 2026 growth-round term sheets, up from 14 percent in Q2 2024, according to the Cooley GO Venture Financing Report. A founder taking a 5.0x revenue mark with a 1.5x participating preference and an 8% cumulative dividend is accepting roughly 5 to 7 percentage points of additional dilution at a three-year exit versus a clean 1.0x non-participating sheet at the same headline price. Use preferred equity when cash flow cannot service additional debt and the business needs runway capital tied to a specific strategic outcome.
Layer 5: Growth Equity (Highest Dilution, No Fixed Charge)
Growth equity is the most expensive capital by dilution cost, but it carries no mandatory cash obligation, giving operators maximum flexibility in a downturn. Lower middle-market growth rounds in the United States closed at a median 4.8x trailing revenue in Q2 2026, against 6.2x in Q2 2025 and 8.4x at the 2021 peak, per PitchBook US Venture Deal Terms. Deploy growth equity only when the use-of-proceeds is pre-revenue, pre-EBITDA, or so transformational that no rational debt structure can underwrite it.
Use-of-Proceeds Mapping: What the Money Does Determines What the Money Should Cost
The single most common structuring error made by growth-stage operators is pulling the wrong instrument for the use-of-proceeds. Here is the practitioner's mapping:
| Use of Proceeds | Optimal Layer | Why It Fits | Red Flags |
|---|---|---|---|
| Working Capital / Revolver | Bank Senior / ABL | Self-liquidating; collateral-backed | Using term debt for cyclical needs |
| Acquisition (Platform or Add-on) | Unitranche / Direct Lending | Speed, certainty, single lender | Over-levering at close; weak QoE |
| Growth Capex / Expansion | Senior + Mezz Split | Hard asset collateral + PIK flexibility | Mismatching short debt to long payback |
| Partial Owner Liquidity / Recap | Preferred Equity or Mezz | Separates liquidity from full exit | Over-diluting on terms; warrants at low strike |
| Pre-Revenue / R&D / Market Entry | Growth Equity | No cash service on non-cash activities | Venture debt without revenue visibility |
Many organizations are now exploring more sophisticated capital structures (layering traditional bank financing with private capital, asset-based solutions, and capital markets activity) which allows for greater optionality, particularly in an environment where economic conditions can change quickly. The operators winning at capital strategy in 2026 are not picking one instrument; they are building a stack where each layer is optimized for its specific purpose.
Worked Example: The $75M Growth Stack for a $12M EBITDA Services Business
Consider a regional business services company with $60M revenue, $12M EBITDA, and a clear acquisition pipeline of two add-on targets totaling $75M in combined enterprise value. The owner wants to execute both acquisitions within 18 months without selling a controlling stake. Here is how the capital stack should be structured:
Senior Secured Unitranche: $48M
- Leverage: 4.0x EBITDA (within the standard 4–6x EBITDA range for LMM unitranche in 2026)
- Pricing: SOFR + 575 bps (within the SOFR + 500–650 bps 2026 pricing band)
- Maturity: 5 years; 1% annual amortization
- Covenants: Single maintenance covenant, maximum net leverage of 5.0x tested quarterly. Middle-market direct loans often still include at least one maintenance covenant, such as a leverage ratio, reflecting the tighter documentation in bilateral or club deals.
- Security: First lien on all assets, plus pledge of subsidiary equity
Mezzanine Tranche: $18M
- Cash Interest: 9% per annum, paid quarterly
- PIK: 3% per annum, accrued to principal (when borrowers elect PIK interest, the outstanding balance compounds, increasing total debt burden, model this carefully)
- Equity Kicker: Warrants representing 2.5% of fully diluted common equity, struck at current FMV. Every warrant granted to a mezzanine lender dilutes existing common equity; in a successful exit, the equity kicker reduces the return available to the sponsor and management team, a cost that must be weighed against the benefit of reduced upfront equity contribution.
- Maturity: 6 years (one year back of senior)
- All-In IRR to Lender: Approximately 18–20%, within the 2026 all-in mezzanine cost range of 10–14% cash coupon plus PIK plus warrants
Owner Equity Rollover / Co-Investment: $9M
The owner rolls $9M of existing equity into the new holding structure, retaining majority economic ownership and all governance control. Total capital deployed: $75M. Blended cost of debt capital: approximately 11.5% all-in. No equity dilution beyond the 2.5% warrant strip on the mezzanine.
This structure is optimal because: the business has predictable FCF to service the cash interest, the PIK feature provides a buffer if Year 1 integration is choppy, and the warrant coverage is small enough that the owner retains meaningful upside at a 6x EBITDA exit.
The Gap Capital Playbook: Quantify → Prepare → Run the Process → Negotiate
Step 1: Quantify the Gap
The gap is the difference between what your existing lenders will provide and what the strategic initiative requires. Build it from the bottom up: (a) total initiative cost; (b) maximum senior leverage your lender base will extend; (c) available equity without triggering a control change; (d) the residual is the gap. For a $75M acquisition using the example above: $75M cost − $48M senior − $9M equity = $18M gap. That is your mezzanine need, sized before you ever open a conversation with a lender.
Step 2: Prepare the Materials Package
Lenders are underwriting your ability to service the debt, not your vision. A 2026 unitranche lender package typically includes three years of audited financials plus TTM interim, a quality-of-earnings report from a top-15 accounting firm, a management presentation, five-year projections, a working capital analysis, a capex build, and key customer and supplier lists. For mezzanine, add a clear equity kicker framework: the strike price methodology, the cap table as-adjusted, and a detailed warrant dilution waterfall. Lenders will not negotiate warrant economics blind.
The QoE is the single most heavily scrutinized document; lenders will not accept management-prepared EBITDA and typically require a QoE from Grant Thornton, RSM, BDO, EisnerAmper, or a similar Tier 2 firm at minimum. Commission it early. Deals that break in diligence almost always break on normalized EBITDA, not structure.
Step 3: Run a Structured Process
Ares Capital, Blue Owl Capital, Antares Capital, Twin Brook Capital Partners, Apollo Global Management direct lending, Carlyle Direct Lending, KKR Capital Markets, Golub Capital, and Monroe Capital lead the unitranche market for $25M–$200M EV deals. For mezzanine, top providers include middle-market BDCs such as Ares and Owl Rock, specialty mezzanine funds including Audax Mezzanine and NewSpring, and family offices doing direct deals. Run a minimum of three to five competing term sheets across the senior and mezzanine layers simultaneously. The borrower trades a modestly higher all-in cost for deal certainty, faster execution, and fewer counterparties to manage, but you only know what "modestly higher" means if you have a competitive reference point.
S&P LCD's middle-market print shows unitranche pricing tightening by 100 basis points in the twelve months to June 2026, which means the first term sheet you receive is not the floor. Push it.
Step 4: Negotiate the Structure
Three terms drive the economics more than the headline rate:
- Covenant headroom: The calibration of incurrence tests is a key underwriting decision. Unlike maintenance covenants, which may not be tested for months, incurrence tests assess risk at the moment a potentially credit-negative action is proposed. Negotiate 25–30% of headroom above your base-case leverage at close, enough buffer to absorb one integration quarter without triggering a waiver process.
- PIK toggle vs. mandatory PIK: A PIK toggle, where the borrower elects to PIK interest when cash is constrained, is materially better than a structure that mandates PIK accrual. In the toggle context, include notice timing, conditions precedent to cash-pay resumption, and any step-up margin for PIK periods. Get the step-up margin to no more than 50 basis points.
- Warrant strike and coverage: The valuation at which equity kickers convert is a critical aspect; it can be set at the time of the loan or determined by a future valuation event. Always negotiate current FMV strike with a hard cap on coverage (no more than 3–5% dilution). A lender asking for 10%+ warrant coverage on a performing business is pricing in equity risk they should not be bearing at a debt cost.
Current Market Context: Five Data Points Every Operator Should Know
- Private credit scale: Global private credit assets under management reached approximately $2.1 trillion in 2025, up from $1.5 trillion a year earlier. Competition among lenders is structurally compressing spreads in your favor.
- Unitranche pricing: Senior secured growth debt for revenue-bearing lower middle-market companies repriced from SOFR plus 750–850 basis points in Q2 2025 down to SOFR plus 600–700 in Q2 2026.
- Mezz cost in 2026: The all-in 2026 mezzanine cost is 10–14%, comprised of an 8–11% cash coupon plus 2–4% PIK plus warrants.
- Covenant trends: Covenant-lite institutional leveraged loans represented 91.7% of large corporate new-issue institutional loans in the United States in 2024, according to PitchBook LCD. But most syndicated leveraged loans today are covenant-lite, though private credit deals typically retain maintenance covenants for earlier lender intervention. Know which structure you are in before you sign.
- Capital stack sophistication: Private capital is now a core part of middle market financial planning, 81% of respondents in KeyBank's April 2026 Middle Market Snapshot Survey consider private capital at least sometimes when evaluating growth or strategic initiatives, while 32% consider it often or every time.
Key Takeaways
- Match capital to use-of-proceeds first, cost second. The cheapest instrument for the wrong use-of-proceeds is the most expensive mistake you can make in a capital structure.
- Unitranche is the workhorse for $25M–$200M acquisitions. It closes faster, requires fewer counterparties, and at current pricing (SOFR + 500–650 bps) is no longer a dramatic premium to split-structure alternatives.
- Mezzanine earns its place when senior leverage is exhausted. The 2026 all-in cost of 16–22% IRR to lenders sounds expensive; it is. But it is cheaper than growth equity dilution at 4–5x revenue multiples, and it preserves control.
- PIK compounds quietly. Model every PIK scenario at 6, 12, and 24 months of election. A 3% PIK on a $18M mezz tranche accretes to $19.9M in two years before you've paid a cent of principal. Factor that into your exit arithmetic before you sign.
- Covenants are the structure that matters after the term sheet. Maintenance covenant headroom, EBITDA add-back definitions, equity cure rights, and springing covenants on revolvers are the four provisions that will determine whether a bad quarter becomes a managed event or a lender-controlled crisis. Negotiate them with the same intensity as the spread.


