
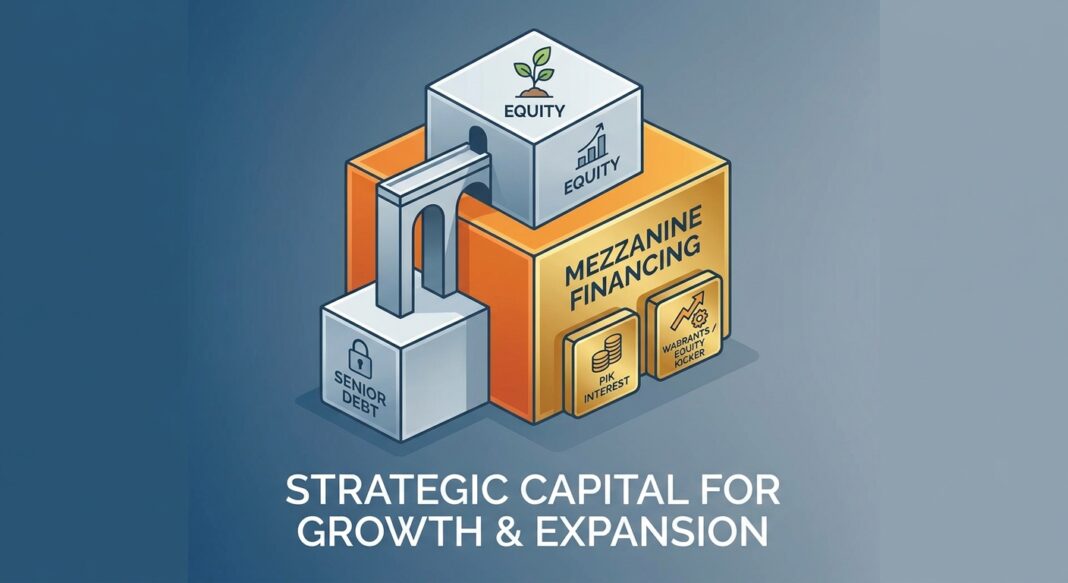
The Growth-Stage Financing Gap: Too Big for the Bank, Too Early for Full Equity
Picture a $35M revenue business-services company operating at 22% EBITDA margins. The founder is not ready to sell, but the business needs $18M to fund two bolt-on acquisitions, accelerate a sales hire-up, and refinance a maturing revolver, all within a 90-day window. The company’s bank will extend a senior revolver up to 3.0x EBITDA. That covers $8M. The remaining $10M sits in what practitioners call the Gap: the capital zone between what senior lenders will underwrite and what the equity structure can absorb without triggering a control-dilution event the founder is unwilling to accept.
This gap is not unusual. Senior lenders have limits on how much risk they will accept, and PE sponsors or founder-operators have limits on how much equity they want to contribute, the instruments that fill that space are mezzanine debt and preferred equity. The decision of which instrument to deploy, at what cost, and with what equity participation attached is one of the most consequential structural choices a growth-stage operator makes.
This article focuses on mezzanine financing as the primary Gap capital tool for companies in the $10M–$100M enterprise value window: a stage where senior-only structures leave value on the table, unitranche pricing is a blunt instrument, and equity issuance triggers dilution the business has not yet earned. We break down the component structure, map the cost of capital spectrum, walk through a detailed term sheet example, and deliver a practitioner-grade Gap Capital Playbook.
Structure Breakdown: Components, Mechanics, and the Full Cost Picture
Mezzanine debt has three defining structural features that distinguish it from senior debt: its subordinated and unsecured position, its option for Payment-in-Kind (PIK) interest, and its equity kicker, almost always in the form of stock warrants. Understanding each component independently is critical before negotiating any term sheet.
1. The Subordinated Debt Layer
Mezzanine debt is a hybrid form of capital that combines features of both debt financing and equity financing, a funding bridge that fills the gap between the amount a traditional bank will lend and the firm’s existing equity base. In liquidation priority, mezzanine debt is subordinated to senior debt, meaning it is repaid after all senior claims have been satisfied in the event of a default. That subordinated position is the root cause of its higher cost.
2. PIK Interest: The Cash-Preservation Mechanism
PIK stands for payment-in-kind. PIK interest accrues on the principal balance instead of being paid in cash, compounding over the life of the facility and increasing the effective cost of borrowing over time. For operators, this feature is a double-edged tool: it preserves operating cash flow during the growth phase but creates a compounding debt obligation. When borrowers elect PIK interest, the outstanding balance compounds, increasing total debt burden, and if the anticipated liquidity event is delayed, the growing PIK balance creates a larger refinancing burden at bullet maturity, a risk that can become severe in deteriorating markets. Structures routinely split the coupon between cash-pay and PIK components to balance lender yield requirements against borrower cash flow.
3. The Equity Kicker: Warrants and Conversion Rights
An equity kicker is the ownership participation component of a mezzanine structure, typically warrants or conversion rights that allow the lender to participate in the company’s upside. This is what makes mezzanine dilutive despite being structured as debt. Every warrant granted to a mezzanine lender dilutes existing common equity. In a successful exit, the mezzanine lender’s equity kicker reduces the return available to the PE sponsor and management team, a cost that must be weighed against the benefit of reduced upfront equity contribution.
Illustrative Term Sheet: $18M Mezzanine for a $60M EV Business-Services Platform
| Term | Structure |
|---|---|
| Facility Size | $18,000,000 |
| Use of Proceeds | Two bolt-on acquisitions ($12M); working capital & fees ($6M) |
| Instrument Type | Subordinated unsecured term note |
| Maturity | 5 years (bullet) |
| Cash Interest | 9.5% per annum, paid quarterly |
| PIK Interest | 3.0% per annum, accruing to principal (toggleable in Year 1–2) |
| Equity Kicker | Warrants for 3.5% fully diluted common equity; strike at $60M EV |
| All-In IRR (lender) | Approximately 17.5–19.0% |
| OID / Origination Fee | 2.0% upfront |
| Senior Leverage | 3.0x EBITDA (existing bank revolver) |
| Total Leverage | 5.2x EBITDA (pro-forma post-close) |
| Financial Covenant | Maintenance: minimum fixed charge coverage ratio 1.15x; tested quarterly |
| Negative Covenants | Restricted payments; additional indebtedness cap; M&A consent above $5M |
| Intercreditor Agreement | Standstill: mezz lender agrees to 180-day payment blockage on senior default |
| Call Protection | No-call Year 1–2; 103 in Year 3; 101 in Year 4; par thereafter |
Current market cost structures for mezzanine in this size range run approximately 8–12% cash interest plus 2–4% PIK (accruing to principal) plus warrants or equity co-investment representing 1–5% equity, creating a 16–22% all-in IRR for the lender. The borrower’s effective blended cost is therefore materially higher than the stated coupon, a point that term sheets frequently obscure.
Mezzanine vs. Alternatives: Mapping the Cost of Capital Spectrum
No financing decision exists in isolation. For a growth-stage operator facing a $10M–$25M gap, four realistic options sit on the cost of capital spectrum:
1. Senior Bank / ABL Extension
All-in Cost: Prime + 2–4% (currently ~10–12% range for leveraged credits)
Advantage: Lowest direct cost; preserves equity.
Constraint: Banks typically cap leverage at 2.5–3.5x EBITDA. For cash flow businesses without hard asset collateral, the ceiling is structural, not negotiated. Below $25M EV, SBA 7(a) and traditional senior bank loans dominate because unitranche minimum check sizes ($15–25M typical) don’t pencil.
2. Unitranche (Direct Lending)
All-in Cost: SOFR + 450–475 bps (approximately 9.5–10.5% current)
Advantage: Unitranche debt consolidates different layers of debt into one facility, providing simplicity and efficiency compared to traditional financing involving multiple lenders and debt tranches. Speed to close is 45–90 days.
Constraint: It prices above a plain senior loan because it is carrying junior risk inside the same wrapper. What the borrower buys is not a lower coupon but a simpler, faster, more certain deal, and they pay a premium in spread for it. For sub-$25M gap needs, the unitranche minimum ticket makes it an overbuilt solution.
3. Mezzanine Financing
All-in Cost: 16–22% IRR to lender (cash + PIK + equity kicker)
Advantage: Mezzanine is a flexible tool when you need capital for growth but want to minimize giving up ownership while offering a favorable rate of return to the lender. The PIK toggle preserves near-term cash flow.
Constraint: Financing agreements often come with covenants that can restrict the company’s operational and financial flexibility. The true complexity comes from the warrants; these equity kickers can complicate the capital structure, add layers to future financing rounds, and create challenging negotiations in a potential exit scenario.
4. Growth Equity / Preferred Stock
All-in Cost: 20–30%+ IRR expectation; 1.0–2.0x liquidation preference
Advantage: No fixed debt service; aligns investor with exit upside.
Constraint: Most dilutive option. Sponsors use mezzanine to reduce equity contribution because even at 15–20% yields, mezzanine is cheaper than the 20%+ returns expected on equity. Preferred stock with liquidation preferences and anti-dilution provisions can materially affect common equity values in modest exit scenarios.
When Mezzanine Wins: When senior debt capacity is exhausted, the company does not want to raise equity at current market multiples, and the business has stable recurring cash flows that can service the interest payments. Mezzanine also remains relevant where the borrower wants to minimize total cost by maximizing cheap senior debt separately, or where deals involve portfolio company add-on financings where existing credit agreements restrict additional senior debt.
Current Market Terms: What the Data Shows in 2026
The mezzanine and direct lending market has shifted meaningfully over the past 18 months. Operators entering the process in H2 2026 are navigating a lender-friendlier environment than existed at the 2024 peak of credit competition.
- Private Credit AUM & Deployment: Global private credit assets under management reached approximately $2.1 trillion in 2025, up from $1.5 trillion the year before, and private credit AUM crossed $1.7 trillion in H1 2026, with roughly 40% of new deployment targeting the lower middle-market growth segment, per PitchBook’s H1 2026 Private Credit Report.
- Spread Widening, A Lender-Friendly Reset: Spreads have widened by roughly 50 to 100 basis points since late 2025, while defensive terms have also improved, according to PitchBook. For borrowers, this means the all-in cost of new mezzanine facilities is modestly higher than 2024 vintage pricing, and covenant packages are tighter.
- Mezzanine Cash + PIK Pricing: The cost structure for mezzanine in 2026 runs 8–12% cash interest plus 2–4% PIK (paid-in-kind, accruing to principal) plus warrants or equity co-investment of 1–5% equity, creating a 16–22% all-in IRR.
- Covenant Structures, Maintenance vs. Incurrence: In private credit, covenants serve as functional risk management tools. Maintenance covenants provide early warning signals; incurrence covenants prevent actions that increase lender risk. Covenant use shifts with borrower size, maintenance covenants are more prevalent with smaller borrowers, while incurrence covenants are the primary guardrails as companies grow. For mezzanine borrowers, negotiating the financial maintenance covenant level (FCCR floor, leverage ceiling) is a primary value driver.
- Renewed Mezzanine Demand: In 2025–2026, mezzanine funds have seen renewed interest as investors seek strategies with built-in cash yields in a higher-rate environment. Simultaneously, all finance providers have noted the growing prevalence of junior debt capital, payment-in-kind structures, and bespoke financing solutions across the mid-market ecosystem.
- Recapitalization Trend: With exits uneven, sponsors increasingly used dividend recapitalizations and continuation vehicles to return capital while holding strong assets. Competitive private credit markets and lower spreads made recapitalizations particularly attractive in 2025, a trend set to continue into 2026.
The Gap Capital Playbook: Quantify, Prepare, Run, and Negotiate
A mezzanine raise is not a bank loan application. It is a structured capital markets process that rewards preparation and penalizes ambiguity. Below is the four-phase playbook.
Phase 1: Quantify the Gap
Before approaching any lender, the operator must produce a Capital Needs Analysis that maps use-of-proceeds to source-of-repayment. This document answers four questions: (1) What is the precise capital need, including fees and contingency? (2) What does the senior lender provide at current leverage ratios? (3) What is the residual gap? (4) What cash flow is available to service both senior and mezzanine debt simultaneously?
The critical test is Debt Service Coverage. A mezzanine lender evaluating a $18M facility at 9.5% cash pay and 3.0% PIK requires that the business generates sufficient free cash flow to service the quarterly cash coupon without breaching the senior credit facility’s own FCCR maintenance covenant. Model both the cash-pay and PIK scenarios under a downside case, typically a 20–25% EBITDA haircut, before approaching lenders.
Phase 2: Prepare the Materials
A mezzanine lender’s diligence focus differs from a bank’s. Banks underwrite collateral coverage; mezzanine lenders underwrite enterprise value and exit optionality. Your information package should include: (a) a trailing 12-month and 3-year EBITDA bridge with addback analysis; (b) a detailed customer concentration and revenue quality analysis; (c) a capital structure waterfall showing recovery at 5.0x, 6.0x, and 7.0x EBITDA exit multiples; and (d) a warrant dilution schedule illustrating common equity values at each exit scenario. Lenders may request financial statements, the current cap table, financial projections, details on the use of funds, and legal and regulatory compliance information. Having these materials pre-assembled compresses a 60–90 day process by two to three weeks.
Phase 3: Run the Process
Top mezzanine providers include BDCs such as Ares Capital, Blue Owl, Main Street, FS KKR, and Hercules; specialty mezzanine funds such as Audax Mezzanine, Madison Capital, Twin Brook, Babson, and Maranon; and family offices and high-net-worth pooled mezzanine vehicles. Run a competitive process with at least four to six term sheet requests. Competing term sheets are the only reliable mechanism for compressing the equity kicker from 4–5% to 2–3% warrant coverage. The underwriting process runs approximately 60–90 days from term sheet to close.
Phase 4: Negotiate the Structure
The five highest-value negotiation points in a mezzanine term sheet, ranked by economic impact:
- Warrant coverage percentage and strike price. Pushing the strike from a nominal $0.01 to current EV eliminates in-the-money dilution at close. Even a 1% reduction in warrant coverage on a $60M EV company saves $600K in exit proceeds.
- PIK toggle optionality. Negotiate the right to toggle between cash-pay and PIK rather than a mandated split. This preserves flexibility if EBITDA growth exceeds projections.
- Call protection schedule. The standard no-call period is 18–24 months. Push for 12 months with a 103/101 step-down. If the business refinances at a lower rate in Year 2, the difference in call premiums can exceed the origination fee savings.
- Financial covenant headroom. Request 25–30% headroom above the maintenance covenant level based on the downside EBITDA case. A FCCR set at 1.05x on a 1.20x trailing actual leaves almost no room for seasonal variance.
- Permitted basket sizes. The negative covenant restricting additional indebtedness and M&A above a threshold will constrain add-on activity. Negotiate a carve-out for acquisitions below 0.5x EBITDA to preserve the roll-up strategy the mezzanine is partly funding.
Key Takeaways
- The stated coupon is not the real cost. A mezzanine facility typically includes cash interest, PIK interest that compounds on the principal, an equity kicker in the form of warrants or conversion rights, and upfront origination fees, and the combination makes the all-in cost of capital higher than the stated interest rate. Always model the full IRR to the lender before signing a term sheet.
- Mezzanine fills a specific structural gap. It is optimal when senior debt capacity is exhausted, equity dilution is too costly at current valuations, and the business has recurring cash flows that can support a quarterly cash coupon. Outside of that window, a unitranche or preferred equity structure may be more efficient.
- PIK compounds, stress-test the balance. When borrowers elect PIK interest, the outstanding balance compounds, increasing total debt burden. If the anticipated liquidity event is delayed, the growing PIK balance creates a larger refinancing burden at bullet maturity. Model a 12-month delay to exit in every scenario.
- Covenant design matters more than pricing. Restructurings initiated at the covenant-breach stage, before a payment default, produce materially higher recoveries than those triggered by missed payments. For borrowers, covenant headroom is operating flexibility. For lenders, it is early-warning infrastructure. Negotiate both sides seriously.
- The market is in a lender-friendly reset. More transactions to finance, less capital competing aggressively for each transaction, and greater ability to negotiate price and structure define the current supply-demand balance. Borrowers should run competitive processes and not accept first-mover terms in the current environment.


