
Deal Structures & Strategy | Bond Capital
Published: 26 May 2026
The Financing Challenge: When Senior Debt Runs Out and Equity Is Too Expensive
A profitable $20M-revenue B2B software company has identified an acquisition target that will double its ARR overnight. The deal price is $40M, a sensible 6x EBITDA multiple. The company’s senior bank will commit $18M, secured by cash flow and receivables. The sponsor has earmarked $10M of equity. That leaves a $12M gap sitting between the two: too large to ignore, too subordinated for the bank to touch, and too expensive to fill with additional equity dilution.
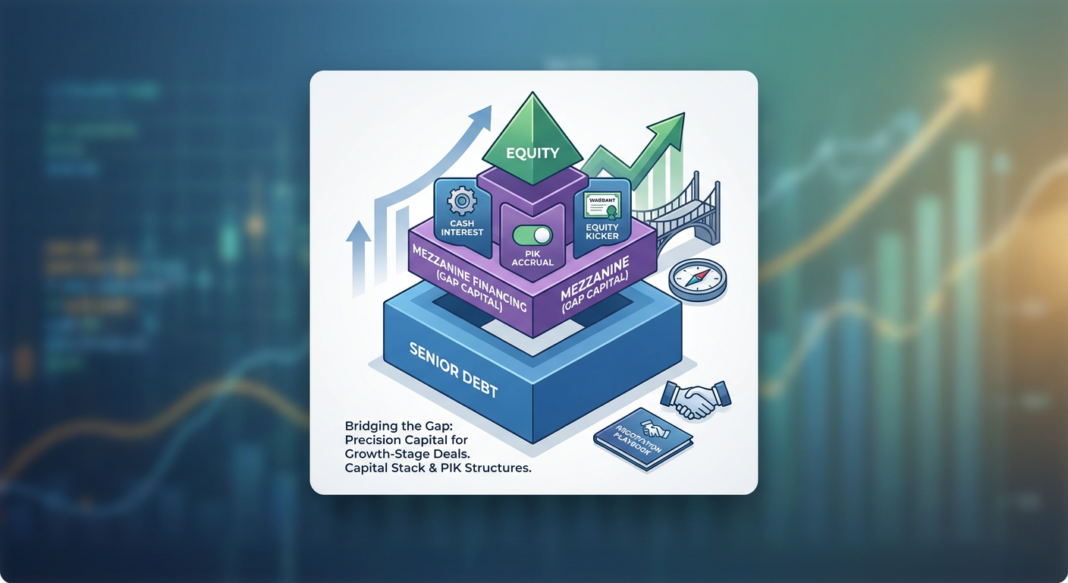
This is the canonical use case for mezzanine financing: a hybrid instrument designed specifically to bridge the structural gap between what senior lenders will provide and what equity investors wish to contribute. It sits junior to senior debt in repayment priority but senior to common equity, occupying a unique risk-return position in the capital stack that is neither pure debt nor pure equity.
In growth-stage acquisition contexts, mezzanine is not a financing instrument of last resort; it is a precision tool. When sized and structured correctly, it enables transactions that would otherwise require excessive equity dilution, keeps management ownership intact, and aligns lender incentives with borrower upside through equity participation features. Understanding its mechanics, true cost, and current market terms is foundational to navigating the capital stack at this stage.
Structure Breakdown: Components, Mechanics & a Live Example
What Mezzanine Is (and Is Not)
Mezzanine debt is a hybrid financing instrument that combines characteristics of both debt and equity. Structurally, it sits junior to senior debt but senior to common equity in a company’s capital stack, creating a distinct risk-return profile. It is almost never secured by hard assets in the same way senior debt is: instead, it relies on subordinated liens, intercreditor agreements, and equity conversion rights as its protective mechanisms.
The three core components that define any mezzanine instrument are:
- Cash Interest: A regular, periodic cash payment, typically 8%–12% per annum, that services the debt like a conventional loan. This component compensates the lender for base credit risk and time value.
- PIK (Payment-in-Kind) Interest: An accrual component, typically 2%–6%, where interest is not paid in cash but instead added to the outstanding principal balance, compounding over time. With PIK, a borrower preserves near-term cash flow at the cost of growing the principal obligation. The structure is often implemented as a “PIK toggle,” allowing the borrower to elect PIK vs. cash-pay on a period-by-period basis, subject to conditions.
- Equity Kicker (Warrants or Conversion Rights): An equity participation feature, typically structured as warrants covering 1%–5% of the borrower’s fully diluted equity, that gives the lender upside exposure if the company grows in value. This feature is what transforms mezzanine from pure subordinated debt into a hybrid instrument, aligning lender and borrower around value creation.
Illustrative Example: $12M Mezzanine for a $40M Software Acquisition
Returning to our growth-stage scenario, the $12M mezzanine tranche might be structured as follows:
| Term Sheet Element | Terms |
|---|---|
| Instrument | Subordinated Mezzanine Note |
| Principal Amount | $12,000,000 |
| Cash Interest Rate | 10.0% per annum (quarterly) |
| PIK Toggle Rate | 3.0% per annum (compounds into principal) |
| All-In Yield (if PIK elected) | ~13.0% |
| Equity Kicker | Warrants for 3.0% of fully diluted equity at a strike price reflecting current FMV |
| Maturity | 6 years (bullet repayment) |
| Amortization | Interest-only; principal due at maturity |
| Call Protection | 2% prepayment premium in years 1–2; 1% in year 3; par thereafter |
| Covenants | Maximum total leverage (6.5x), minimum EBITDA, change-of-control provision |
| Subordination | Second priority lien; intercreditor agreement with senior bank |
The full capital stack at closing looks like this: $18M senior bank debt + $12M mezzanine + $10M equity sponsor contribution = $40M acquisition. The sponsor retains majority equity control, the management team avoids the dilution of a larger equity raise, and the mezzanine lender earns a cash return plus warrant participation.
The PIK toggle is particularly valuable for a post-acquisition integration period, when cash flows may be temporarily compressed by integration costs, system migrations, or customer transitions. Rather than straining the P&L with full cash interest service from day one, the borrower can elect PIK for the first 12–18 months, then shift to cash-pay as normalized EBITDA stabilizes.
How It Compares: Mezzanine vs. Unitranche vs. Growth Equity
Mezzanine does not exist in isolation; it is always evaluated against structural alternatives. The three most relevant comparators in a growth-stage acquisition context are the unitranche, the traditional senior + mezz split, and incremental growth equity.
Mezzanine vs. Unitranche
The unitranche has become the dominant acquisition financing product for the middle market, with the structure now representing a significant share of sponsored transactions in the sub-$500M enterprise value band. A unitranche consolidates senior and subordinated debt into a single credit agreement with a blended rate and one lender, eliminating the intercreditor negotiation that mezzanine requires. For borrowers who prioritize execution speed and documentation simplicity, the unitranche is often the cleaner solution.
However, the trade-off is price. Mezzanine, when layered above senior bank debt, can produce a lower weighted average cost of capital than a unitranche, particularly when equity kickers allow the mezz lender to accept a lower cash coupon in exchange for equity upside. The unitranche absorbs the entire debt stack into one blended rate; the senior + mezz structure allows pricing optimization across two separate instruments.
Critically, mezzanine also retains clear structural subordination: a feature that becomes important for borrowers anticipating future capital events, rating needs, or investors who require visible seniority rankings in the stack. The unitranche obscures that distinction internally through an Agreement Among Lenders (AAL) that is kept confidential from the borrower.
Mezzanine vs. Growth Equity
The fundamental comparison is cost of capital vs. dilution. Mezzanine, despite its higher nominal rate versus senior debt, is categorically less dilutive than equity for founders and operators who expect enterprise value to grow significantly post-acquisition. Mezzanine lenders earn their equity kicker at a fixed warrant strike price; equity investors would capture the full upside of incremental value creation. For a business targeting a 2–3x equity return over a 5-year hold, preserving equity concentration in the hands of operators is a material value decision.
The trade-off sharpens when the business underperforms: mezzanine has fixed obligations (cash interest, bullet principal) that constrain cash flow during distress, whereas equity has no mandatory service requirements. Operators must honestly model downside scenarios before electing mezzanine over equity dilution.
Decision Matrix: When to Use Each
- Use Mezzanine when: You need stretch leverage beyond bank capacity, want to minimize dilution, have strong cash flow visibility post-close, and your senior lender approves the intercreditor structure.
- Use Unitranche when: Speed of execution is paramount, the deal timeline is compressed to 60–90 days, and administrative simplicity outweighs the marginal pricing difference.
- Use Growth Equity when: The business lacks sufficient cash flow to service any debt burden, integration risk is high, or the transaction requires the strategic value-add of an institutional equity partner.
Current Market Terms: What Mezzanine Looks Like in 2025–2026
Mezzanine market conditions have evolved alongside the broader private credit expansion. Here are the key data points and structural standards practitioners should anchor to:
Pricing & Yield
- Mezzanine financing for performing middle-market companies typically yields 12.5%–14% for the lender on a blended cash + PIK basis, reflecting the subordinated position and equity optionality priced into the structure. All-in yields can reach 18%–20% when equity kicker upside is fully realized at exit.
- For context, unitranche facilities currently price at SOFR + 425–475 basis points for upper middle-market sponsored transactions, with core middle-market credits commanding 50–100 basis points higher, producing all-in rates of approximately 11%–14% at current SOFR levels. Mezzanine, as a subordinated layer sitting behind a senior facility, commands additional return for its structural risk position.
- Asset-based lending (ABL) facilities, where applicable, continue to price at 8%–12% depending on collateral quality and borrowing base composition, representing the cheapest rung on the cost of capital ladder.
PIK Toggle Market Standards
- PIK is commonly structured as a toggle rather than mandatory, giving the borrower election rights subject to conditions. A typical structure includes a cash-pay floor (e.g., no more than 50% of total interest may be PIKed) with a 25–50 basis point premium during any PIK election period to compensate the lender for deferred cash receipt.
- Performance-based PIK triggers (requiring a minimum liquidity threshold or maximum leverage ratio before a PIK election is permitted) have become a market-standard protective mechanism for lenders seeking to avoid compounding into deteriorating credits.
Equity Kicker Standards
- Warrants typically cover 1%–5% of fully diluted equity at a strike price reflecting the enterprise value at closing. Some structures use conversion rights (convertible subordinated notes) rather than detachable warrants, particularly where the borrower anticipates a clean exit and wants to avoid the cap table complexity of outstanding warrant instruments.
- Where the mezzanine lender accepts equity kickers in lieu of higher cash-pay rates, the cash coupon can compress by 150–200 basis points, making warrant coverage a genuine cash-flow management tool for borrowers with strong equity value outlook.
Market Context: Mezzanine vs. Unitranche Displacement
- The broad expansion of private credit, with global assets under management reaching approximately $2.1 trillion in 2025, has compressed traditional mezzanine opportunities as unitranche structures absorbed transactions that would previously have required a senior + mezz split. Many traditional mezzanine providers have pivoted toward preferred equity structures sitting behind unitranche debt as a result.
- However, in the lower middle market (sub-$50M enterprise value), where banks remain active senior lenders but unitranche lenders may not compete aggressively, the traditional senior bank + mezzanine fund structure remains highly relevant and cost-effective.
The Gap Capital Playbook: Quantifying, Preparing & Running the Process
Step 1: Quantify the Gap with Precision
Before approaching any mezzanine provider, operators must be able to articulate the gap with deal-level precision. The four inputs that define the gap are: (1) total acquisition consideration, (2) available senior debt capacity (typically a multiple of EBITDA: ask your bank for a term sheet first), (3) equity contribution available and willing, and (4) the residual. That residual is your mezzanine sizing. Over-engineering the gap (by under-stating equity or inflating the purchase price justification) will surface immediately in lender diligence and destroy credibility.
Step 2: Build the Debt Service Model
Mezzanine lenders evaluate historical and projected cash flow, growth potential, and the company’s ability to service both existing senior debt and the new mezzanine layer simultaneously. Expect lenders to stress EBITDA coverage ratios, model free cash flow after senior debt service, and probe add-backs aggressively. The model must demonstrate that, even under a downside scenario, the business generates sufficient cash flow to service cash-pay interest without relying solely on PIK elections.
Step 3: Prepare the Right Materials
Mezzanine is relationship-driven and private; there is no public roadshow. The typical package includes a Confidential Information Memorandum (CIM) or lender presentation covering business model and market position, 3-year audited financials, a detailed LTM EBITDA analysis with normalized add-backs, acquisition rationale and integration plan, a 5-year financial model with base, upside, and downside cases, and management bios. The quality of the EBITDA normalization work, how cleanly the company can defend its add-back schedule, is often the single most important determinant of lender confidence.
Step 4: Run a Targeted, Parallel Process
Unlike syndicated markets, mezzanine is sourced through focused outreach to 5–10 targeted funds. Given the non-dilutive appeal of mezzanine to borrowers, operators often underestimate the importance of running a competitive process. Multiple term sheets create pricing tension and drive down the equity kicker size, both of which matter materially to long-term returns. A debt advisor with existing mezzanine fund relationships can compress the process from 90+ days to 45–60 days in the lower middle market, which matters in time-sensitive acquisition contexts.
Structuring Guidance: Negotiation Points That Move the Needle
For Operators and Borrowers
1. Negotiate the PIK toggle conditions, not just the rate. The rate is visible and easy to compare across term sheets. The PIK conditions (when you can elect PIK, what leverage or liquidity thresholds must be met, and whether the PIK premium steps up or stays flat) are where the real optionality lives. A PIK toggle with loose conditions is worth more to a post-acquisition integration story than a 50-basis-point rate cut.
2. Push back hard on warrant coverage percentage. Warrant coverage is permanently dilutive at the enterprise level. A 5% warrant at a $40M FMV strike price, on a company that exits at $80M, costs the equity holders $2M of incremental lender return that would otherwise accrue to sponsors and management. Negotiate warrant coverage down through competitive tension or offer a higher cash coupon in exchange for reduced equity participation.
3. Understand the interaction between PIK compounding and prepayment premiums. If a company outperforms and seeks to repay the mezzanine early, the prepayment premium calculation must account for capitalized PIK principal, not just the original face amount. Failure to define this cleanly at the term sheet stage is a common source of post-closing disputes when companies perform ahead of plan.
4. Clarify change-of-control provisions in full. Mezzanine instruments typically include change-of-control triggers that accelerate the obligation or allow the lender to put the instrument back to the borrower. In a platform acquisition strategy where the company may itself be acquired within the mezzanine’s tenor, understanding and negotiating these provisions at origination is essential.
For Investors and Capital Allocators
When evaluating a portfolio company’s capital structure that includes mezzanine, verify: (1) the senior intercreditor agreement does not restrict the mezzanine from exercising enforcement remedies in a timely way, (2) the PIK compounding does not create a situation where the mezzanine principal balloons beyond the enterprise’s repayment capacity at maturity (“PIKing into default”), and (3) the equity kicker strike price was set at fair market value at closing to avoid downstream tax and dilution complications.
Key Takeaways
- Mezzanine fills the structural gap between senior debt capacity and total acquisition need; it is a precision instrument for growth-stage operators who want stretch leverage without full equity dilution.
- The true cost is three-dimensional: cash interest (8%–12%), PIK accrual (2%–6%), and equity kicker dilution (1%–5% warrant coverage). Evaluating only the headline rate understates the all-in cost of capital by a meaningful margin.
- PIK toggle mechanics matter more than the toggle rate itself: negotiate the conditions, election windows, and compounding definitions as carefully as the coupon spread.
- Mezzanine vs. unitranche is a cost-vs-speed trade-off: mezzanine can optimize weighted average cost of capital when bank debt is available at competitive rates; unitranche wins on execution certainty and documentation simplicity in compressed timelines.
- Competitive process discipline is non-negotiable: running 5–10 parallel mezzanine fund conversations drives down warrant coverage, tightens pricing, and produces better post-closing relationship dynamics than a single-lender bilateral negotiation.


