
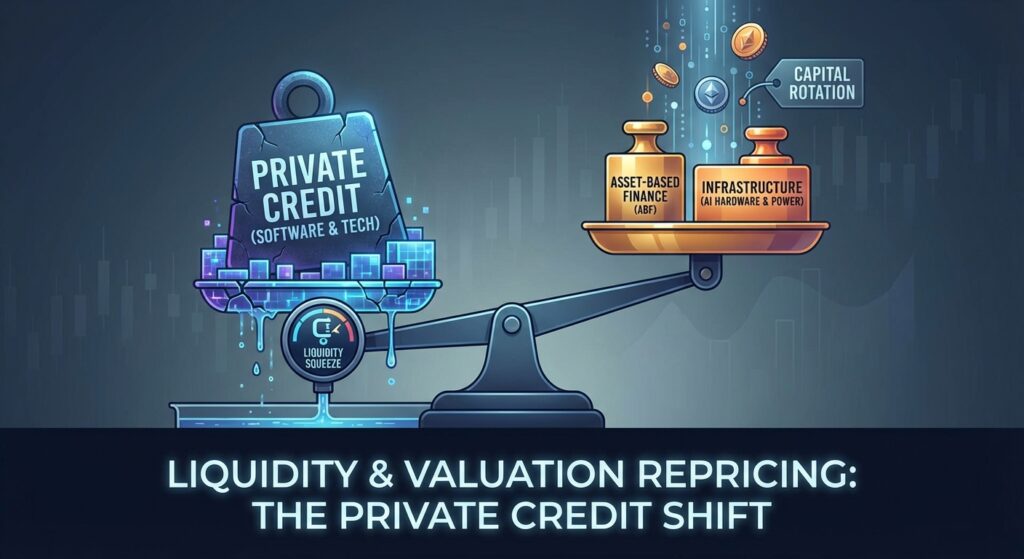
Market Headline: The Liquidity & Valuation Repricing
The private credit market is currently navigating its most significant structural test since the post-COVID expansion. As of mid-March 2026, the primary narrative is not a generalized solvency crisis, but a sharp liquidity and valuation repricing centered on semi-liquid vehicles and the software sector. The catalyst for this shift is JPMorgan Chase’s recent move to mark down the collateral value of private credit loans held on its books. This preemptive tightening of leverage lines, specifically targeting software assets, has restricted borrowing capacity for private credit funds and triggered redemption gates at major semi-liquid issuers.
While institutional closed-end funds (5-8 year lockups) remain largely insulated from run-risk, the “retailization” of private credit is facing a stress test. With listed Business Development Companies (BDCs) trading at significant discounts to Net Asset Value (NAV) and “evergreen” funds hitting withdrawal limits, the market is bifurcating. Capital is rotating out of crowded, high-valuation corporate direct lending strategies and into asset-based finance (ABF) and opportunistic credit, as allocators seek protection from valuation volatility and AI-driven sector disruption.
Quantitative Snapshot: March 2026
The following metrics highlight the current dislocation between asset valuations, liquidity constraints, and sector-specific stress.
| Metric | Current Level / Trend | Prior / Context | Implication |
|---|---|---|---|
| Listed BDC Valuation | ~73% of NAV | Previously ~95-100% (2024-25) | Public markets are pricing in loan markdowns that private NAVs have not yet recognized. Source |
| Software Sector Defaults | ~9.2% | Historical Avg < 2% | “AI disintermediation” fears are driving a re-rating of software credit quality. Source |
| Distressed Capital Raised | >$100 Billion | Last 24 Months | Dry powder is accumulating to target stressed vintages and secondary liquidity solutions. Source |
| Total Market Size | ~$2.1 Trillion | Estimate (Assets + Committed) | Despite liquidity friction, the asset class remains massive, with Europe seeing a fundraising surge. Source |
Sector Analysis: The Great Rotation
Cold: Enterprise Software & Technology
The once “safe haven” of recurring revenue loans is now the primary pressure point. Lenders are grappling with AI disruption risk, where generative AI threatens the moats of legacy SaaS businesses. Atlas Peak Research notes that stress is concentrated in “valuation credibility” within tech portfolios. With default rates in the sector ticking toward 9.2%, lenders are retreating from high loan-to-value (LTV) underwriting based purely on ARR (Annual Recurring Revenue), demanding clearer paths to cash flow.
Hot: Asset-Based Finance (ABF) & Infrastructure
As corporate direct lending faces scrutiny, capital is flowing into Asset-Based Finance (ABF) and specialty finance. PIMCO highlights that these “other lanes” (including real estate, equipment finance, and consumer credit) offer a liquidity premium and diversification away from corporate credit beta. Furthermore, infrastructure debt, particularly tied to Power and AI data centers, remains robust, creating an irony where the hardware of AI is a prime lending target while the software faces skepticism.
Emerging: European Credit
Allocators are diversifying geographically. Following years of US-centric allocation, there is a structural shift toward European direct lending, which is viewed as less saturated and offering slightly more favorable lender protections compared to the highly competitive US middle market.
Implications for Market Participants
For Borrowers
- Cost of Capital: Expect higher all-in yields and tighter documentation, particularly for technology issuers. The leverage multiple arbitrage that fueled software M&A is compressing.
- Structure: Lenders are reducing hold sizes. Borrowers will need to assemble larger clubs of lenders rather than relying on a single mega-tranche from one giant fund.
For Lenders & Investors
- Liquidity Management: The “semi-liquid” evergreen model is broken for the moment. Managers must manage redemption queues and likely halt new withdrawals to preserve portfolio integrity.
- Collateral Discipline: JPMorgan’s move signals that senior lending partners (banks providing leverage to private credit funds) are de-risking. Funds will need to post more equity or un-lever, dragging down IRRs for levered strategies.
- Opportunity: Dislocation creates alpha. Distressed funds and secondary buyers will find attractive entry points as liquidity-constrained investors seek to exit mostly healthy positions at discounts.
Key Market Insights
- The “Run” is Structural, Not Solvency-Based: The current stress is driven by asset-liability mismatches in wealth products, not a wave of bankruptcies across the entire middle market.
- Banks are Back in Control: By marking down collateral, major banks like JPMorgan are effectively tightening financial conditions for the non-bank sector, reasserting their role as systemic gatekeepers.
- Valuation Lag is Closing: Private credit marks have historically been smoothed; the disparity between public BDC trading levels (73% NAV) and reported private valuations is unsustainable and will force write-downs.
- Underwriting Shift: The era of “growth-at-all-costs” lending is over. Underwriting is pivoting back to asset coverage and tangible cash flow debt service.
- Diversification is Key: Portfolios heavily concentrated in US Software direct lending are vulnerable; 2026 vintages will likely favor ABF and diversified specialty finance.


