
Deal Structures & Strategy | Bond Capital
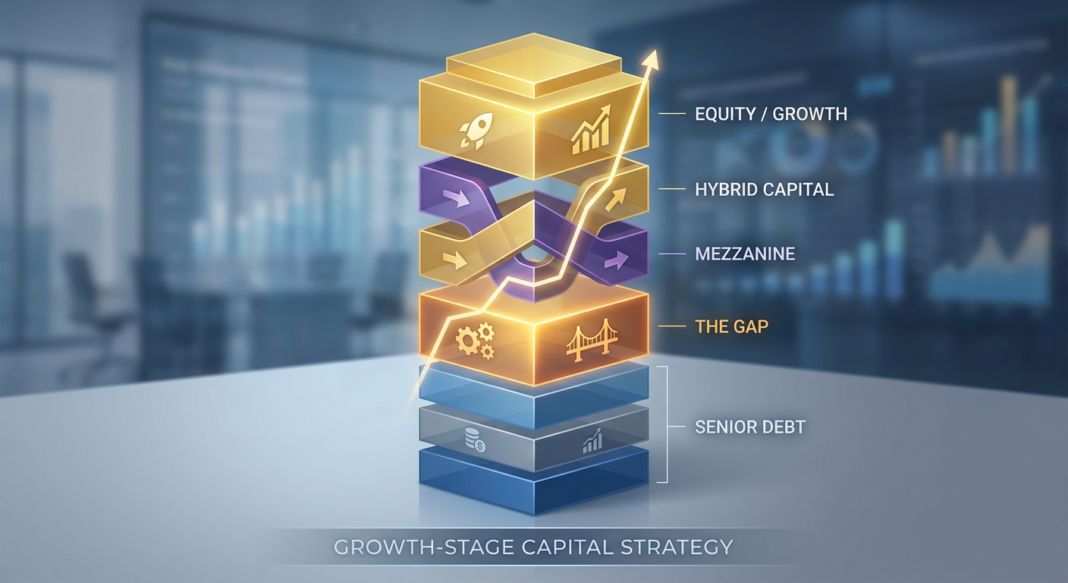
Gap Capital at the Growth Stage: How to Navigate the Capital Stack from Mezzanine to Mezz-Equity Hybrid When Senior Debt Runs Out
May 19, 2026, Bond Capital Editorial Desk
The Growth-Stage Capital Challenge: Where the Gap Lives
A growth-stage business sits in a structurally uncomfortable position. It has moved past the uncertainty of early traction, proven product-market fit, and is now investing aggressively in GTM expansion, add-on acquisitions, or operational scale. Its story is compelling. But its cash-flow profile (often EBITDA-thin relative to revenue, occasionally negative on a free-cash-flow basis) limits what traditional senior lenders will provide. A bank or senior direct lender may cap the facility at 3.0–4.0x EBITDA. The deal economics may require 5.0–6.0x. The company isn’t broken; it simply has a structural financing gap.
This gap is where capital strategy becomes the differentiating lever. Operators and sponsors who understand how to layer the capital stack (mapping each instrument to the right risk tier, use of proceeds, and stage) extract significantly better outcomes than those who approach lenders with a single ask. The tools available are not exotic: mezzanine debt, PIK facilities, preferred equity, hybrid capital, and venture debt all exist precisely to fill this space. The discipline lies in choosing the right instrument for the right gap, at the right cost, with the right structural protections.
This article maps the full cost-of-capital spectrum for growth-stage companies, explains how to quantify the funding gap, and provides the practitioner playbook for structuring, sourcing, and negotiating the right capital solution in today’s market.
Mapping the Cost-of-Capital Spectrum: Banks to Equity
Every financing decision begins with understanding where each instrument sits in the repayment waterfall and what it costs. The capital stack is a hierarchy: senior debt is repaid first and carries the lowest risk for lenders, while equity sits last and absorbs the most risk in exchange for the highest upside. Cost rises as you move down the stack.
Here is the practical spectrum for a growth-stage middle-market company in 2026:
| Layer | Instrument | All-In Cost (2026) | Typical Leverage | Dilution |
|---|---|---|---|---|
| 1st Lien Senior | Bank revolver / term loan | SOFR + 200–350 bps | 2.0–3.5x EBITDA | None |
| Senior / Unitranche | Direct lending (private credit) | SOFR + 425–550 bps (~9–11% all-in) | 4.0–5.5x EBITDA | Minimal (warrants rare) |
| Mezzanine / Junior Debt | Sub-debt, 2nd lien, PIK facility | 12–18% (cash + PIK blend) | 5.0–6.5x EBITDA | Warrants (1–5% equity) |
| Preferred Equity | Hybrid structured preferred | 14–20% (fixed + participation) | N/A (equity layer) | Moderate (senior to common) |
| Common Equity | VC / growth equity / PE | 20–30%+ (IRR expectation) | N/A | High (18–25% per round) |
At the senior / unitranche layer, current market terms reflect a significant shift. Spreads compressed materially in 2025: SOFR spreads on direct lending LBOs with spreads below 550 bps increased to 81% of transactions, according to PitchBook LCD data cited in Capstone Partners’ Q4 2025 leveraged finance report. For upper-middle-market credits, unitranche facilities price at approximately SOFR + 425–475 bps, implying all-in rates in the 9–10% range for top-tier borrowers, with core lower-middle-market credits carrying spreads 50–100 bps higher.
However, the senior layer has limits. A standard unitranche can reach 5.0–6.0x EBITDA in a single facility for strong credits, versus the 3.0–4.0x that a senior-only lender provides. When deal economics require more than the unitranche ceiling, mezzanine or hybrid capital fills the gap. This is the zone where growth-stage companies most commonly find themselves.
The Gap-Fill Instrument: Mezzanine Financing Mechanics
Mezzanine financing is a hybrid instrument that sits between senior debt and equity in the capital structure. It bridges the gap between what senior lenders will provide and the total capital required (for acquisitions, growth investment, or ownership recapitalization) without forcing the operator to dilute at the equity level. The instrument is flexible by design: terms are negotiated case-by-case, with no standardized market pricing or documentation.
Component Breakdown
A typical mezzanine facility combines three economic elements:
- Cash Interest Coupon: A periodic cash payment, typically 8–12% per annum, paid quarterly. This is the senior income component for the mezzanine lender and the primary cash cost to the borrower.
- PIK (Payment-in-Kind) Component: Instead of paying interest in cash, the interest amount is added to the outstanding loan balance, compounding the principal over time. PIK allows the borrower to preserve near-term cash flow at the cost of growing the debt balance. PIK is increasingly prevalent: public BDCs now receive approximately 8% of investment income via PIK, and PIK features have entered mainstream use as cash conservation tools well beyond their traditional home in distressed or subordinated structures.
- Equity Kicker: Warrants or conversion rights that give the mezzanine lender exposure to the borrower’s equity upside. Equity kickers typically represent 1–5% of the borrower’s equity, granting the lender the right to purchase stock at a pre-agreed strike price. They enhance the lender’s total return without requiring immediate equity issuance.
Illustrative Term Sheet: A $35M Growth Acquisition Mezzanine
Consider a B2B software business with $8M EBITDA seeking to acquire a complementary platform for $50M enterprise value. A senior unitranche facility can fund 4.5x EBITDA = $36M. The remaining $14M gap, after $10M of sponsor equity, requires a $4M mezzanine piece alongside the transaction structure. Here is what a representative mezzanine term sheet looks like for a broader $35M stand-alone growth mezzanine facility:
ILLUSTRATIVE MEZZANINE TERM SHEET, BOND CAPITAL EDUCATIONAL EXAMPLE
Borrower: [Growth-Stage B2B SaaS / Technology Company, $12M EBITDA, $80M EV]
Facility Amount: $35,000,000 Term Loan
Use of Proceeds: Acquisition financing / growth capital
Seniority: Subordinated; ranking below senior unitranche ($55M) and above common equity
Cash Coupon: 10.0% per annum, paid quarterly
PIK Component: 3.0% per annum, added to principal; toggled at borrower election (with lender consent) if FCCR falls below 1.10x; PIK margin step-up of 100 bps during PIK periods
Total Stated Yield: 13.0% (10% cash + 3% PIK)
Equity Kicker: Warrants for 3.5% of fully diluted common equity; strike price at current enterprise value / share; 5-year exercise window
OID: 2.0% of funded principal (amortized over term)
Maturity: 6 years (bullet repayment)
Amortization: None (full bullet at maturity)
Call Protection: Non-callable years 1–2; 2% call premium year 3; 1% year 4; callable at par thereafter
Financial Covenant: Maximum total leverage ratio (tested quarterly); minimum FCCR of 1.05x
Intercreditor: Subordination agreement required with senior unitranche lender
Note: This is a Bond Capital illustrative example for educational purposes only. Terms are representative of current market practice and do not constitute a commitment to lend.
The true all-in cost to the borrower must account for all three economic components. Cash interest of 10% plus PIK of 3% plus warrant dilution (valued as an annualized cost over the expected hold period) and OID typically produces a lender return in the 14–18% gross IRR range. Investors targeting mezzanine strategies typically underwrite to 12–20% total returns, comprising cash coupon, PIK accretion, equity participation, and origination fees.
Mezzanine vs. Alternatives: Trade-Offs and Fit
Choosing mezzanine over its alternatives is a function of three variables: how much capital is needed beyond the senior ceiling, how much equity dilution the operator is willing to accept, and whether free cash flow can sustain cash interest obligations.
Unitranche + No Mezzanine
For deals where total leverage requirements sit below 5.5–6.0x EBITDA, a single-tranche unitranche from a direct lender eliminates complexity entirely. There is no intercreditor agreement, no subordination negotiation, and a single relationship to manage. The compression in unitranche spreads in 2025, with spreads falling from highs near 700 bps in 2022 to an average around 510 bps in 2025 per Capstone Partners, has made unitranche increasingly cost-competitive. The tradeoff: the unitranche ceiling is real. Lenders will not stretch leverage indefinitely, and for acquisitive growth strategies requiring 6.0–7.0x leverage, the gap persists.
Preferred Equity
Preferred equity occupies the layer directly above common equity. It is not debt, there is no fixed repayment obligation, but it typically carries a structured return (often 14–20% via PIK dividends or fixed coupons) plus liquidation preference. Preferred equity works well when a business cannot service additional cash interest (e.g., early-growth or pre-profitability stage) but can offer structured equity economics to capital providers. The cost is less flexibility: preferred holders often carry governance rights, board observers, or consent rights that mezzanine lenders typically do not demand.
Venture Debt (Pre-Profitability / High-Growth Stage)
For companies at an earlier growth stage, typically $2–10M ARR with significant top-line momentum but limited EBITDA, venture debt is the natural instrument. The global venture debt market reached approximately $49 billion in 2025, and the structure typically takes the form of a senior secured term loan with interest-only payments and a small warrant tranche. Venture debt does not require hard assets, profitability, or the strict covenant packages of bank credit. It is the right instrument when a company is extending runway between equity rounds or bridging to a profitability milestone, but it is not designed for the larger capital requirements of growth acquisitions or full recapitalizations.
Growth Equity (Common Equity Round)
Raising a common equity round solves the capital need but at the highest long-term cost. Median dilution in 2025 sat at approximately 18–19.5% per round at the Series A/B stage. By the time a company has run through multiple rounds, founder and early stakeholder ownership can be significantly diluted. The opportunity cost of equity dilution versus debt servicing is often underappreciated: a $5M growth facility at 15% annual cost over four years totals roughly $3M in interest; a $5M equity round at 25% ownership on a $50M eventual exit costs the equivalent of $12.5M in economic value. For operators who have strong and predictable cash flows and are close to a milestone that will re-rate the business’s valuation, structured debt is often the superior instrument.
Rule of thumb: Use senior debt first, mezzanine to extend leverage beyond the senior ceiling with acceptable cash cost, preferred equity when cash cannot service fixed interest, and common equity only when debt capacity is genuinely exhausted or when strategic investor value justifies dilution.
Current Market Terms and Structural Standards (2025–2026)
The private credit market in 2025–2026 is defined by an unusual combination: record dry powder, spread compression, and quietly rising credit stress. Understanding the current environment shapes both the available terms and the negotiating leverage available to borrowers.
Five Key Data Points for Structuring in 2026
- Spread compression is real but plateauing. After SOFR spreads peaked near 700 bps in 2022, the percentage of direct lending LBOs priced below 550 bps reached 81% in 2025, per PitchBook LCD. For 2026, material further compression is unlikely; the Capstone Partners Q4 2025 report notes no clear catalyst for further tightening. Borrowers who repriced in 2025 captured significant savings, but those coming to market now face a floor, not a continuing tailwind.
- PIK usage is rising across the stack. Once confined to mezzanine and subordinated debt, PIK features now appear in senior secured loan documentation. Public BDCs receive approximately 10% of investment income via PIK, per estimates from private capital research. Lenders are offering PIK toggles at a premium of 50–200 bps when activated, making them a meaningful (if expensive) cash-management tool for borrowers under pressure.
- Maintenance covenants have returned to mid-market private credit. In the broadly syndicated loan market, approximately 90% of new loans in 2024 remained covenant-lite. By contrast, private credit lenders have maintained firmer positions on covenant inclusion for mid-market transactions, anticipate at least one financial maintenance covenant (typically a total leverage ratio test) in private credit deals under $50M EBITDA. S&P Global Ratings analysis found that more than a third of credit-estimated borrowers subject to leverage-based maintenance covenants have loose thresholds with current headroom above 40%, however, suggesting many initial covenant packages are set wide at closing.
- DDTLs are now standard for acquisitive strategies. Many unitranche and mezzanine facilities now include Delayed Draw Term Loans (DDTLs) sized at 0.5–1.0x EBITDA, available for 12–18 months post-closing. For buy-and-build strategies, a DDTL eliminates the need to refinance for each tuck-in acquisition, providing committed capital certainty at pre-agreed pricing.
- Refinancing from private credit to BSL accelerated in early 2025. In Q1 2025, companies refinanced at least $7.3 billion of direct lending deals with broadly syndicated loans, the second-highest quarterly total in at least four years, with borrowers achieving an average spread saving of 263 bps, per PitchBook. For growth-stage borrowers who originally accessed private credit at peak spreads (2022–2023), a refinancing analysis should be a standing agenda item.
The Gap Capital Playbook: Quantifying, Preparing, Running the Process
The gap capital playbook has four phases: Quantify → Prepare → Run the Process → Negotiate the Structure. Each phase has specific deliverables and decision gates.
Phase 1: Quantify the Gap
Before approaching any capital provider, the operator must define the gap with precision. The inputs are:
- Total Capital Need (TCN): The full capital requirement for the transaction or initiative: acquisition price, working capital funding, capex, or recapitalization amount.
- Senior Debt Capacity: What a senior or unitranche lender will provide. This is typically the minimum of (a) a leverage multiple, 4.0–5.5x EBITDA, and (b) a debt service coverage test (typically minimum FCCR of 1.10–1.20x on a forward basis).
- Available Equity: How much equity capital the operator or sponsor is prepared to contribute. For recapitalizations, this may be zero; for acquisitions, sponsors typically target 35–50% equity contribution.
- The Gap: TCN minus Senior Debt Capacity minus Available Equity = the financing gap to be filled by mezzanine, preferred equity, or a hybrid instrument.
Operators should stress-test this gap across downside scenarios: if EBITDA contracts 15–20%, does the senior lender’s leverage test still clear? Does cash interest remain serviceable? What does the covenant cushion look like at closing versus stressed projections?
Phase 2: Prepare the Materials
Mezzanine and junior capital providers conduct bespoke, relationship-driven diligence. They evaluate historical cash flow, projected EBITDA, management track record, and the borrower’s ability to service both the senior debt layer and the new mezzanine piece concurrently. The core preparation package includes:
- 3-year audited financials with EBITDA bridge and adjustment schedule
- 12–18 month LTM management accounts demonstrating trend performance
- 5-year financial model with clearly labeled assumptions, including revenue drivers, margin profile, and debt service schedule (showing coverage at both senior and total debt levels)
- Use-of-proceeds memo: A clear one-to-two page narrative showing exactly how each dollar of the capital raise will be deployed and the expected return on that deployment: acquisition synergies, market expansion metrics, or operational leverage
- Capital structure waterfall: A visual summary of the post-closing stack, showing all tranches, pricing, leverage multiples, and coverage ratios
The use-of-proceeds memo is often under-invested by operators. Mezzanine lenders are pricing equity risk alongside debt risk; they want to understand the value creation thesis, not just the ability to service the coupon. A clear GTM expansion plan, an accretive acquisition thesis with stated synergy assumptions, or a demonstrable path to EBITDA expansion are the narratives that unlock the best terms.
Phase 3: Run the Process
Unlike bank credit, mezzanine and junior capital markets are relationship-driven and non-syndicated. The process typically involves outreach to 5–10 targeted capital providers: specialist mezzanine funds, BDC platforms, family office credit arms, and hybrid capital funds. The hybrid fund category has grown meaningfully: newer “hybrid” junior capital funds tend to combine contractual cash flows with warrants or preferred equity, rather than relying purely on PIK as the older mezzanine model did. Running a competitive process across at least three live term sheets is the standard that unlocks real price tension.
Timeline: mezzanine diligence typically runs 4–8 weeks from NDA execution to term sheet. Fund-to-fund intercreditor negotiation between the senior lender and the mezzanine provider adds 2–3 weeks. Total process time from launch to close: 8–14 weeks, versus 4–6 weeks for a unitranche-only process.
Negotiation Guidance: Key Structural Deal Points
Once term sheets are in hand, the following are the highest-leverage negotiation points for growth-stage borrowers structuring mezzanine or junior capital:
For Operators and Borrowers
- PIK Toggle Triggers and Step-Up Margin: Push for a PIK toggle that activates at borrower election, not solely as a distress trigger, to preserve optionality. Negotiate the step-up margin for PIK periods down from the market standard of 100–200 bps to 50–100 bps. Ensure PIK elections are available for at least the first three years of the facility, when growth investment is highest and free cash flow is thinnest.
- Warrant Coverage and Strike Price: Equity kickers typically represent 1–5% of fully diluted equity. Negotiate (a) the percentage, pushing below 3% where deal quality supports it, (b) the strike price, which should be set at or above the current enterprise value per share, not at a discount, and (c) the vesting and expiry mechanics. Where possible, negotiate buyout rights that allow the borrower to repurchase warrants at a pre-agreed formula before a liquidity event.
- Covenant Headroom: The leverage ratio definition, starting threshold, and step-down schedule are among the most consequential and heavily negotiated terms. Because the leverage ratio drives maintenance testing, incurrence baskets, pricing mechanics, excess cash flow sweeps, and amendment negotiations, its definition deserves granular scrutiny. Argue for EBITDA definitions that include appropriate add-backs for non-recurring items, integration costs, and run-rate synergies. Push the opening maintenance covenant threshold to at least 35–40% above closing leverage to create real operational headroom.
- Call Protection Structure: A standard mezzanine make-whole provision can be extremely punitive if the business outperforms and refinancing becomes attractive. Push for a hard call schedule (e.g., NC-1 / 2% / 1% / par) rather than an open-ended make-whole or net present value premium calculation, which can be extremely costly in a declining rate environment.
- DDTL Commitment for Add-On Acquisitions: For acquisitive strategies, negotiate a committed Delayed Draw Term Loan as part of the original mezzanine facility. This secures capital certainty for future tuck-in deals at pre-agreed pricing without requiring a full re-documentation process for each acquisition.
For Investors and Credit Providers
When evaluating growth-stage mezzanine exposure, the key structural risk points are: (1) the quality and realism of EBITDA add-backs, which inflate apparent leverage headroom; (2) PIK compounding and its interaction with equity kicker value at exit; and (3) intercreditor subordination terms and the degree of control rights the senior lender retains in a default scenario. Ensure that call protection mechanics are coordinated with warrant valuation so that a prepayment event does not destroy the economics of the equity kicker component.
Key Takeaways
- ▶ The gap is structural, not a failure signal. Most growth-stage companies have a legitimate financing gap between senior debt capacity (3.0–5.5x EBITDA) and total capital need. Mezzanine and hybrid instruments exist specifically to fill this space without forcing premature equity dilution.
- ▶ Use-of-proceeds drives structure choice. Working capital needs favor revolving credit; acquisitions favour unitranche + DDTL or senior + mezz; recapitalizations and owner liquidity events favour hybrid capital or preferred equity; runway extension for pre-profitability companies favours venture debt. Match the instrument to the use-case before approaching lenders.
- ▶ PIK is a tool, not a red flag, when structured correctly. PIK toggles preserve near-term cash flow for growth investment. The risk is compounding: a $50M PIK facility at 11% grows to approximately $84M in outstanding principal over five years if entirely PIK’d. Model the terminal debt load, not just the opening coupon, before committing to a PIK-heavy structure.
- ▶ Covenant headroom is worth negotiating hard. In private credit, maintenance covenants remain the standard for sub-$50M EBITDA deals. S&P Global Ratings data shows that more than a third of middle-market borrowers have leverage covenant headroom above 40%, but that headroom was typically set at closing, not earned. Negotiate the opening threshold, the EBITDA definition, and the step-down schedule with equal rigour.
- ▶ Run a competitive process, always. Mezzanine and private credit markets have record dry powder and strong lender competition. Dry powder within U.S. direct lending funds hit a record $146 billion at end-2025 per PitchBook LCD. Operators who run a structured process across 5–10 targeted providers consistently extract better pricing, wider covenant packages, and more borrower-friendly call protection than those who negotiate with a single incumbent lender.


