
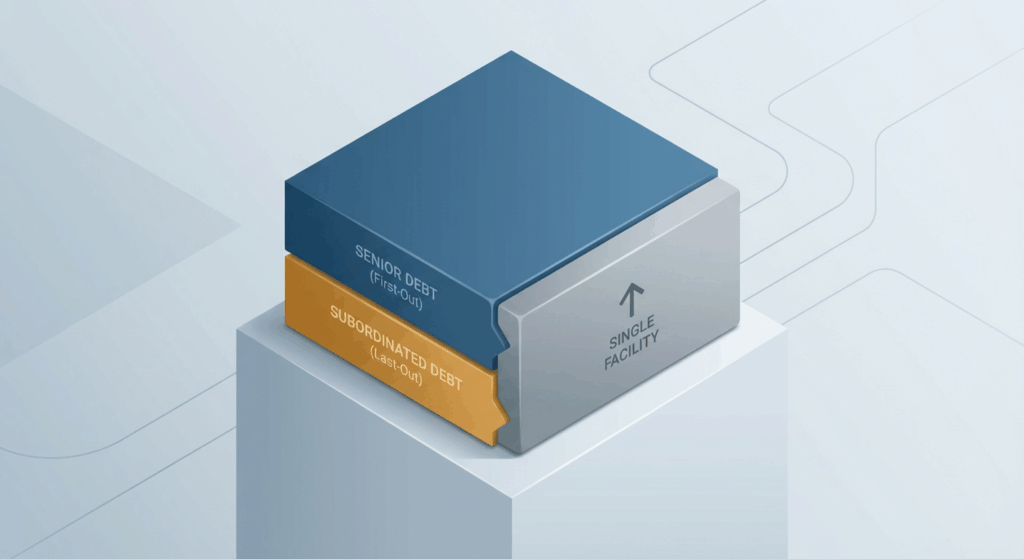
For middle-market operators and private equity sponsors, the financing landscape has shifted decisively toward execution speed and certainty. The “unitranche” facility (a hybrid loan structure combining senior and subordinated debt into a single instrument) has become the dominant financing tool for leveraged buyouts (LBOs) and significant acquisitions. While historically a middle-market product, unitranche structures have scaled up, with “jumbo” unitranches now challenging the broadly syndicated loan (BSL) market.
This deep dive unpacks the mechanics of unitranche financing, using a practical term sheet example to illustrate how the economics work behind the scenes and how borrowers can negotiate effectively in the current 2026 market environment.
Structure Breakdown: The “Bifurcated” Reality
On the surface, a unitranche facility appears simple: one credit agreement, one set of covenants, one agent, and a single blended interest rate. However, the internal mechanics often involve a “bifurcation” of risk between lenders, governed by an Agreement Among Lenders (AAL).
Unlike a traditional intercreditor agreement (which the borrower signs), the AAL is a private contract between lenders that creates a “first-out” and “last-out” waterfall structure within the single lien.
Deal Example: $150M Unitranche Facility
Consider a software company with $30M EBITDA sought for acquisition at a 10.0x multiple ($300M EV). The sponsor requires $150M in debt financing (5.0x leverage).
- Borrower View (The “Unitranche”):
- Total Facility: $150M Term Loan
- Interest Rate: SOFR + 650 bps (Blended)
- Leverage: 5.0x total net leverage
- Documents: Single Credit Agreement
- Lender View (Behind the Scenes):
- First-Out Tranche ($100M): Held by a traditional bank or low-cost insurance fund.
- Risk: 0.0x – 3.3x leverage
- Return: SOFR + 475 bps
- Last-Out Tranche ($50M): Held by a specialized private credit fund.
- Risk: 3.3x – 5.0x leverage (Junior risk)
- Return: SOFR + 1000 bps
- First-Out Tranche ($100M): Held by a traditional bank or low-cost insurance fund.
The “Last-Out” lender typically acts as the administrative agent and holds the relationship, while the “First-Out” provider essentially provides quiet backend leverage to the structure to drive down the blended cost of capital.
How It Compares: Unitranche vs. Traditional Structures
The strategic choice often comes down to Unitranche versus a Senior + Mezzanine split.
| Feature | Unitranche | Senior + Mezzanine |
|---|---|---|
| Execution | Single document, one closing process. Speed premium (30-45 days faster). | Two credit agreements, complex intercreditor negotiation. Slower execution. |
| Certainty | High. Bilateral terms usually fixed early. No “market flex” in direct lending. | Moderate. Senior syndication risk can alter terms closing (flex pricing). |
| Cost | Higher blended rate (e.g., S+650). | Often lower WACC (e.g., Senior at S+400, Mezz at 12% fixed). |
| Amortization | typically 1% per annum. | Senior amortizes (5-10%); Mezz is interest-only (bullet). |
Trade-off: Borrowers pay a “speed premium” of approximately 50–100 basis points in yield for the unitranche to avoid the administrative burden of two lender groups and the execution risk of syndication.
Current Market Terms (2025-2026 Trends)
As of early 2026, private credit markets have matured, stabilizing terms for borrowers.
- Pricing: All-in yields for standard middle-market unitranches are hovering around 11.5% – 13.0%. Spreads have compressed slightly as competition among direct lenders increases.
- Leverage: Total leverage ratios for high-quality credits remain near 5.0x – 5.5x, with highly recurring revenue models (SaaS) sometimes commanding higher turns.
- Jumbo Unitranches: Deals exceeding $2 billion are becoming standardized, often syndicated among a small “club” of direct lenders rather than a single hold. These large deals increasingly adopt “cov-lite” terms similar to the BSL market, dropping maintenance covenants in favor of incurrence covenants.
- Documentation: For middle-market deals ($20M – $50M EBITDA), maintenance covenants (typically a leverage ratio application) remain standard, tested quarterly.
Structuring Guidance & Negotiation
For Operators and Sponsors
When negotiating a unitranche, the headline interest rate is only one variable. Focus leverage on:
- “Holiday” Periods: Negotiate for the ability to PIK (Payment in Kind) a portion of the interest for the first 12-24 months to preserve operating cash flow.
- Acquisition Facilities: Ensure the facility includes a committed “delayed draw term loan” (DDTL) to fund future add-on acquisitions without renegotiating the credit agreement.
- Call Protection: Private credit funds typically demand call protection (e.g., 102/101 soft call). Push for “portability” clauses that allow the debt to stay in place if the company is sold, potentially increasing exit valuation.
For Investors
In a bifurcated structure, understand the voting rights in the AAL. Does the “Last-Out” lender (who holds the riskier tranche) have the right to drag the “First-Out” lender into a restructuring enforcement? Or can the First-Out lender block actions? The alignment of interests during a workout scenario is defined entirely by this private document.
Key Takeaways
- Singular Interface: Unitranche offers borrowers one set of loan documents and one interest rate, masking complex backend risk-sharing.
- Speed Premium: Borrowers often pay ~50-100 bps more than syndicated solutions in exchange for closing speed and execution certainty.
- Hidden Bifurcation: “First-Out/Last-Out” structures allow lenders to blend cheap senior capital with expensive junior capital to achieve competitive yields.
- Covenant Flexibility: While jumbo deals are going cov-lite, core middle-market unitranches still typically require maintenance covenants.
- Scalability: The structure now supports multi-billion dollar capital needs, making it a viable alternative to the public loan markets.


