
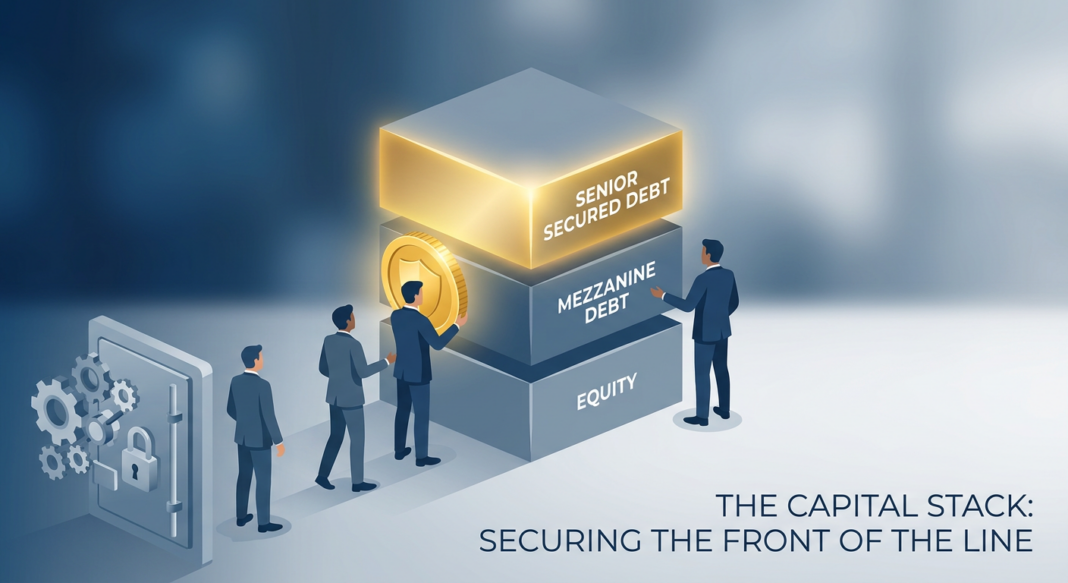
The Concept That Determines Who Gets Paid, And Who Gets Wiped Out
When a company borrows money, not all lenders are treated equally. Whether a business is humming along or heading toward default, the capital stack: the ordered hierarchy of every financial claim on a company’s assets and cash flows: determines exactly who gets repaid first, who waits, and who absorbs losses. For anyone evaluating private credit, or any business owner exploring financing options, understanding capital stack position may be the single most important concept in the entire asset class.
The stack is not theoretical. It is a legally enforced pecking order that plays out in real time whenever a borrower misses a payment, breaches a covenant, or files for bankruptcy. Position in that pecking order directly determines yield, risk, and recovery, which is why two funds that both call themselves “private credit” can have dramatically different risk profiles depending on where in the stack they actually sit.
How the Capital Stack Works: From Top to Bottom
According to BIP Wealth, the capital stack flows from the lowest-risk, highest-priority claims at the top to the highest-risk, last-priority claims at the bottom. Each layer earns a return that reflects the risk of its position. Here is how the layers are typically structured, from safest to riskiest:
- Working Capital / Senior Revolving Credit: Short-term obligations funding day-to-day operations. Repaid first. Lowest yield.
- Senior Secured Debt: Long-term loans backed by the company’s tangible collateral: equipment, receivables, real property. First in line among long-term creditors. This is the primary focus of most direct lending funds.
- Subordinated Debt (Mezzanine): Repaid only after senior lenders are made whole. Carries a higher coupon to compensate for the lower priority position.
- Convertible Debt: A hybrid instrument, starts as debt but can convert to equity under defined conditions. Offers some downside protection with equity-like upside potential.
- Preferred Equity: Ownership with priority over common shareholders for dividends and liquidation proceeds. Riskier than any debt layer.
- Common Equity: Last to be repaid and first to absorb losses. Bears the greatest risk but captures all residual upside.
The analogy is simple: think of the capital stack as a line outside a bank vault. Senior secured lenders are at the front. Common equity holders are at the back. If the vault runs low, the people at the back go home empty-handed.
A Concrete Example: The $50 Million LBO
Consider a private equity firm acquiring a manufacturing company for $50 million. The deal is structured with the following capital stack:
- Senior Secured Term Loan, $30 million (60% of deal value): Provided by a direct lending fund at a floating rate of SOFR + 575 basis points. Backed by all company assets. First priority lien.
- Mezzanine / Subordinated Debt, $8 million (16% of deal value): Provided by a subordinated lender at a fixed rate of 13%. Second lien or unsecured. Repaid only after the senior loan is satisfied.
- Common Equity, $12 million (24% of deal value): Contributed by the private equity sponsor. Last in line. No fixed return, upside is the residual value of the business at exit.
Now imagine the business deteriorates and is eventually liquidated for $35 million: a 30% decline from the purchase price. Here is how the recovery plays out:
- Senior secured lender recovers the full $30 million. ✓
- Mezzanine lender recovers $5 million of the $8 million owed. Partial loss.
- Equity sponsor recovers nothing. Total loss on $12 million.
The equity cushion: the $12 million of sponsor equity sitting below the senior loan, acted as a buffer, absorbing the first $15 million of value decline before the senior lender was touched. This structural protection is why senior secured direct lenders can underwrite at tighter spreads than mezzanine lenders and still deliver favorable risk-adjusted outcomes.
Why This Matters in Today’s Private Credit Market
The capital stack framework is not just academic; it is directly relevant to the structural forces reshaping credit markets right now.
According to PitchGrade’s 2026 Private Credit Primer, global private credit AUM has surpassed $1.7 trillion as of Q1 2026, with senior secured direct lending representing the dominant strategy. The same source notes that 75% or more of leveraged buyout financing in deals below $500 million in EBITDA is now provided by private credit funds rather than bank lenders, a structural shift driven by Basel III capital requirements that make leveraged lending economically unattractive for banks at comparable returns on equity.
As noted by Long Angle’s Private Credit Investment Guide 2026, bank lending as a share of U.S. GDP has fallen from approximately 59% in Q4 2008 to roughly 44% as of Q1 2025, and private credit has expanded to fill that gap, now comprising an estimated 20% of the leveraged credit market. Private credit AUM was estimated to exceed $2 trillion in 2025, with projections reaching $4.5 trillion by 2030.
For context on returns by stack position, PitchGrade reports that middle market senior secured direct loans currently price at approximately SOFR + 500–650 basis points, while large-cap direct lending deals price at SOFR + 425–500 basis points. The 200–350 basis point premium over broadly syndicated loans reflects the illiquidity premium and the structural advantages of bilateral origination, not necessarily additional credit risk at the senior secured level.
Meanwhile, Blackstone’s Essentials of Private Credit resource highlights that direct lending has historically generated approximately a 200 basis point premium over leveraged loans on a sustained basis, a compounding advantage that meaningfully separates long-term outcomes between the two strategies.
| Stack Layer | Typical Spread (2026) | Source |
|---|---|---|
| Senior Secured (Mid-Market) | SOFR + 500–650 bps | PitchGrade, 2026 |
| Senior Secured (Large Cap) | SOFR + 425–500 bps | PitchGrade, 2026 |
| Premium vs. Broadly Syndicated Loans | +200–350 bps | PitchGrade, 2026 |
| Direct Lending Premium vs. Leveraged Loans (Historical) | ~200 bps sustained | Blackstone, 2024 |
| Direct Lending Default Rate (Since 2021) | <4% | Long Angle / Proskauer, 2026 |
Decision Framework: Investors and Operators
For Investors Evaluating Private Credit: Capital stack position is the first question to answer before evaluating yield. A fund offering a 14% return in subordinated debt is not comparable to one offering 11% in senior secured, the subordinated fund is absorbing losses before the senior lender even notices a problem. Investors consider: What lien position does the fund hold? What is the loan-to-value ratio? How much equity cushion sits below the loan? According to Long Angle, top-quartile private credit managers outperform bottom-quartile peers by roughly 3.5% annually, and that dispersion is heavily influenced by disciplined underwriting standards and consistent stack positioning.
For Business Owners Seeking Capital: Understanding where a lender sits in your capital stack matters for cost of capital decisions. Senior secured debt is typically the cheapest form of non-bank financing because the lender carries the least risk; they are first in line. Mezzanine lenders price their higher position in the stack with higher rates. As noted by the LSTA’s Private Corporate Credit FAQ, private credit lenders often offer flexibility that banks cannot (including above-6x leverage multiples, covenant flexibility, and speed of execution) but operators should evaluate total cost of capital across all stack layers, not just the senior rate in isolation.
Key Takeaways
- Position determines protection. Senior secured lenders are first in line for repayment in any outcome: default, restructuring, or liquidation. That priority is legally enforceable, not aspirational.
- The equity cushion is your margin of safety. In a typical private credit deal, sponsor equity absorbs the first 20–40% of value decline before a senior lender’s principal is impaired. The size of that cushion is a core underwriting variable.
- Higher yield does not automatically mean better risk-adjusted return. Mezzanine debt pays more than senior secured debt because it carries more risk, not because the manager is more skilled. Stack position explains the difference.
- The bank retreat has structurally expanded private credit’s role at every stack layer. With banks constrained by capital requirements from leveraged lending above 6x debt/EBITDA, private credit funds now originate and hold senior secured loans that banks would have syndicated a decade ago.
- Always ask: where in the line am I standing? Before evaluating any private credit fund, manager, or loan, identify the lien position, the collateral package, and the equity below the debt. Everything else (spread, maturity, covenants) is secondary to those three structural facts.


