
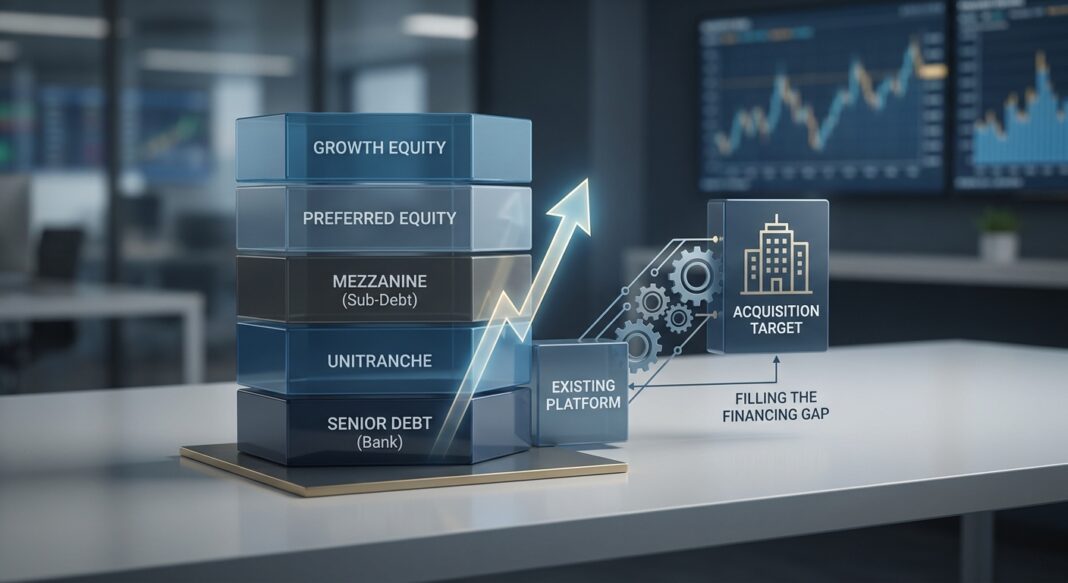
The Financing Challenge: Growth Has Outrun the Balance Sheet
You are running a $12M EBITDA services or software business. You have identified a bolt-on acquisition at a $60M enterprise value: a target that would add recurring revenue, expand your geographic footprint, and meaningfully accelerate an exit timeline. Your bank will lend 3–4x normalized EBITDA. That gets you to roughly $36–$48M. The equity required to bridge the gap between your bank’s offer and the deal price is more than your team can write (or wants to write) at this stage of the company’s life.
This is the acquisition financing gap. And in 2026, it sits at the center of almost every mid-market growth narrative.
The good news: the market has never offered more tools to fill it. Private credit assets under management reached approximately $2.1 trillion globally in 2025, and the financing menu now spans bank senior debt, unitranche, mezzanine, preferred equity, and growth equity minority stakes: each carrying a different cost, structure, and dilution profile. The discipline is knowing which instrument belongs at which layer, and why.
This article maps the full acquisition capital stack for growth-stage operators, walks through a representative deal scenario, compares unitranche and mezzanine structures using current market terms, explains the covenant trade-off between private credit and the syndicated market, and provides a step-by-step gap capital playbook for running the process.
The Cost of Capital Spectrum: Banks to Equity
Every acquisition capital structure begins with the same exercise: mapping available capital sources from cheapest to most expensive, then filling from the bottom up. For a growth-stage operator in the $5M–$25M EBITDA band in 2026, the hierarchy looks like this:
| Layer | Instrument | Indicative Cost (2026) | Typical Leverage |
|---|---|---|---|
| Senior Secured | Bank term loan / revolver | SOFR + 250–350 bps | 3–4x EBITDA |
| Unitranche | Single-tranche direct loan | SOFR + 475–650 bps (~10–11% all-in) | 4–5x EBITDA |
| Mezzanine | Sub-debt with PIK + warrants | 11–14% cash + 1–4% PIK + 1–5% equity | 5–6x EBITDA (combined) |
| Preferred Equity | Structured equity with preference | 15–20% IRR target | Non-leveraged; dilutive |
| Growth Equity | Minority or majority stake | 20–30%+ IRR target | Dilutive; ownership transfer |
The practitioner’s rule: fill from the bottom of the stack first. Every dollar of bank debt at SOFR + 300 bps is structurally cheaper than a dollar of growth equity diluting your cap table at a 25% IRR hurdle. The goal is to maximize the debt layers available to you, calibrated against the company’s realistic debt service capacity, before touching equity.
The tension in 2026 is that capital is concentrating into fewer companies, with larger checks flowing primarily to later-stage and AI-driven businesses. For operators outside that narrow lane, building a deliberate, multi-source capital stack has never been more important.
Structure Breakdown: Two Paths Through the Gap
Scenario: $60M Acquisition by a $12M EBITDA Platform
Your platform generates $12M EBITDA. You are acquiring a target at a $60M enterprise value (5.0x EBITDA). You need to fund the acquisition without surrendering control or exhausting equity capacity needed for the next add-on. Here are two structural paths:
Path A: Unitranche Only
A unitranche facility is a single-tranche debt structure that combines what would traditionally be separate senior and subordinated debt layers into one loan with one set of documents, one interest rate, and one lender relationship. The borrower deals with a single credit agreement and, critically, there is no intercreditor agreement to negotiate.
- Facility size: $54M unitranche (4.5x combined EBITDA)
- Pricing: SOFR + 525 bps (~10.2% all-in as of mid-2026, per S&P LCD data)
- Amortization: 1% per annum / bullet maturity at year 5–6
- Equity required: ~$6M (10% of purchase price)
- Covenant: Single maintenance leverage test, typically set at 6.0–6.5x with 25–35% headroom to closing leverage
- Execution timeline: 45–90 days from term sheet to close
The $50M–$200M enterprise value band is the heart of the unitranche market. Direct lenders compete aggressively for deals in this range, with pricing at its tightest and terms most flexible. In this EV band, virtually all major lower middle market PE firms run their platform financing on unitranche structures.
Path B: Senior Bank + Mezzanine
Mezzanine debt is a hybrid form of capital that sits between senior debt and equity in the capital stack, a funding bridge that fills the gap between what a traditional bank will lend and the total deal cost.
- Senior bank facility: $36M (3.0x EBITDA) at SOFR + 275 bps (~7.0% all-in)
- Mezzanine tranche: $15M at 12% cash coupon + 2% PIK + warrants covering ~3% of fully diluted equity
- Combined leverage: 4.25x EBITDA
- Equity required: ~$9M (15% of purchase price)
- Intercreditor: Required, senior lender controls enforcement; mezz has cure rights
- Execution timeline: 8–14 weeks, parallel tracking of two processes
A typical 2026 mezzanine rate for a healthy $5M–$15M EBITDA lower-middle-market company runs 11–14% cash coupon plus 1–4% PIK, with warrant coverage of roughly 1–5% of fully diluted equity. The key structural reality: a mezzanine facility advertised at 14% interest is not a 14% cost of capital: it is 14% plus PIK that compounds over a 3–5 year term, plus warrants, plus origination fees. Operators must model the true all-in cost before committing.
When a borrower elects PIK interest, the outstanding principal balance compounds: if the anticipated liquidity event is delayed, the growing PIK balance creates a larger refinancing burden at bullet maturity, a risk that can become severe in deteriorating markets.
Unitranche vs. Senior + Mezz: When to Use Each
Traditional senior plus mezzanine can achieve a lower weighted cost of capital if mezzanine carries equity kickers, but intercreditor complexity slows execution and reduces flexibility. Unitranche wins on speed, confidentiality, and single-document control.
| Dimension | Unitranche | Senior + Mezz |
|---|---|---|
| All-in cost | ~10–11% (SOFR + 475–650) | Potentially lower blended, but warrants add real cost |
| Execution speed | 45–90 days | 90–150 days (two parallel processes) |
| Leverage capacity | 4–5x EBITDA | 4.5–6x (combined layers) |
| Documentation | Single credit agreement | Two agreements + intercreditor |
| Equity dilution | None (debt only) | 1–5% via mezz warrants |
| Refinancing flexibility | One consent required | Consent from both lenders |
| Best for | Speed-critical, $25M–$200M EV | Large deals, cost optimization, add-on constraints |
Traditional mezzanine debt has not disappeared despite the unitranche’s rise. It remains relevant in specific contexts: very large transactions where unitranche lenders cannot provide the full quantum of debt needed; situations where the borrower wants to minimize total cost by maximizing cheaper senior debt separately; deals where the sponsor or management team wants equity kickers to align lender incentives; and portfolio company add-on financings where existing credit agreements restrict additional senior debt.
For issuers with near-term public-market refinancing catalysts that can achieve tighter spreads in broadly syndicated loan or bond markets, those options should also be modeled. In risk-on markets with active CLO demand, broadly syndicated term loans typically price inside unitranche: the premium for unitranche buys speed, certainty, and the absence of syndication flex risk.
Current Market Terms: What the Data Shows in 2026
The 2026 private credit market is navigating what practitioners are calling a lender-friendly inflection. After a period where spreads compressed, leverage moved higher, and loan documents became more flexible, the market has reset in a direction that favors lenders. Borrowers entering processes today should calibrate around the following verified benchmarks:
- Unitranche pricing ($5M–$50M facilities): Median all-in coupons on unitranche facilities in the $5M–$50M band are clearing at approximately 10.2% as of mid-2026, per S&P LCD comparable data. Current middle-market spreads run approximately SOFR + 475 to 550 bps for mid-sized deals in the $40M–$100M EBITDA range, per Lincoln International’s Q1 2026 private market data.
- Mezzanine pricing: A typical 2026 mezzanine rate for a healthy lower-middle-market company runs 11–14% cash coupon plus 1–4% PIK, with warrant coverage of roughly 1–5% of fully diluted equity, producing a blended cost of capital of 15–18% inclusive of the equity kicker. GF Data and Lincoln International both reported cash coupons drifting down from 2024 peaks as senior spreads compressed through the first half of 2026.
- Leverage multiples: Average total leverage in sponsored middle-market unitranche deals hovered around 5.0x EBITDA in mid-2024, with TCW data showing middle market leverage climbing from 4.5x to 5.5x over the past decade. Senior bank loans in the lower middle market generally advance 3–5x normalized EBITDA.
- Covenant standards: The distinction between maintenance and incurrence covenants represents one of the most significant structural differences between private credit and the broadly syndicated loan market. In the syndicated market, covenant-lite structures (incurrence only) are dominant, over 85% of institutional leveraged loans now lack the quarterly testing that gives lenders early warning of trouble. In direct lending and private credit, maintenance covenants remain the standard. KBRA DLD Research and ABF Journal data show that 98% of lower-middle-market loans with borrower EBITDA below $50M retain full financial maintenance covenant packages.
- Typical maintenance tests: A maximum leverage ratio is typically set at 4–6x depending on the industry and transaction; a minimum interest coverage ratio is usually set at 1.5–2.5x; and a minimum fixed charge coverage ratio provides a broader test of the company’s ability to meet all fixed obligations. Maintenance covenants are tested quarterly and reported through compliance certificates delivered alongside financial statements.
The private credit market has reached a pivotal stage, with direct lending now matching the broadly syndicated loan market at $1.5–2 trillion in size and forecast to reach $3 trillion by 2028. For operators in the core middle market, these are companies large enough to have scale and operating history, but generally not large enough to rely on liquid markets as a competing financing source, making private credit relationships structurally important.
The Gap Capital Playbook: Quantify, Prepare, Run, Negotiate
Running an acquisition financing process is not a one-call exercise. It is a structured, four-phase workflow that begins well before a term sheet is signed.
Phase 1: Quantify the Need
Begin with absolute clarity on four questions: How much capital is needed? For what specific purpose? Over what deployment timeline? What is the expected financial return on that capital? These answers are not always obvious at the start, but they shape every decision that follows.
Build a detailed sources and uses table. Map total acquisition cost (purchase price plus fees) against each proposed capital layer. Stress-test the DSCR (debt service coverage ratio) at 80% of base-case EBITDA. If the structure fails the stress test, you are over-leveraged regardless of what the lender will approve.
Phase 2: Prepare the Materials
Private credit lenders underwrite to the business, not just the collateral. Your process package should include: a trailing-twelve-months and projected EBITDA bridge (with add-backs clearly documented and capped, market convention for pro forma cost savings add-backs clustered around 25–35% of EBITDA); a quality of earnings summary; a customer concentration analysis (lenders flag accounts above 20–30% of revenue); an industry outlook; and a use-of-proceeds memo that explicitly maps each dollar of capital to a business outcome. Smart CFOs build a data room that answers lender questions before they are asked.
Phase 3: Run the Process
For a $40M–$100M unitranche: approach 4–6 direct lenders simultaneously. For a senior + mezz structure: run the senior process first, then layer the mezzanine. From signed indication of interest to funded, a mezzanine deal for an LMM transaction typically closes in 8–14 weeks; a unitranche closes in 45–90 days. The speed advantage of unitranche matters most for operators running roll-up platforms with frequent add-ons, where execution certainty is as valuable as pricing.
Identify the right lender universe for your deal size. The $50M–$200M EV band is the most competitive for unitranche, major direct lenders compete aggressively, creating favorable dynamics for borrowers. Below $25M EV, SBA and senior bank structures win on cost. Above $300M EV, broadly syndicated loans win on cost.
Phase 4: Negotiate the Structure
The debt market for quality borrowers remains competitive, meaning borrowers retain meaningful negotiating leverage, particularly in the large-cap segment, but also across well-credentialed middle market credits. Key negotiation points for operators:
- Covenant headroom: Push for 30–35% headroom on the leverage maintenance test to closing leverage. Tighter headroom creates unnecessary waiver risk on temporary EBITDA dips post-acquisition.
- Incremental capacity: Negotiate a grower basket or ratio-based incremental facility to preserve the ability to finance future add-ons without a full amendment process. Note that the "no worse than" test, allowing incremental debt as long as leverage does not increase, is frequently pushed back on by lenders in the middle market.
- PIK toggle: If mezzanine is in the structure, negotiate a PIK toggle option that allows you to defer cash interest to principal during integration periods, preserving free cash flow for operations.
- Prepayment premiums: Call protection on unitranche typically runs 2–1–0 (2% in year one, 1% in year two, none thereafter). Negotiate for a soft call structure rather than a hard make-whole if a refinancing event is anticipated within 24 months.
- Warrant coverage (mezz): Every warrant granted to a mezzanine lender dilutes existing common equity. In a successful exit, the equity kicker reduces returns available to the sponsor and management team. Where possible, negotiate a fixed-price warrant buyout option triggered at a defined MOIC threshold.
Structuring Guidance: For Operators and Investors
For operators: Model the blended cost of capital, not the stated interest rate, before selecting a structure. A mezzanine facility at 13% cash carry is not a 13% cost of capital once PIK compounding, warrant dilution, and origination fees are included. Compare structures on IRR-to-exit, not headline rate. Use equity for growth that requires speed you cannot otherwise afford; use debt to preserve ownership and leverage tax deductibility.
For investors evaluating capital structure: In any sponsored deal, ask: what is the leverage covenant headroom at close? What percentage of the loan book carries full maintenance covenant packages? Rising PIK provisions signal that cash interest can no longer be fully serviced, a visible early warning of borrower strain. Restructurings initiated at the covenant-breach stage, before a payment default, produce materially higher recoveries than those triggered by missed payments. The early-warning function of maintenance covenants is not a documentation formality.
The most capital-efficient growth-stage companies use both debt and equity strategically. Smart CFOs do not think in terms of "debt or equity." They think in terms of blended cost of capital, and they build the stack that minimizes dilution, preserves operating flexibility, and funds the specific use of proceeds in front of them.
Key Takeaways
- ✔ Fill the stack from the bottom up: Every dollar of senior bank debt at SOFR + 275–350 bps is structurally cheaper than a dollar of mezzanine or equity, maximize it before touching higher-cost layers.
- ✔ Unitranche dominates the $25M–$200M EV acquisition market because it delivers 4–5x leverage, single-document simplicity, and 45–90 day execution at approximately 10.2% all-in as of mid-2026 (S&P LCD).
- ✔ Mezzanine fills the gap without forced dilution, but the all-in cost, 11–14% cash coupon + 1–4% PIK + 1–5% warrant coverage, produces a blended 15–18% cost of capital that must be modeled against the unlevered return of the acquisition.
- ✔ Private credit maintenance covenants are a structural feature, not a burden: 98% of lower-middle-market loans below $50M EBITDA retain full financial maintenance covenant packages, giving lenders early intervention rights and borrowers a structured negotiation path if performance softens.
- ✔ Run the gap capital process like a competitive auction: Approach 4–6 lenders simultaneously, prepare a lender-grade data room before outreach, and use competing term sheets to negotiate headroom, call protection, and incremental capacity, not just rate.


