
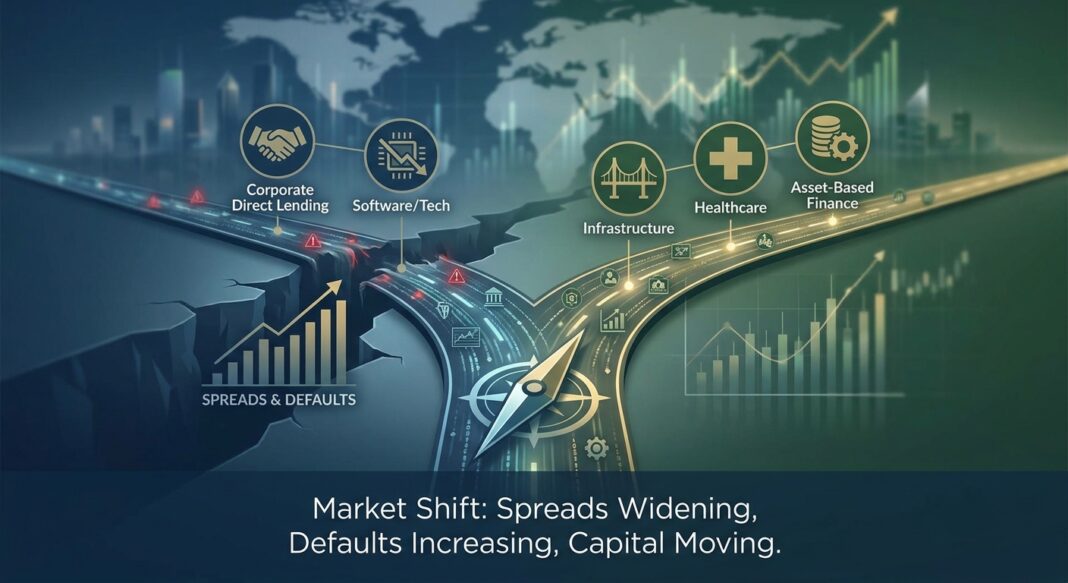
Market Headline: The Lender-Friendly Reset Is Here, But So Is the Stress
The private credit market has arrived at a defining inflection point in Q3 2026. After years of relentless spread compression and covenant erosion, market forces (amplified by geopolitical shock, AI-driven sector disruption, and a “higher-for-longer” rate regime) have conspired to produce what Lord Abbett’s midyear team calls a lender-friendly reset. For the first time in the post-pandemic cycle, lenders are reclaiming pricing power, documentation discipline, and deal selectivity. For borrowers, the calculus has shifted materially: the window of ultra-cheap capital has closed, and KPI thresholds (particularly Fixed Charge Coverage Ratios (FCCR) and leverage multiples) are under renewed scrutiny.
The macro backdrop is unambiguous. Heightened volatility in early 2026, driven by AI-related disruption concerns and geopolitical developments, pushed credit markets back into price discovery mode, slowing primary market activity and widening secondary spreads, particularly for technology and software-exposed credits. A geopolitical shock in February, including renewed Middle East conflict, reinforced a risk-off tone that reverberated through leveraged finance. The stock market dipped, the price of oil and gas rose, triggering fears of renewed inflation and damping the prospect for interest rate cuts.
Regulatory pressure has materialized as well. On 6 May 2026, the Financial Stability Board (FSB) issued a formal report on vulnerabilities in private credit, forming part of its work programme to enhance resilience in non-bank financial intermediation. The FSB warned that the private credit sector’s complexity, leverage, and interconnectedness could amplify stress in adverse scenarios, posing broader risks to financial stability. For institutional investors and operators, this is not background noise; it is a structural signal that the regulatory and underwriting environment for private debt is tightening in ways that will reshape access, pricing, and covenant architecture for the next several years.
Quantitative Market Snapshot
| Metric | Current Value | Prior Period | Direction | Source |
|---|---|---|---|---|
| Middle Market Private Credit Spreads | SOFR + ~500 bps | SOFR + mid-400s bps (late 2025) | ▲ Wider | Hamilton Lane, 2026 |
| 3-Month Term SOFR | 3.75% (July 2026) | 3.68% (June 2026) | ▲ Slight rise | Fidelity / Bloomberg, July 2026 |
| Unitranche Coupon Spreads | 4.75%–5.50% | ~4.50%–5.25% (YE 2025) | ▲ ~25 bps wider | VRC Q2 2026 |
| High Yield OAS (Public) | ~266 bps (Sep 2026) | ~308 bps (Mar 2026) | ▼ Tighter (vs. private) | ICE BofA via FRED, Sep 2026 |
| Direct Lending Origination (Q2 2026) | $33.6 billion | $74.7 billion (Q1 2026) | ▼ -55% QoQ | PitchBook/LCD via Angel Investors Network |
| Proskauer Private Credit Default Index (Q1 2026) | 2.73% | 1.84% (Q3 2025) | ▲ Rising | Proskauer via Forbes, May 2026 |
| Fitch Broad Default Rate (ttm to Jan 2026) | 5.8% | <2% (headline rate) | ▲ Materially higher when restructurings included | Fitch Ratings via Forbes, May 2026 |
| Typical Leverage Covenant (Direct Lending) | Max ~4x EBITDA | 4.5–5.5x (2021–2022 vintage) | ▼ Tightening | Investing.com / PitchBook, Aug 2026 |
The data reveals a critical divergence: investment-grade spreads sit at 81 bps and high-yield spreads at 266 bps as of September 2026, both in the bottom decile of historical ranges, offering minimal compensation for credit risk relative to private credit. Private credit, by contrast, has repriced upward, restoring an illiquidity premium that had compressed sharply in 2024–2025. Spreads have widened by roughly 50 to 100 basis points since late 2025, while defensive terms have also improved, according to PitchBook. For operators managing debt-laden balance sheets, the critical KPI threshold shifts: with maximum leverage covenants tightening toward 4x EBITDA and minimum interest coverage requirements near 2.5x, FCCRs below 1.3x will increasingly attract lender scrutiny or outright exclusion from primary deal flow.
Sector Analysis: Where Capital Is Flowing, and Where It Is Retreating
🟢 Healthcare: Durable Lender Appetite, Premium Spreads Intact
Healthcare led private credit activity last year, accounting for 19% of all 2025 direct lending deals, and was the only major industry not to see significant year-over-year price tightening, with spreads landing at an average of approximately SOFR+500 bps in Q4 2025, according to Octus data. In healthcare, demographic shifts and non-cyclical service models continue to attract lenders seeking stable cash flows. For operators in this sector, credit access remains robust, but lenders are now applying tighter FCCR floors (typically 1.25x–1.35x) to account for rising labor costs and reimbursement uncertainty.
🔴 Software & Technology: Capital Retreat Accelerates
No sector has been more severely repriced. Performance in the software sector remains notably weaker, with secondary spreads approximately 245 basis points wider than year-end levels and roughly 229 basis points above the broader B-rated loan index, based on PitchBook LCD data as of June 2026, reflecting continued uncertainty related to AI-driven disruption. Many lenders continue to adopt a more cautious stance toward the sector, with some remaining risk-off, others already overexposed to software and technology, and many limiting incremental exposure amid ongoing uncertainty in borrower performance. Morgan Stanley projected direct lending default rates could climb to 8% as advances in AI continually disrupt the software industry, noting that elevated leverage and looming maturity walls within the sector may push default rates near peak levels unseen since the pandemic.
🟡 Infrastructure, ABF, and Industrials: The New Frontier for Capital
The most decisive structural shift in 2026 is the rotation from corporate direct lending toward asset-backed and infrastructure strategies. Direct lending’s share of private debt fundraising fell from 58.4% in 2024 to 31% by Q1 2026, with capital flowing into infrastructure debt, real estate credit, special situations, and other asset-backed opportunities, according to PitchBook data cited by Wellington. In 2025, KKR raised $6.5 billion for its Asset-Based Finance Partners II, the second-largest ABF fund ever, while specialty finance was the most popular strategy for new private credit launches (84 funds), ahead of direct lending (71). The market for asset-based finance (lending secured by diversified portfolios of cash-flowing assets such as mortgages, corporate and consumer loans, and equipment finance) is viewed as a $28 trillion addressable market ranging from private assets to investment-grade rated securities.
Bank Lending Standards: Stable at the Surface, Tighter Underneath
The July 2026 SLOOS reported that survey respondents reported, on balance, basically unchanged standards for commercial and industrial (C&I) loans to firms of all sizes over Q2 2026. However, this headline masks an important bifurcation: for C&I loans, banks reported that the current level of standards is easier than the midpoint of their historic ranges, while demand for loans from large firms is recovering faster. About 16% of banks cited stronger demand for C&I loans from large businesses; that figure was just 4% for small firms. Importantly, banks reported, on net, tighter standards for all categories of non-depository financial institution (NDFI) loans over the past year, with significant net shares tightening standards for loans to business credit intermediaries and consumer credit intermediaries. This constrains the back-end funding that many private credit funds rely on to lever their own balance sheets.
Implications: What This Means for Borrowers, Lenders, and Operators
For Borrowers and Operators
The era of covenant-lite, high-leverage financing is over for the current cycle. With rising interest expense consuming 30–40% of operating income in heavily leveraged deals, and interest coverage ratios having declined materially per multiple 2026 industry assessments, operators must prioritize EBITDA generation and free cash flow conversion with fresh urgency. Companies carrying net leverage above 4x EBITDA face a shrinking pool of willing lenders; those with FCCRs below 1.25x will encounter significantly tighter terms or be pushed to alternative structures including PIK components, which carry their own compounding risk. Payment-in-kind (PIK) usage has risen notably in private credit, with public BDCs now receiving an average of 8% of investment income via PIK, signaling that this mechanism is increasingly a symptom of stress rather than a structuring preference.
Operators in healthcare, industrials, and infrastructure-adjacent businesses (particularly those with recurring revenues and demonstrable FCCR coverage) are best positioned to access credit on favorable terms. Borrowers in software and consumer products should anticipate 200+ bps in additional spread and far more demanding covenant packages. Nearly $1 trillion in U.S. corporate debt is set to mature between 2026 and 2028, much of which was underwritten during the low-rate era of 2020–2022, creating acute refinancing risk for companies that cannot demonstrate improved credit profiles.
For Institutional Investors and Lenders
The second half of 2026 is likely to be defined by dispersion. Investors should focus less on broad asset-class headlines and more on where managers are lending, how loans are structured, how much free cash flow borrowers generate, and whether portfolios have the right balance of income, downside mitigation, and selectivity. Many long-term allocators, including pension plans and insurers, continue to increase exposure to private credit, attracted by the asset class’s combination of income generation, diversification benefits, and historically attractive risk-adjusted returns in a higher-rate environment.
The FSB’s May 2026 report is a structural warning that cannot be dismissed. The FSB identified four vulnerability clusters in private credit: bank interconnections, borrower credit quality and valuation opacity, concentration and liquidity mismatches, and data gaps. Banks carry $220 billion in official credit line exposure to private credit funds, while commercial estimates put that number between $270 billion and $500 billion, a gap of up to $280 billion that regulators cannot currently reconcile. Institutional allocators to semi-liquid vehicles should stress-test redemption gate mechanics, particularly after deal flow remained light in Q2 2026, with ongoing investor redemption pressures at several non-traded BDCs and fresh warnings about portfolio concentration risks, per PitchBook.
Forward View: Liquidity and Lending Dynamics, Next 3 to 6 Months
Market expectations continue to reflect a higher-for-longer rate environment, with the forward curve broadly flat as of June 2026. This removes a key tailwind that borrowers were anticipating, the reprieve of meaningful rate cuts. Middle market private equity activity has shown signs of improvement, with deal value increasing approximately 10.7% year-over-year and exit activity rising 14% over the same period, according to PitchBook data, suggesting the M&A engine is starting to turn over. However, loan origination fell to $33.6 billion in Q2 2026 from $74.7 billion in Q1, with deal count dropping to 154 completed transactions in Q2, down from 217 in Q1, the weakest quarter for lending activity since Q2 2023.
The structural rotation toward asset-based finance will intensify. Moody’s sees AUM exceeding $2 trillion in 2026 and approaching $4 trillion by 2030, with investing shifting from a corporate lending focus to the ABF market. Partnerships between private credit and banks are becoming more prevalent as private credit continues to move into areas traditionally dominated by banks. For operators, this means the most creative financing solutions in H2 2026 and into 2027 will be found in bespoke, asset-secured structures rather than in plain-vanilla unitranche arrangements. The managers who can originate, underwrite, and service across corporate, ABF, and infrastructure credit will define the next phase of the market.
Key Market Insights
- Spreads have reset upward: Middle market private credit is pricing at SOFR+500 bps, up from the mid-400s, while unitranche coupons are 25 bps wider than year-end 2025. Lenders, not borrowers, now hold pricing power for the first time since 2022.
- True default risk is materially higher than headlines suggest: Fitch’s broad methodology pegs the U.S. private credit default rate at 5.8% (12 months to January 2026), versus the sub-2% headline figure. Operators with deteriorating FCCRs and covenant violations should expect accelerated lender engagement, not forbearance.
- Deal origination collapsed in Q2 2026: A 55% QoQ drop in loan origination to $33.6 billion and a deal count of just 154 transactions signal that lenders are choosing discipline over deployment. Borrowers with weak credit profiles will find the window to refinance or access growth capital narrowing.
- Capital is rotating decisively into asset-based finance and infrastructure: Direct lending’s share of private debt fundraising has fallen from 58.4% (2024) to 31% (Q1 2026). Healthcare, infrastructure, and ABF strategies are absorbing the displaced capital, offering investors collateral-backed returns with tighter structural protections.
- Regulatory risk is no longer theoretical: The FSB’s May 2026 vulnerability report, tighter bank NDFI lending standards per the April SLOOS, and the Fed’s formal queries on bank exposures to private credit funds signal a tightening supervisory environment. Institutional allocators should audit redemption terms, valuation methodologies, and fund-level leverage before committing incremental capital.


