
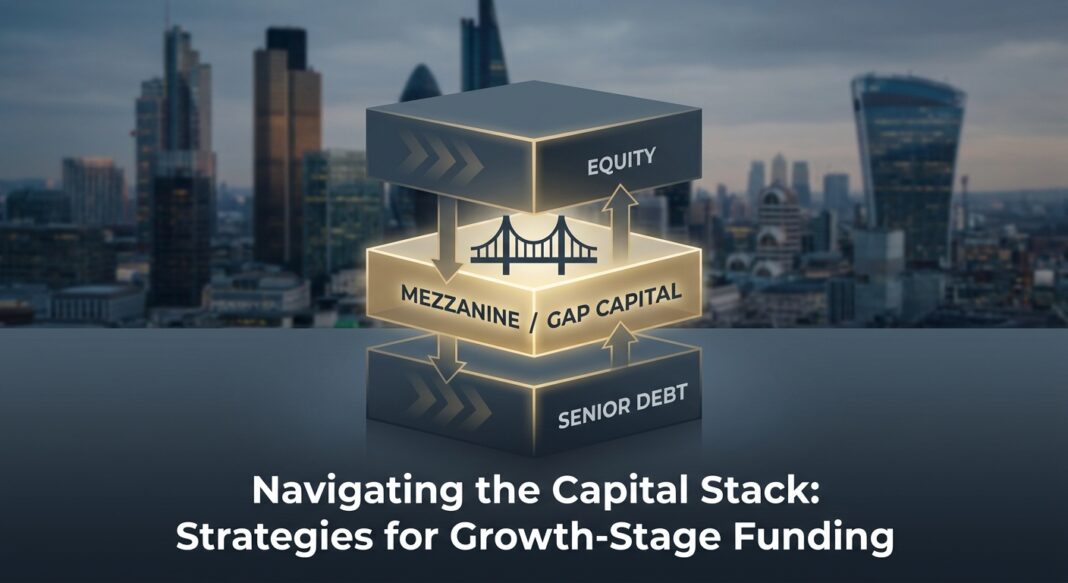
The Gap Between What Banks Will Lend and What the Deal Requires
A growth-stage operator has found the target: a profitable services business trading at 6.0× EBITDA, with $4 million in trailing earnings and a clean balance sheet. The purchase price is $24 million. The company’s bank, a relationship lender with a tight credit committee, will underwrite 3.0× EBITDA, producing $12 million in senior debt. The operator can deploy $6 million in equity without losing operational flexibility. That leaves a $6 million structural hole sitting between the senior loan and the equity check.
This is the gap. And this is where mezzanine financing lives.
The gap is not a failure of preparation. It is a structural feature of acquisition finance. Senior lenders price for first-priority recovery and cap leverage accordingly. Equity investors price for control or high-return minority positions. Neither instrument is designed to occupy the middle of the stack. Mezzanine debt (subordinated, partially PIK-accruing, warrant-bearing) is. Understanding how to navigate this layer: how to size it, price it, document it, and negotiate it, is one of the highest-leverage skills a growth-stage operator can develop.
The Capital Stack: Layer by Layer
A growth-stage acquisition capital stack typically comprises three to four distinct layers. Each carries a different cost of capital, a different structural expectation, and a different risk tolerance. The hierarchy, moving from most senior to most junior, is as follows:
Layer 1: Senior Secured Debt
The cheapest layer in cash-pay terms. Senior secured debt (whether from a bank or a direct lender) holds first priority on collateral, is priced at SOFR plus 250–450 basis points for bank facilities or SOFR plus 500–700 basis points for direct lending, and is typically sized at 2.5×–4.0× EBITDA depending on business quality and sector. Senior lenders set the floor and the ceiling for everything below them. Their credit decision defines the gap.
Layer 2: Mezzanine / Subordinated Debt (The Gap Capital Layer)
Mezzanine debt is a hybrid form of capital that combines features of both debt and equity financing, a funding bridge that fills the gap between the amount a traditional bank will lend and the firm’s existing equity base.
Mezzanine debt has three defining structural features that distinguish it from senior debt: its subordinated and unsecured position, its option for Payment-in-Kind (PIK) interest, and its equity kicker, almost always in the form of stock warrants.
In 2026, the all-in cost of mezzanine is not a single number; it has three components:
- Cash Coupon: A typical 2026 mezzanine debt financing rate for a healthy $5M–$15M EBITDA lower-middle-market company runs 11%–14% cash coupon.
- PIK Interest: With PIK interest, the borrower does not pay cash right away: instead, the interest amount is added to the total loan balance, causing the principal to grow over time. PIK layers of 1%–4% are standard on current LMM mezzanine deals.
- Equity Kicker (Warrants): A warrant is a security that gives the holder the right to purchase a company’s stock at a set price in the future. In mezzanine financing, warrants act as an equity kicker, letting lenders share in the company’s upside if it grows. Warrant coverage of roughly 1%–5% of fully diluted equity is typical.
Mezzanine debt combines a fixed cash coupon with an equity kicker so the fund earns a blended 15%–20% IRR. That blended return target is the structural reason mezzanine providers accept a subordinated lien position.
Layer 3: Preferred Equity or Seller Notes
Preferred equity or seller notes function as a bridge layer used when the debt stack is fully stretched but an equity check would be prohibitively dilutive. Seller notes, in particular, are negotiated instruments that carry no cash covenant burden and can be subordinated behind both senior debt and mezzanine.
Layer 4: Common Equity
The operator’s own capital. Its purpose is not simply to fund the deal; it signals skin-in-the-game to every lender above it in the stack. Mezz providers typically require a minimum equity contribution of 25%–35% of total sources to confirm alignment of interest.
Worked Example: $24M Acquisition, $4M EBITDA Business
| Capital Layer | Amount | Multiple | Pricing |
|---|---|---|---|
| Senior Bank Debt | $12M | 3.0× EBITDA | SOFR + 300 bps |
| Mezzanine Debt | $6M | 1.5× EBITDA | 12% cash + 2% PIK + 3% warrant coverage |
| Operator Equity | $6M | – | 25% of total purchase price |
| Total Sources | $24M | 6.0× EBITDA | WACC ≈ 10.1% (excl. warrant dilution) |
Mezzanine vs. the Alternatives: A Structural Trade-Off Matrix
Mezzanine does not exist in a vacuum. Three alternatives occupy adjacent positions on the capital stack, and the choice between them is a cost-of-constraint and cost-of-dilution calculation, not simply a rate comparison.
Mezzanine vs. Unitranche
For acquisitions in the $25M–$200M enterprise value range where a single financing instrument can cover the full debt quantum, the unitranche is frequently the cleaner structure. Unitranche removes syndication risk that used to blow up 5%–10% of deals in volatile markets, and term sheets typically arrive in 2–3 weeks with closing in 60–75 days from LOI, versus 90–120 days for a syndicated deal. Current spreads in the middle market run approximately SOFR + 4.75% to SOFR + 5.50% for deals in the $40M–$100M EBITDA range, according to Lincoln International’s Q1 2026 private market data. Where the unitranche falls short is leverage ceiling: the typical debt structure in 2026 for a $50M–$500M EV platform buyout is a 4.0×–5.5× total leverage unitranche sized off adjusted EBITDA. When a deal requires total leverage exceeding that ceiling, mezzanine fills what the unitranche cannot.
Traditional senior-plus-mezzanine can achieve a lower weighted cost of capital if mezz carries equity kickers, but intercreditor complexity slows execution and reduces flexibility. The operator must weigh execution speed against structural cost.
Mezzanine vs. Growth Equity
A growth equity investor will write the same-size check that a mezz fund writes, but will demand a priced equity stake rather than a warrant position. Borrowers often choose mezzanine financing when they want to keep the instrument classified as debt; that structure preserves tax-deductible interest and limits dilution to the warrant component. The meaningful risk: when borrowers elect PIK interest, the outstanding balance compounds, increasing the total debt burden. If the anticipated liquidity event is delayed, the growing PIK balance creates a larger refinancing burden at bullet maturity.
Mezzanine vs. Seller Notes
Seller notes are cheaper on paper, typically 5%–8% cash interest, but require seller willingness, often subordination provisions that senior lenders must approve, and a seller who remains economically invested in the business’s performance. For arms-length acquisitions, institutional mezzanine is the more reliable execution path.
Current Market Terms: What Mezzanine Looks Like in 2026
The mezzanine market has tightened from its 2024 rate peaks as senior credit spreads compressed through early 2026, but the structure remains substantively unchanged. Here are five benchmarks that define the current landscape:
- All-in pricing: Mezzanine debt prices at an all-in yield of 13%–17% in 2026, structured as an 11%–14% cash coupon plus 2%–4% PIK, and typically includes 1%–5% equity warrants.
- Target IRR for mezz funds: A blended cost of capital of 15%–18% is normal for mezz plus warrants; the equity kicker is the reason funds accept a subordinated position without a board vote.
- Covenant drift toward cov-lite: Proskauer’s Private Credit Insights Report found that cov-lite deals rose to 21% of private credit transactions in 2025, up from just 4% in 2023. For mezzanine specifically, covenant packages are negotiated, some mezz providers accept incurrence-only covenants; others require maintenance tests.
- Covenant design divergence by size: Covenant use shifts with borrower size, maintenance covenants are more prevalent with smaller borrowers, while incurrence covenants are the primary guardrails as companies grow.
- PIK structuring norms: Effective PIK structures include carefully tailored triggers that constrain or condition PIK elections: performance-based triggers might require a minimum liquidity threshold, a maximum leverage ratio, or positive free cash flow before permitting cash-pay toggling; alternatively, time-based triggers may allow PIK for an initial period, with a step-down to partial cash-pay thereafter.
One structural risk worth flagging for borrowers: if the borrower elects to prepay the mezzanine instrument, the agreement should clarify whether make-whole or call protection applies to both the debt and the warrant value, and how capitalized PIK is factored into any premium calculation, failure to define these aspects with specificity is a frequent source of post-closing disputes, especially when the company outperforms and the equity kicker becomes valuable.
The Gap Capital Playbook: Quantify, Prepare, Run the Process, Negotiate
Step 1: Quantify the Gap Precisely
Before approaching any provider, construct a precise sources-and-uses schedule mapping every dollar from capital sources to closing requirements: purchase price, debt payoff, transaction fees, financing fees, working capital reserve, and integration costs. Providers underwrite the complete picture. A schedule with gaps signals preparation failure and undermines negotiating credibility. The mezzanine quantum is what remains after the senior debt ceiling and the equity contribution are locked in. Size it explicitly, not residually.
Step 2: Prepare the Provider Package
Mezzanine funds underwrite to exit; they model the equity kicker’s value at an assumed exit multiple in year five or six. The materials package must therefore include not just trailing EBITDA but a credible growth bridge. Providers will independently stress-test the model; operators who provide the stress case first, rather than waiting to be asked, signal analytical credibility. Required materials: three years of audited financials, trailing-twelve-month management accounts, an LTM-to-forward bridge, the sources-and-uses table, a proforma debt service schedule showing both cash-pay and PIK layers, and a brief on the exit hypothesis.
Step 3: Run a Competitive Process
Approach four to six mezzanine providers simultaneously. Issue a structured term sheet request with a defined response window of 10–15 business days. Require each provider to specify their proposed all-in pricing, PIK vs. cash-pay split, warrant coverage percentage, and covenant package type. A competitive process does not only produce better pricing; it produces information. Variance in warrant coverage demands and covenant requirements across responses tells the operator precisely where the market prices the transaction’s risk.
Step 4: Evaluate Total Cost of Constraint, Not Just Coupon
The most common structuring error is optimizing for the lowest cash coupon without accounting for covenant restrictiveness. A 12% coupon with a leverage maintenance covenant tested quarterly is materially more constraining than a 13% coupon with incurrence-only covenants. Incurrence covenants only test the ratio when the borrower takes an affirmative action (issuing new debt, making an acquisition, or paying a dividend) meaning a borrower can operate without triggering lender intervention rights even when financials deteriorate. For a growth-stage company planning add-on acquisitions, the covenant architecture is the most consequential term in the document, not the spread.
Negotiation Guidance: Key Points to Influence Before Signing
Mezz term sheets contain five high-leverage negotiation points that operators frequently underweight:
- Warrant strike price and anti-dilution provisions. Push for a strike price at or near the closing equity value, with standard weighted-average anti-dilution protection rather than full-ratchet provisions. The valuation at which equity kickers convert is a critical aspect; it can be set at the time of the loan or determined by a future valuation event.
- PIK toggle mechanics. Negotiate the right to toggle between cash-pay and PIK based on liquidity metrics you control, rather than at lender discretion. Performance-based triggers might require a minimum liquidity threshold or a maximum leverage ratio before permitting cash-pay toggling.
- Call protection schedule. Standard mezz call protection runs 105/104/103/102/101 over five years. Operators with high confidence in a near-term refinancing or exit should push for a shorter no-call window, 24 months instead of 36.
- Incremental debt basket. Future add-on acquisitions require incremental debt capacity. Negotiate a defined incremental facility basket with a leverage test measured on a pro forma basis so the mezz document does not become a structural block on the growth strategy.
- Information rights vs. board observation rights. Most institutional mezz funds will seek board observer rights. This is negotiable. Operators who grant robust quarterly reporting packages (financials, KPI dashboards, and a management discussion letter) can frequently negotiate board observation rights down to a notice requirement rather than a standing seat.
Key Takeaways
- 🔑 The gap is structural, not situational. Senior lenders cap leverage; equity investors price for control. Mezzanine debt is purpose-built to occupy the capital stack layer between them, and every growth-stage acquisition finance should model this layer explicitly from the outset.
- 🔑 All-in mezzanine cost has three components. In 2026, a healthy LMM mezzanine facility runs 11%–14% cash coupon plus 1%–4% PIK plus warrant coverage of 1%–5% of fully diluted equity. Evaluating only the cash coupon produces a materially understated cost-of-capital comparison.
- 🔑 Covenant design is the highest-leverage negotiation point. In private credit, covenants serve as functional tools for risk management, maintenance covenants provide early warning signals, and incurrence covenants prevent actions that increase lender risk. For growth-stage operators planning add-on acquisitions, incurrence-only covenants preserve the operational flexibility that maintenance tests foreclose.
- 🔑 PIK compounds leverage, model it forward. When borrowers elect PIK interest, the outstanding balance compounds, increasing the total debt burden. If the anticipated liquidity event is delayed, the growing PIK balance creates a larger refinancing burden at bullet maturity. PIK is a cash-flow tool, not a free lunch; model the compounding effect out to year five before electing it.
- 🔑 Run a structured, competitive process. Approaching four to six providers simultaneously with a standardised term sheet request produces both better economics and market intelligence. Variance in responses (particularly on warrant coverage and covenant requirements) is diagnostic data on how the market prices your specific credit profile.


