
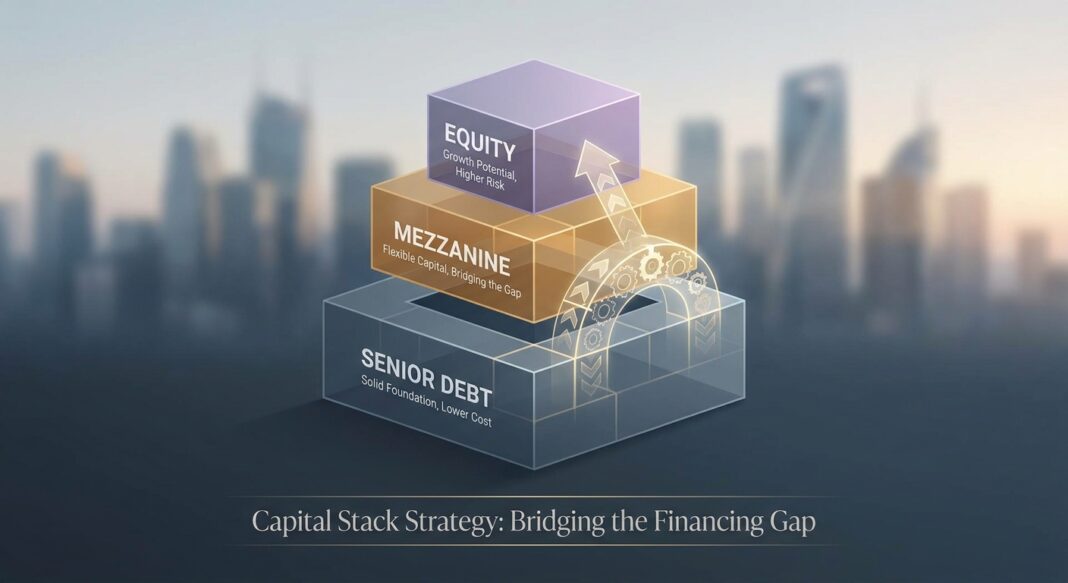
Growth-Stage Acquisition Financing: How to Map the Capital Stack from Senior Debt to Mezzanine and Close the Gap
The Financing Challenge at the Growth Stage
A growth-stage operator sitting at $8M–$15M in EBITDA faces a structurally awkward moment when it wants to make its first material acquisition. The business is too large and too cash-generative for venture instruments, but not yet seasoned enough in leverage history or asset depth to satisfy a bank’s full appetite. The result is a financing gap: the delta between what a senior lender will comfortably advance and the total capital required to close the deal.
This gap is not a niche problem. It sits at the centre of nearly every lower-middle-market (“LMM”) and growth-stage acquisition in 2026. The decision the operator must make is not simply “debt or equity?” It is a more precise question: which combination of instruments, at which layer of the capital stack, produces the lowest blended cost of capital while preserving the optionality and operational control the business needs to execute the acquisition thesis?
Answering that question requires a clear-eyed map of the cost-of-capital spectrum, an honest assessment of leverage capacity at each layer, and a disciplined process for preparing, running, and closing the financing. That is what this article provides.
The Cost-of-Capital Spectrum: Banks to Equity
Every acquisition financing decision is fundamentally a trade-off between cost and access. The spectrum runs, from cheapest to most expensive, as follows:
| Layer | Instrument | Typical Leverage Ceiling | All-In Cost (2026) | Key Constraint |
|---|---|---|---|---|
| 1st Lien Senior | Bank term loan / revolver | 3.0x–4.0x EBITDA | 7.5%–9.5% | Requires hard collateral; amortisation; maintenance covenants |
| Unitranche | Single-lender private credit | 4.0x–5.5x EBITDA | ~10.2% (median, $5M–$50M facilities, S&P LCD, June 2026) | Speed premium over bank; single covenant; no syndication |
| Mezzanine | Subordinated debt + equity kicker | 5.5x–7.0x EBITDA (blended) | 10%–14% cash + PIK; 16%–22% total IRR | Warrant dilution; bullet maturity; intercreditor complexity |
| Preferred Equity | Participating or convertible preferred | N/A (equity-treated) | 12%–18% dividend + participation rights | Board rights; liquidation preference stacking |
| Common / Sponsor Equity | PE fund cheque / founder rollover | N/A | 20%–30%+ target IRR | Most expensive; permanent dilution |
Sources: S&P LCD US Loan Comparable Data (June 2026) via Bond Capital; Capstone Partners Winter 2025 Leveraged Finance Report; GF Data H1 2026.
The strategic insight is straightforward: each incremental dollar of senior debt is the cheapest dollar in the stack. Every dollar of equity is the most expensive. The operator’s job is to push leverage as far up the capital structure as the business can credibly service, and no further.
Structure Breakdown: A $60M Acquisition at a $10M EBITDA Growth Business
Consider a concrete scenario: a B2B software-enabled services company generating $10M in EBITDA wants to acquire a complementary platform for $60M (6.0x EBITDA on the target). The acquirer has $5M of its own equity to contribute. Here is how the capital stack assembles:
Layer 1: Unitranche Facility, $42M (4.2x acquirer EBITDA)
The first port of call is a direct lending unitranche. Rather than splitting senior and subordinated tranches across multiple lenders, a single private credit fund advances a blended facility. The borrower sees one rate, one set of covenants, and one counterparty.
- Structure: $42M unitranche (SOFR + 450–500 bps, approximately 10.0%–10.5% all-in), 6-year tenor, minimal amortisation (1% per annum), bullet at maturity
- Leverage test: Total net leverage ≤5.25x at close, stepping to ≤4.75x by year 2, a single maintenance covenant tested quarterly
- Execution: Closes in 45–90 days from mandate; single credit committee approval
- Inside the wire: The lender may sub-allocate first-out / last-out tranches to co-investors via an Agreement Among Lenders (“AAL”), a mechanism the borrower never sees but that allows the lead lender to sell down risk post-close
Layer 2: Mezzanine Facility, $13M (filling the gap to $60M)
The unitranche covers $42M. Combined with $5M of equity, the stack still needs $13M to reach the $60M purchase price. This is the textbook mezzanine gap.
- Structure: $13M subordinated term loan, 5-year tenor, bullet at maturity
- Cash coupon: 9.0%–10.0% per annum, paid quarterly
- PIK toggle: 2.5%–3.5% PIK option for years 1–2, converting to full cash pay in year 3 (preserves liquidity during integration)
- Equity kicker: Warrants covering 3%–5% of diluted equity at the current valuation, exercisable at a nominal strike price on exit or IPO
- Intercreditor agreement: Payment blockage provisions; standstill of 120–180 days on enforcement; senior lender approval required for any mezzanine acceleration
Layer 3: Sponsor / Founder Equity, $5M
The equity contribution signals skin-in-the-game to lenders and sets the loan-to-value starting point. In sponsor-backed deals, this layer is larger; in founder-led acquisitions, rollover equity from the seller can substitute for a portion of the cash equity requirement.
Blended Cost of Capital
On the $55M of debt, the blended all-in cost approximates 10.5%–11.0% before the warrant dilution from the mezzanine layer. With warrant coverage at 4% of equity, the fully-loaded cost of the mezzanine tranche rises to a 17%–20% effective IRR for the mezz investor, an expensive but non-dilutive-at-inception instrument that avoids a priced equity round and the valuation anchor that comes with it.
Unitranche vs. Senior + Mezzanine: When Each Structure Wins
When Unitranche Dominates
The unitranche has become the standard structure for sponsored middle-market acquisitions. The structural simplicity is its core advantage: a single credit agreement, a single lender relationship, and a single covenant package. For repeat acquirers running roll-up platforms, this matters. Managing add-on financings, covenant modifications, and incremental draws across two lender groups introduces execution risk that compounds with deal frequency.
The speed premium is real and quantifiable. Unitranche financing can close in 45–90 days versus 90–150 days for a traditional senior-plus-mezzanine syndication. For a buyer in a competitive auction process, that timeline advantage can determine whether a deal is won or lost.
The pricing premium is also real. Unitranche spreads run 100–150 basis points above comparable syndicated senior loans, a cost that sponsors routinely absorb to eliminate financing-gap risk and broken-deal liability.
When Senior + Mezzanine Makes Sense
When leverage requirements exceed what a single unitranche provider will deploy, typically above 5.0x–5.5x for most LMM credits, the traditional split structure re-emerges as a necessity rather than a preference. The senior lender advances to its comfort ceiling; the mezzanine provider fills the residual gap. The blended cost can be marginally cheaper than a stretched unitranche, but the execution complexity, intercreditor negotiations, and extended timeline erode much of that savings in practice.
The senior/mezz split also makes sense when the operator wants PIK optionality on the subordinated layer. Pure unitranche structures rarely permit PIK interest; mezzanine instruments are designed around it. For a business entering an integration period where near-term cash generation may be constrained, the PIK toggle on the junior tranche is not a luxury; it is a liquidity management tool.
The Equity Kicker Trade-Off
The mezzanine warrant is the instrument’s defining feature and its sharpest negotiating point. Warrants typically cover 3%–8% of diluted equity and are struck at or near the current equity valuation. They are not permanent dilution (they are contingent dilution, exercised only on a liquidity event) but they reset the cap table at exit and can meaningfully reduce founder or sponsor proceeds in a high-multiple outcome. Operators should model warrant dilution at both a base-case and upside exit multiple before accepting a mezz term sheet.
Current Market Terms & Standards (2026)
The following data points are drawn from current market sources and reflect the LMM and growth-stage acquisition financing environment as of mid-2026:
- Unitranche all-in pricing ($5M–$50M facilities): Median all-in coupons on unitranche facilities in the $5M–$50M band are clearing at approximately 10.2% as of June 2026, per S&P LCD US Loan Comparable Data. Upper middle-market credits (SOFR + 425–475 bps) price 50–100 bps tighter than core middle-market credits per Capstone Partners’ Winter 2025 Leveraged Finance Report.
- Mezzanine cost structure (2026): The all-in cost of mezzanine runs 10%–14%, composed of a cash coupon of 8%–11% plus PIK of 2%–4% plus warrant coverage. At a total IRR of 16%–22% including the equity component, mezzanine is expensive on a cost basis but avoids the permanent dilution of a priced equity round.
- Leverage multiples: Senior bank loans are typically limited to 3.0x–4.0x leverage, while unitranche facilities reach 4.0x–5.5x for quality recurring-revenue businesses. A typical $50M enterprise value LMM platform in 2026 was funded with roughly 40% senior debt, 10% mezzanine, 45% sponsor equity, and 5% seller rollover, per GF Data H1 2026 averages.
- Covenant standards (private credit): In the broadly syndicated loan market, approximately 90% of new large-cap loans in 2024 remained covenant-lite (incurrence-only), per PitchBook LCD. Private credit lenders, by contrast, have maintained firmer positions on maintenance covenants for mid-market transactions. The share of private credit lenders requiring at least one financial maintenance covenant grew significantly in 2025–2026, with a single total net leverage test (typically 25%–35% cushion over base case) remaining the standard structure. For borrowers, this is not just documentation; it determines when a lender can intervene and how much operational flexibility the business retains between test dates.
- Private credit scale: Global private credit assets under management reached approximately $2.1 trillion in 2025. Unitranche financings now represent approximately 30% of sponsored middle-market transactions, with private credit controlling over 50% market share in sponsored transactions overall, per market estimates cited in ABF Journal (August 2025).
The Gap Capital Playbook: Quantify, Prepare, Run, Negotiate
Step 1: Quantify the Gap Before Approaching Any Lender
The single most common error growth-stage operators make in acquisition financing is approaching lenders without a fully mapped capital stack. Lenders do not fund ambiguity. Before the first call, the operator must know: (a) total acquisition consideration including fees and working capital adjustments; (b) senior debt capacity at 3.0x–4.5x of combined EBITDA post-acquisition; (c) the residual gap between (a) and (b) after adding sponsor equity; and (d) the cash flow available to service each layer on a stressed basis. The mezzanine or unitranche size should be a precise number derived from this analysis, not a reflexive plug.
Step 2: Prepare Materials That Speak to Each Layer’s Risk Lens
Senior lenders underwrite to downside collateral and coverage. Mezzanine investors underwrite to cash flow trajectory and equity upside. The same management presentation cannot serve both audiences equally. Prepare a lender-specific financial model that clearly shows: (1) sources and uses with leverage multiples at each layer; (2) interest coverage on a cash-pay and PIK basis under base, downside, and stress scenarios; (3) the integrated EBITDA bridge post-acquisition; and (4) an explicit exit analysis showing mezzanine warrant exercise proceeds at 2.0x–4.0x multiple of invested capital scenarios.
Step 3: Run a Parallel, Competitive Process
Do not run senior and mezzanine processes sequentially. Engage both layers simultaneously, even if the mezzanine commitment is conditioned on senior close. Competition within each layer is the primary lever for improving terms. For mezzanine, three to five term sheets is sufficient; more creates complexity without meaningful incremental price discovery. Mandate letters should include a market flex provision: understanding how far each lender will move on rate, PIK split, and warrant coverage under pressure is essential intelligence before signing.
Step 4: Negotiate the Intercreditor Agreement with as Much Attention as the Loan Documents
In a senior + mezzanine structure, the intercreditor agreement governs what happens when things go wrong. The key negotiating points for the operator are: (a) minimising the payment blockage period (push for 120 days vs. the standard 180); (b) ensuring the mezzanine lender cannot independently accelerate without senior consent; and (c) preserving the right to cure a senior maintenance covenant breach without triggering mezzanine default cross-default provisions. These points are rarely lead items in term sheet negotiations, but they define the practical control dynamics of the business in any distress scenario.
Structuring Guidance: For Operators and Investors
For Operators
- Model the covenant with a 35% cushion, not 25%. Lenders set covenants at a 25%–35% initial headroom over the base case. If your model is optimistic (and every management model is) that cushion closes faster than expected. Build the covenant test into your financial model before accepting the term sheet, not after.
- PIK is not free money. A PIK toggle preserves cash in the near term but compounds the debt burden at maturity. Model the PIK accrual in full at the outset and stress-test the maturity refinancing at a rate 200 bps higher than today’s market.
- Negotiate warrant coverage on fully-diluted shares, not authorised shares. The difference between 3% of issued-and-outstanding and 3% of fully-diluted (including options and convertibles) can be substantial in a capital-efficient tech or services company. Lock the denominator at signing.
For Investors and Lenders
- The covenant package is a monitoring tool, not just a legal protection. Maintenance covenants tested quarterly allow lenders to intervene while corrective action is still viable. Research confirms that restructurings initiated at the covenant-breach stage, before a payment default, produce materially higher recoveries than those triggered by missed payments. Do not trade away this early-warning mechanism for deal volume.
- Underwrite the intercreditor agreement as carefully as the credit. In any multi-lender structure, the intercreditor determines actual recovery outcomes. Understand the standstill obligations, the buy-out right mechanics, and the enforcement waterfall before committing capital.
- Warrant coverage should reflect risk, not convention. A 3% warrant on a stable cash flow business is not the same as a 3% warrant on a high-growth SaaS platform with uncertain exit timing. Price the kicker relative to equity volatility and expected exit horizon, not as a reflexive percentage of loan size.
Key Takeaways
- Map the gap first. Quantify the delta between senior debt capacity (3.0x–4.5x EBITDA) and total capital required before approaching any lender. The mezzanine or unitranche size must be a precise, model-derived figure, not a residual estimate.
- Unitranche dominates the $25M–$200M EV acquisition market because it offers execution certainty and speed (45–90 days to close) at a modest cost premium over traditional senior debt. For roll-up platforms, that speed advantage compounds in value with each add-on.
- Mezzanine fills the structural gap above unitranche leverage ceilings. Its PIK toggle is a genuine liquidity management tool during integration, but the warrant kicker, typically 3%–8% of diluted equity, must be modelled at exit to understand the true economic cost at different outcome multiples.
- Covenant design shapes control dynamics, not just documentation. Private credit maintenance covenants (single leverage test, 25%–35% initial cushion) give lenders an early-warning mechanism unavailable in covenant-lite syndicated structures. Borrowers should negotiate cushion headroom aggressively; lenders should resist trading it away for deal economics.
- The intercreditor agreement is the most consequential document in a senior + mezzanine structure. Payment blockage periods, cure rights, enforcement standstills, and cross-default provisions determine who controls the business in a distress scenario. Negotiate it with the same rigour as the credit terms themselves.


