
The Growth-Stage Financing Problem: You've Hit the Senior Debt Ceiling
A profitable lower-middle-market business generating $6 million of EBITDA has identified a bolt-on acquisition at a $40 million enterprise value. The operator has been through the bank circuit. Senior secured lenders will extend to approximately 3.5x EBITDA, call it $21 million. The equity on the balance sheet, together with what the sponsor is willing to put in, covers another $10 million. That leaves a $9 million hole sitting exactly between senior debt and equity in the capital structure. This is not a niche problem. It is one of the most common structural challenges in growth-stage acquisition finance.
The instinct is to either over-lever the senior tranche, which creates covenant risk, or issue more equity, which crystallises dilution at precisely the wrong time in the company's growth trajectory. Neither outcome is optimal. The better answer sits in the middle of the capital stack: mezzanine financing. Structured correctly, mezz fills that gap, preserves equity control, and funds the deal at a blended cost that is meaningfully cheaper than handing over equity to a growth investor at a compressed multiple.
This article maps the mechanics, current 2026 market terms, and the negotiation playbook for using mezzanine financing in a growth-stage acquisition context, from quantifying the gap to closing the term sheet.
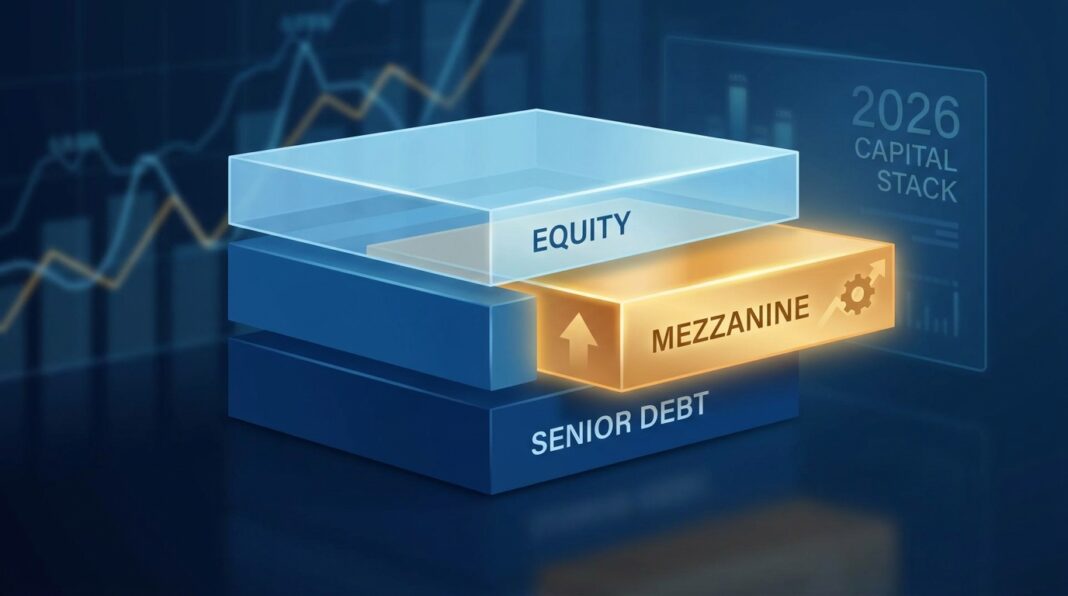
Structure Breakdown: How Mezzanine Fits Into the Capital Stack
Where It Sits
Mezzanine debt is the layer in the capital stack between senior debt and equity, providing two to three turns of additional leverage above senior bank debt at a 12–15% all-in cost. Mezz funds roughly 10% to 20% of the capital stack for a lower-middle-market deal that needs more leverage than senior can provide but less dilution than another turn of equity.
The Three-Part Return Structure
Mezzanine return to the lender comes from three compounding components:
- Cash-Pay Interest: Current coupon paid quarterly. Pricing runs 10% to 12% cash plus 2% to 4% PIK, plus warrants worth 3% to 8% of common equity.
- PIK (Payment-in-Kind) Interest: Interest that accrues into the principal rather than being paid in cash each period, preserving the borrower's near-term free cash flow. Most deals include a mix of cash-pay interest and PIK components, with the PIK portion compounding into principal over time.
- Equity Kickers / Warrants: The true complexity comes from the warrants. These equity kickers can complicate the capital structure, add layers to future financing rounds, and create challenging negotiations in a potential exit scenario. Their purpose is to give the mezz lender common-equity upside if the company is sold or recapitalised at a higher valuation.
Illustrative Term Sheet: $9M Mezz Tranche on a $40M Acquisition
Consider the scenario opened above, a $6M EBITDA operator acquiring a target at $40M enterprise value. The capital stack might look like this:
- Senior Secured Term Loan (1st Lien): $21M at SOFR + 450–550 bps (approx. 9.5–10.5% all-in). As of Q2 2026, senior secured lending for LMM businesses runs SOFR plus 400 to 550 basis points per S&P Global LCD, which puts all-in coupons in the 9% to 10% range.
- Mezzanine Tranche (2nd Lien / Subordinated): $9M. Priced at an all-in yield of 13% to 17% in 2026, comprising an 11% to 14% cash coupon plus 2% to 4% PIK, and typically including 1% to 5% equity warrants.
- Equity (Sponsor + Rollover): $10M. Common equity, last in line but capturing all residual upside.
Per GF Data's Q1 2026 mezzanine report, LMM mezz deals in Q1 2026 closed at a median 12.5% cash coupon, 3.0% PIK, and 2.5% warrant coverage, with a five-year term and typically two years of call protection.
The total leverage stack sits at 5.0x EBITDA, $21M senior (3.5x) plus $9M mezz (1.5x), within a range that experienced mezz lenders accept for a business with durable cash flows. Mezzanine lets an operator push effective debt capacity from the senior-debt cap of roughly 3.5x EBITDA up to a total-debt cap of 4.5x to 5.5x without giving up equity control, because mezzanine is technically debt with a small equity kicker rather than a true equity investment.
Mezzanine loans typically mature in five to seven years, often aligning with expected exit timelines. Repayment is usually structured as a single bullet payment at maturity.
Mezzanine vs. Alternatives: Trade-Offs Across the Capital Spectrum
Vs. Growth Equity
The most direct alternative to mezz is selling equity to a growth investor. The trade-off is a 12% to 15% blended cost of capital via mezz versus 30% or greater dilution cost of equity. For a business growing at 15–20% annually and approaching an exit, issuing common equity at today's valuation locks in permanent dilution on future value creation. Mezz debt extinguishes at maturity; equity does not.
Vs. Unitranche
A unitranche is a single-tranche term loan that combines what would otherwise be a senior secured loan and a subordinated/mezzanine loan into one instrument. From the borrower's perspective, there is one loan document, one lender, one set of covenants, one interest rate, and one prepayment schedule. The unitranche trades simplicity for cost: unitranche is priced at SOFR plus 550 to 700 basis points, streamlining LBO and roll-up financings. If the senior lender relationship is strong and the deal is large enough to warrant the all-in unitranche pricing, it eliminates intercreditor complexity. If the operator already has an existing senior facility they want to preserve, slotting in a mezz tranche is more surgical.
Vs. Traditional Senior + Mezz Syndication
Traditional senior plus mezzanine can achieve a lower weighted cost of capital if mezz carries equity kickers, but intercreditor complexity slows execution and reduces flexibility. For LMM operators running acquisitions on a defined timeline, the additional documentation burden and negotiation time between senior and mezz lenders can be the decisive factor.
When Mezz Wins
Mezzanine is most useful in three scenarios: first, a growth capital raise where the operator wants to fund a large capex or acquisition without giving up equity; second, an LBO where senior debt is capped and the sponsor needs additional non-equity capital; third, a shareholder buyout where the operator wants to buy out a partner without diluting existing equity.
Current Market Terms: What the 2026 Mezz Market Is Pricing
The mezzanine market in 2026 is operating against a private credit backdrop that has reached significant scale. The U.S. private credit market expanded from $500 billion to $1.3 trillion over the last five years and is poised for continued growth in 2026. That competition has tightened spreads at the senior end but left the mezz layer relatively well-compensated given its subordinated position.
Five data points defining the current market:
- Coupon Structure (Q1 2026): LMM mezz deals in Q1 2026 closed at a median 12.5% cash coupon, 3.0% PIK, and 2.5% warrant coverage.
- All-In IRR: Mezzanine debt carries a 12–15% cash plus PIK cost, with a 16–22% all-in IRR when warrant value is included.
- Total Issuance: Total mezz issuance to LMM sponsors in 2025 hit $28.3 billion per S&P LCD, the highest level since 2019.
- Leverage Capacity: Average total leverage in sponsored middle-market unitranche deals hovered around 5.0x EBITDA in mid-2024 as lenders focused on free cash flow and covenant headroom. Dedicated mezz lenders are willing to push to 5.5x in higher-quality, recurring-revenue businesses.
- Covenant Trend: Covenant-lite transactions rose to 21% of direct lending deals in 2025, up from 4% in 2023. However, private credit managers correctly point out that their lower-middle-market books remain covenant-rich, with maintenance covenants retained as the standard in the sub-$25M EBITDA universe. Covenant use shifts with borrower size: maintenance covenants are more prevalent with smaller borrowers, while incurrence covenants are the primary guardrails as companies grow.
On the covenant architecture: maintenance covenants are lender-monitoring tools; incurrence covenants are transaction-gating tools. A well-structured mezz package for an LMM acquisition will carry a maintenance-based leverage covenant tested quarterly, typically net debt-to-EBITDA with 20–25% headroom to the underwritten case, plus incurrence covenants governing additional debt, dividends, and asset sales. In 2024, market caps on pro forma cost-savings add-backs clustered around 25% to 35% of EBITDA, a figure borrowers should scrutinise carefully when negotiating their covenant-testing base.
The Gap Capital Playbook: Quantifying, Preparing, and Running the Process
Step 1: Quantify the Gap
Before approaching any mezz provider, the operator must build a clean sources-and-uses table with the senior debt capacity anchored to the lending bank's actual offer, not a theoretical maximum. The mezz gap is the residual between (total consideration + transaction costs) and (committed senior debt + equity). Size it precisely. Mezz lenders will back-solve to DSCR and free-cash-flow-to-debt-service ratios; entering the process with a pre-stressed model demonstrates underwriting discipline.
Step 2: Prepare the Materials
A mezz raise requires a concise CIM (Confidential Information Memorandum) covering: three years of audited financials, trailing twelve-month management accounts, a bottoms-up EBITDA bridge for the combined entity, a synergy schedule with supporting assumptions, and an exit analysis (strategic buyer multiples or public comps). The warrant coverage negotiation hinges on the equity story, lenders will price kickers to the quality and certainty of exit.
Step 3: Target the Right Lenders
The named mezzanine sponsor universe in the LMM segment includes traditional mezz funds like Audax Private Debt, Main Street Capital, Golub Capital, Churchill Asset Management, and Norwest Mezzanine Partners. Run a focused process with four to six lenders, enough to create competitive tension on pricing without over-distributing sensitive business information. Mezz providers are relationship-driven; a warm introduction through a senior lender or M&A adviser accelerates the diligence clock materially.
Step 4: Structure the Intercreditor Negotiation
The intercreditor agreement between senior and mezz is where execution risk concentrates. Key flashpoints: standstill periods (how long mezz must wait before enforcing on a default), cure rights (can mezz cure a senior covenant breach to protect its position?), and payment blockers (conditions under which mezz interest is suspended). Experienced borrowers negotiate a 180-day standstill maximum and preserve mezz cure rights as non-negotiables.
Negotiation Guidance: What to Fight For and What to Concede
For Borrowers / Operators
The three highest-leverage negotiation points are: (1) Call Protection Window: push for a non-call period of no more than two years with a declining premium thereafter (NC2, then 103, 102, 101 par). Most lenders start at NC3; two years is achievable in a competitive process. (2) Warrant Strike Price and Coverage: negotiate the warrant strike to current or slightly higher than current equity value, and limit coverage to 2.5–3.5% in a strong EBITDA-growth story. Lenders will quote 5–8% on first pass. (3) PIK Toggle Optionality: push for the right to elect PIK interest during a defined period (typically the first 24 months) without triggering a default. This preserves cash flow during the integration phase of an acquisition when EBITDA may temporarily compress.
Private credit lenders have significantly more freedom than banks in that they can evaluate borrowers on a case-by-case basis, offer bespoke loan structures, create flexible covenants, and make relationship-driven lending decisions. For example, a seasonal business might negotiate covenant tests tied to peak sales months rather than uniform quarterly targets. Borrowers should exploit this flexibility explicitly in negotiations, not treat the term sheet as a fixed document.
For Investors / Deal Teams
When reviewing a mezz-supported capital structure, the key diligence focus is cash flow durability at the combined leverage level. The PIK component compounds silently: a 3% PIK on a $9M tranche adds $270,000 to principal in year one alone, growing each year. Model the total debt outstanding at maturity under the base case and a 20% EBITDA stress scenario. If the bullet repayment at year five requires a refinancing exit, stress-test the refinancing market assumptions as well. The financing agreements often come with covenants that can restrict the company's operational and financial flexibility, and those restrictions compound operational risk during integration periods, precisely when management bandwidth is most constrained.
Key Takeaways
- Mezz fills the structural gap. When senior debt capacity is exhausted at 3.5x EBITDA and equity dilution is prohibitive, mezzanine unlocks a further 1.5–2.0x of leverage at a blended cost significantly below growth equity.
- Current 2026 pricing is well-defined. Q1 2026 LMM mezz closed at a median 12.5% cash coupon, 3.0% PIK, and 2.5% warrant coverage, with total all-in IRR for the lender running 16–22% when warrants are exercised.
- The warrant negotiation is the equity conversation. Mezz warrants are dilutive equity instruments embedded in a debt instrument; operators must model their impact on cap table ownership and exit proceeds before signing a term sheet.
- Covenant architecture matters as much as pricing. Maintenance covenants tested quarterly are standard in LMM mezz; borrowers should push for a 20–25% headroom cushion above the underwritten base case and a clearly defined EBITDA add-back cap to prevent ambiguity at covenant-test dates.
- Process discipline determines outcome. A four-to-six-lender competitive process, anchored by clean financial materials and a credible synergy narrative, is the single most effective lever for compressing warrant coverage, extending call protection periods, and winning PIK-toggle optionality.


