
The Growth Stage Capital Challenge
The most dangerous moment in a company’s financial life is not the startup phase, it’s the growth stage. A business generating between $3M and $30M in revenue, with 20%–60% growth and proven unit economics, sits in a structural no-man’s-land: too large for SBA facilities, too small (or too early) for the broadly syndicated loan market, and too operationally complex for vanilla bank credit. Yet this is precisely the moment when capital requirements spike: for a bolt-on acquisition, a geographic expansion, a capex build-out, or a management buyout.
The instinct is often to raise equity. But in the current environment, that instinct is increasingly expensive. According to Carta’s State of Private Markets data, median dilution in 2025 sat at approximately 19.5% for seed rounds and 18% for Series A rounds, and these figures are higher than the 2021 peak, reflecting a market where investors are demanding more ownership for the same risk. Stack dilution across two or three rounds and a founder can enter a Series C holding less than half the company they built.
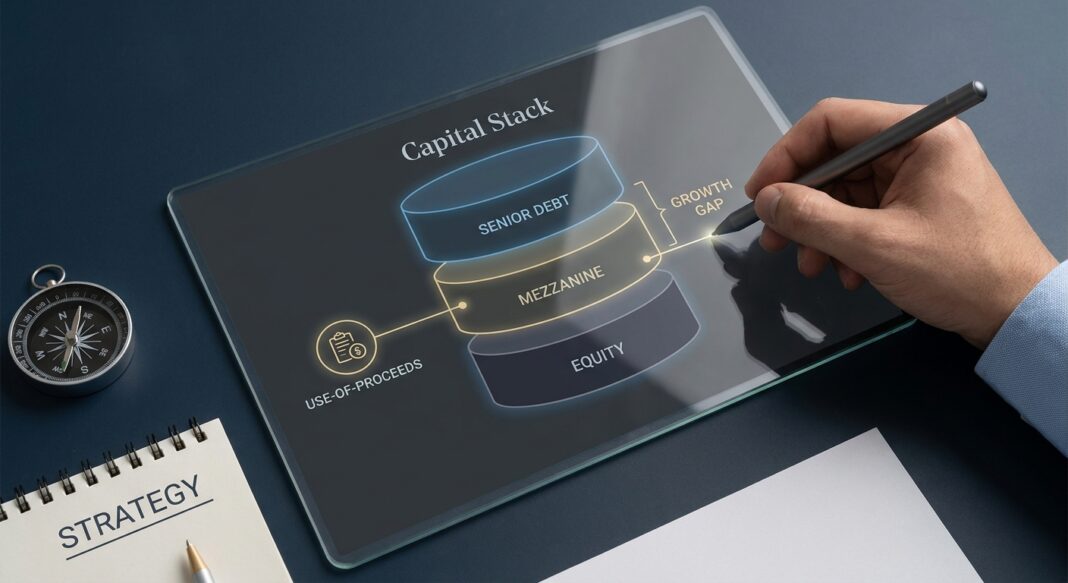
The better framework is this: identify the use-of-proceeds precisely, quantify the capital gap, and match each layer of the stack to the specific purpose, duration, and risk profile of that deployment. Done correctly, a growth-stage operator can fund a $20M–$40M strategic event while holding dilution below 30% and maintaining operational control. This is the Gap Capital Playbook.
The Cost of Capital Spectrum: Banks to Equity
Every structuring decision starts with the same map. Capital is priced by risk: specifically, by seniority, security, and certainty of repayment. Understanding where each instrument sits on that spectrum determines both access and cost.
1. Senior Secured Bank Debt: The Cheapest Layer, With Hard Limits
Commercial bank facilities (revolving credit lines, term loans) remain the lowest-cost form of capital and the cornerstone of private credit infrastructure. Banks typically lend to 3.0x–4.0x EBITDA against hard assets or contracted cash flows and price at SOFR plus 175–325 basis points. The constraint is structural: regulatory capital requirements mean banks will rarely stretch beyond 4x total leverage for middle-market borrowers, and they require the tightest covenant packages. For a growth-stage company with lumpy EBITDA or limited asset coverage, the bank will fill only a portion of the financing need.
2. Direct Lending / Unitranche: The Growth-Stage Workhouse
Unitranche facilities have become the dominant leveraged finance product for middle-market sponsor deals below $500M in total debt. They combine senior and subordinated debt into a single instrument with a single agent, a single credit agreement, and a blended rate. Current 2026 pricing on unitranche facilities in the $5M–$50M band clears at a median all-in coupon of approximately 10.2%, with spreads quoted at SOFR plus 550–750 basis points. For borrowers, the primary benefit is execution certainty: a unitranche can close 30–45 days faster than a syndicated alternative, a speed premium that sponsors often justify at 50–100 basis points of extra spread when avoiding a broken syndication that could jeopardize a purchase agreement.
Importantly, private credit AUM crossed $1.7 trillion in H1 2026, with roughly 40% of new deployment targeting the lower middle-market growth segment. This capital abundance has driven spread compression of approximately 175 basis points from Q1 2024 peaks, a meaningful tailwind for growth-stage borrowers entering the market today.
3. Mezzanine Financing: Bridging the Remaining Gap
When senior debt capacity is exhausted but equity would be too dilutive, mezzanine debt fills the structural gap. Mezzanine sits below all senior creditors in the payment waterfall, is typically unsecured or junior-secured, and carries a higher all-in cost to compensate for subordinated risk. The current market cost structure for performing mezzanine is 8%–12% cash interest plus 2%–4% PIK (payment-in-kind), plus warrants or equity co-investment representing 1%–5% of the fully diluted cap table: producing a lender IRR of 16%–22% all-in. Maturity typically runs five to seven years, structured as a bullet payment at exit, which aligns with typical hold-period assumptions for sponsor-backed platforms.
The PIK component is the key cash-flow preservation mechanism: rather than paying interest in cash, the borrower accrues the obligation into the principal balance. This preserves liquidity during the growth phase but compounds the refinancing burden at bullet maturity, a risk that must be modeled carefully against projected exit timelines.
4. Preferred Equity and Growth Equity: The Dilutive Tier
At the top of the cost spectrum sits equity. Growth equity investors typically target 15%–30% ownership for minority positions, with preferred equity instruments carrying liquidation preferences, participation rights, and sometimes ratchets. Equity is the most expensive form of capital on a long-term IRR basis but carries no fixed cash service obligation, making it the appropriate instrument for genuine early-stage businesses with no cash flow visibility. For growth-stage operators with demonstrable EBITDA or recurring revenue, defaulting to equity represents a structural overpayment.
Structure Breakdown: A $30M Acquisition for a Growth-Stage Services Business
To ground the framework, consider a concrete scenario:
The Company: A B2B professional services platform with $8M EBITDA, $22M in revenue, 85% recurring contract base, and a target add-on acquisition priced at $30M (3.75x EBITDA). The founder-owner wants to fund the deal without giving up a board seat and without selling more than 15% of the business.
Step 1: Quantify the Gap
Start with what the bank will provide. Against $8M EBITDA at 3.0x leverage, a senior bank facility supplies approximately $24M of pro forma debt capacity. However, the bank may only stretch to 2.5x against a recurring-revenue services business with limited hard assets, call it $20M. The deal requires $30M, plus approximately $1.5M in transaction costs. The capital gap is $11.5M after the bank tranche.
Step 2: Fill with a Unitranche or Senior + Mezz Stack
Two structural paths are available:
- Option A, Unitranche: A single direct lender provides the full $30M at SOFR + 625 bps (approximately 10.9% all-in at current SOFR). The bank relationship is replaced entirely. One set of documents, one agent, faster close. Annual cash interest burden: approximately $3.3M, or ~41% of EBITDA before amortization and taxes. Leverage: 3.75x at close.
- Option B, Senior + Mezzanine Split: Bank provides $20M at SOFR + 275 bps (~6.6% all-in). A mezzanine fund layers in $10M at 10% cash + 2.5% PIK + warrants for 3% of equity. Blended cash interest: approximately $2.3M. The mezz adds a 3% equity give-up but preserves the lower-cost bank relationship and reduces year-one cash service by approximately $1M versus the unitranche.
The trade-off is structural complexity versus all-in cost. For a business confident in near-term cash generation, the senior-plus-mezz split is cheaper in cash terms. For a business prioritizing speed, covenant simplicity, and a single relationship, the unitranche wins. Growth-stage operators with EBITDA growth above 8% per year and a clear exit horizon within five to six years typically favor the mezz split, the equity kicker dilution at exit is less painful than three to four years of elevated cash debt service.
Step 3: The Equity Residual
In the senior-plus-mezz scenario, the remaining $1.5M transaction cost gap is funded from existing cash or a modest seller note. The founder issues no new equity beyond the 3% mezzanine warrant and retains full operational control. Total dilution: 3% economic, 0% governance.
Covenant Design: What the Package Actually Says
The covenant package is not boilerplate; it is the functional control architecture of the deal. Understanding the distinction between maintenance and incurrence covenants determines when a lender can intervene and how much operational flexibility the borrower retains between transactions.
Maintenance covenants require borrowers to pass financial tests every reporting period, typically quarterly, regardless of any action taken. A maximum total leverage ratio, tested quarterly and stepping down over the life of the loan, is the most common financial covenant in middle-market direct lending. A typical structure sets an opening covenant of 7.0x with quarterly step-downs to 6.0x by year four. A fixed charge coverage ratio is a common secondary covenant, typically set at a minimum of 1.10x–1.25x. Crucially, maintenance covenants are lender-monitoring tools: a covenant breach can be triggered purely by EBITDA deterioration, the borrower does not need to take any action to trip the wire.
Incurrence covenants, by contrast, are permissioning tests triggered only when a borrower proposes a specified transaction: raising additional debt, paying a dividend, or making an acquisition. The same EBITDA deterioration that would trip a maintenance covenant is irrelevant under an incurrence-only package unless the company attempts a restricted action.
The market data is stark on how this has evolved: covenant-lite institutional leveraged loans represented 91.7% of large corporate new-issue loans in the United States in 2024, according to PitchBook LCD, meaning maintenance covenants have nearly disappeared from the broadly syndicated market. However, the picture diverges sharply in private credit: direct lenders have maintained firmer positions on covenant inclusion, particularly for mid-market transactions. Maintenance covenants, quarterly tests of leverage or fixed charge coverage, have returned to many PE-backed deals financed by non-bank lenders.
Negotiation guidance: For borrowers in a growth-stage deal, push for incurrence-only packages where possible, or, where a maintenance covenant is unavoidable, negotiate the widest possible cushion (30%–40% headroom to closing leverage) and ensure the EBITDA definition includes generous add-backs for non-recurring charges, integration costs, and pro forma run-rate synergies. The EBITDA definition is where the real negotiation lives: two credit agreements with nominally identical leverage covenants can have dramatically different practical headroom depending on what the definition permits.
The Gap Capital Playbook: Quantify, Prepare, Run the Process
Phase 1: Quantify the Need
Before approaching any capital provider, operators must produce a precise uses-of-proceeds schedule: acquisition price, transaction fees, integration costs, working capital adjustments, and reserve for covenant cushion. Map each dollar to its expected return profile and duration. Capital deployed into a recurring-revenue acquisition with contractual cash flows supports more debt than capital deployed into a speculative geographic expansion. The structure must reflect the use.
Phase 2: Prepare the Materials
Lenders across the stack will evaluate the same core package differently. For senior debt and unitranche lenders, the key documents are: three years of audited financials, trailing twelve-month management accounts, a detailed customer revenue schedule (with concentration analysis), EBITDA bridge from reported to adjusted, and a base-case model with covenant compliance through maturity. For mezzanine providers, add an exit case model with warrant valuation at two to three exit multiples. Expect lender diligence (financial review, customer concentration, industry analysis, and management team assessment) to take 60–90 days from term sheet to close.
Phase 3: Run the Process
For sub-$50M transactions, direct lenders offer the most efficient execution path. Engage two to three direct lending funds simultaneously to create competitive tension on spread and structure. For deals requiring a senior-plus-mezz split, the bank and mezzanine processes can run in parallel with a coordinated closing. Be explicit about the timeline: if a purchase agreement has a financing condition with a 45-day outside date, lead with the unitranche, execution certainty is worth 50–100 basis points.
Phase 4: Negotiate the Structure
Five terms matter most in a growth-stage financing and deserve deliberate negotiation:
- Covenant headroom: Push for 35%–40% cushion to the maintenance test at close. A model-tight covenant is a liability-management event waiting to happen.
- Incremental debt baskets: Negotiate a general debt basket of at least 0.5x EBITDA, plus a specific acquisition basket for future add-ons. Growth-stage platforms need room to do the next deal without a full amendment process.
- PIK toggle: If accepting mezzanine with a cash-pay component, negotiate a toggle right that permits election of full PIK for up to two quarters per year without constituting an event of default. This preserves cash in a seasonal or integration-heavy period.
- Prepayment terms: Mezzanine call protection typically runs as a declining premium over years one through three (3%–2%–1%). Push to structure the call premium as a make-whole limited to the first twelve months, with par-plus-accrued thereafter, if exit timing is uncertain.
- Warrant strike and coverage: Mezzanine warrants typically cover 1%–5% of fully diluted equity. The strike price is the critical variable: negotiate for a fixed dollar amount (rather than a formula) set at the current enterprise value, with anti-dilution protection limited to standard issuances only, excluding future debt-for-equity conversions or preferred rounds.
Current Market Terms: What the Data Shows (H1 2026)
- Unitranche spreads (sub-$100M): Median all-in coupon at approximately 10.2% in the $5M–$50M band as of June 2026, with lower-middle-market direct lending spreads clearing at SOFR plus 450–475 basis points, a 100–150 bps premium over the broadly syndicated market, per S&P LCD US Loan Comparable data.
- Mezzanine all-in yield: 12.5%–14% for performing companies, with the cost structure running 8%–12% cash interest, 2%–4% PIK, and warrants representing 1%–5% equity, producing a lender IRR of 16%–22%.
- Covenant-lite penetration: Covenant-lite structures now represent 62% of new unitranche originations in the sub-$100M ticket band as of Q2 2026, up from 34% in Q2 2024, a meaningful shift in borrower-friendly documentation at smaller deal sizes.
- Private credit AUM: Crossed $1.7 trillion in H1 2026, with approximately 40% of new deployment targeting the lower middle-market growth segment, sustaining strong capital availability for growth-stage borrowers.
- Debt-inclusive capital events: Debt-inclusive capital events in the growth-stage band increased 47% year-over-year in H1 2026, while pure equity rounds declined 12%, confirming the structural shift away from dilutive equity as the default growth-capital instrument.
Key Takeaways
- Use-of-proceeds drives structure: Contractual recurring revenue supports more debt than speculative expansion capital. Match the instrument to the cash flow profile of the specific deployment, not to the business in aggregate.
- Mezzanine is not a last resort: For growth-stage operators with clear exit timelines, mezzanine’s equity kicker is a known, bounded cost. The 3%–5% warrant give-up is frequently less expensive in total than one additional equity round at a constrained valuation.
- The covenant package is a control document: Incurrence-only covenants are materially more borrower-friendly than maintenance tests. In the current private credit market, growth-stage borrowers have genuine negotiating leverage to push for wider headroom, use it.
- Speed has a price, and it’s worth paying selectively: A unitranche can close 30–45 days faster than a split structure. When a purchase agreement timeline is binding, the 50–100 bps execution premium is justified. When it isn’t, the senior-plus-mezz split typically produces a lower blended cash cost of capital.
- The gap capital process is a capital markets exercise: Running two to three direct lenders in parallel, coordinating senior and mezzanine closings, and presenting a clean diligence package compresses both timeline and spread. The operators who treat the capital raise as a structured sale process, not an application, consistently achieve better terms.


