
The Underwriting Question That Defines Every Deal
A sponsor presents a $10M EBITDA manufacturing company to your credit committee. The company’s income statement shows $7.2M in reported EBITDA. Management’s addback schedule (owner compensation normalization, one-time legal fees, COVID-related disruptions, and a planned facility consolidation) bridges the gap to $10M. The ask: $55M in senior secured debt at 5.5x leverage.
The question is not whether addbacks exist. The question is which ones survive independent lender scrutiny, and whether the resulting EBITDA can actually carry the debt load through a downside cycle.
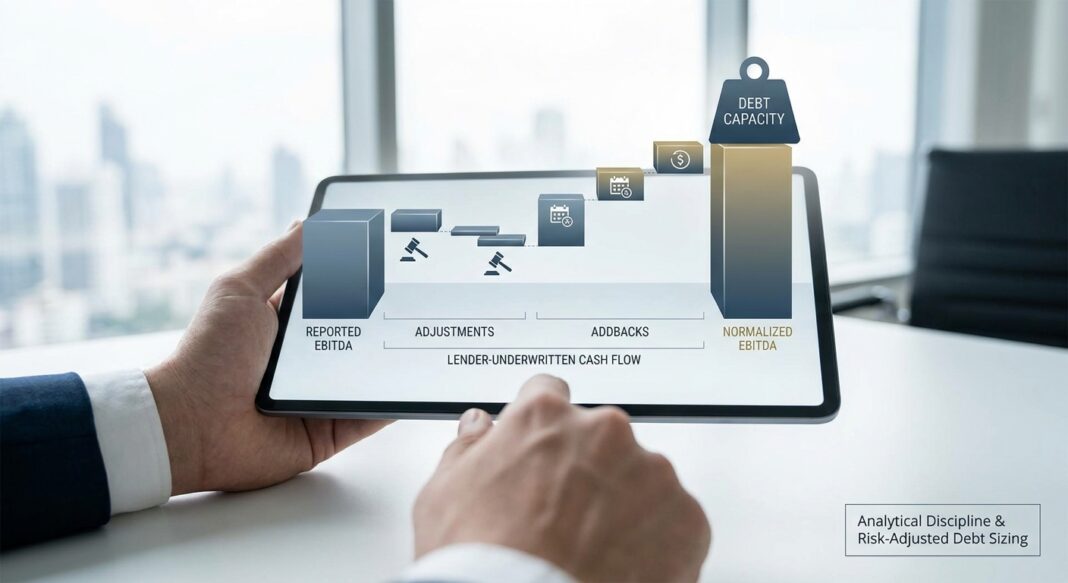
This is the core discipline of EBITDA normalization: not an accounting exercise, but a forward-looking credit judgment about sustainable, lender-underwritten cash flow. In today’s deal environment, the bridge between reported and adjusted EBITDA has become one of the most consequential (and contested) elements in any leveraged credit transaction. Getting it right protects principal. Getting it wrong underwrites the loss.
The Analytical Framework: From Reported to Lender-Underwritten EBITDA
Experienced credit underwriters distinguish between three layers of EBITDA, each serving a distinct analytical purpose:
- Reported EBITDA: The number derived directly from audited or reviewed financial statements: net income plus interest, taxes, depreciation, and amortization. This is the baseline.
- Adjusted EBITDA: The seller or sponsor’s bridge from reported EBITDA after removing non-recurring, non-cash, and non-operating items. This is the starting point for negotiation, not the ending point for underwriting.
- Normalized (Lender-Underwritten) EBITDA: The earnings level independently validated by the lender’s credit team: reflecting steady-state staffing, market compensation, necessary reinvestment, and only those adjustments backed by verifiable documentation.
The distinction matters enormously for debt sizing. As practitioners note, normalized EBITDA can be lower than adjusted EBITDA when the business requires additional costs under new ownership, and lenders must underwrite to the former, not the latter.
Step 1, Build the Reported EBITDA Bridge: Begin with three years of historical P&L and construct a clean trailing twelve-month (TTM) EBITDA figure. Confirm revenue recognition policies, customer concentration, and any restatements.
Step 2, Classify Every Addback by Category: Separate addbacks into four buckets: (a) clearly acceptable, e.g., one-time legal settlements with documented resolution; (b) conditionally acceptable, e.g., owner compensation above market replacement; (c) challenged, e.g., recurring restructuring costs relabeled as non-recurring; and (d) rejected, e.g., pro forma revenue from an unacquired target or anticipated cost savings dependent on post-closing actions.
Step 3, Apply Downward Adjustments: Buyers and lenders sometimes make downward adjustments to remove one-time revenue or non-recurring income that inflated the seller’s trailing results, reducing adjusted EBITDA below the reported figure. This step is frequently skipped by sponsor-presented models, and must not be skipped by the credit team.
Step 4, Arrive at Lender EBITDA and Test Debt Capacity: Lenders underwrite acquisition financing based on Debt/EBITDA ratios and fixed charge coverage ratios. An inflated normalized EBITDA that lenders do not accept in their own underwriting does not support the debt capacity needed to achieve target returns. The lender-underwritten EBITDA sets the ceiling on leverage, not the sponsor’s model.
Illustrative Example: A $10M EBITDA Manufacturing Company
Reported EBITDA: $7.2M
Add: Owner compensation above market replacement ($800K documented) → +$800K
Add: One-time legal settlement (resolved, no ongoing exposure) → +$400K
Add: COVID-related supply disruption (2022 only, confirmed non-recurring) → +$300K
Add: Facility consolidation savings (projected, not yet realized) → REJECTED
Less: Below-market related-party rent adjustment to market rate → -$200K
Less: Additional G&A required under new ownership → -$300K
Lender-Underwritten Normalized EBITDA: $8.2M
At 5.5x leverage, this supports $45.1M, not the $55M originally proposed.
Walking the Calculations: Leverage, Coverage, and Stress
Once normalized EBITDA is established, the underwriter runs three core credit metrics against it:
1. Total Leverage (Debt / EBITDA)
Using lender-underwritten EBITDA of $8.2M with a $45M senior debt request: Total Leverage = $45M / $8.2M = 5.5x. Senior lenders typically target 4.0–5.0x for first-lien facilities. At 5.5x on lender-underwritten EBITDA, this deal is at the upper boundary, and that is before any revenue stress.
2. Interest Coverage (EBITDA / Interest Expense)
Assuming a SOFR + 525bps all-in rate of approximately 10.5% on $45M debt: Annual interest = ~$4.7M. Coverage = $8.2M / $4.7M = 1.74x. Interest coverage of 3.0x or higher is generally considered healthy. Leveraged companies typically operate between 1.5x and 3.0x; this borrower is in the lower range of acceptable. Below 1.5x is a hard red flag for credit quality.
3. Fixed Charge Coverage Ratio (FCCR)
FCCR = (EBITDA − Capex) / (Interest + Required Amortization). Assuming $1.5M maintenance capex and $1.5M annual amortization: FCCR = ($8.2M − $1.5M) / ($4.7M + $1.5M) = $6.7M / $6.2M = 1.08x. An FCCR below 1.0x is a common covenant trigger in credit facilities, signaling the company cannot cover both interest and capex from normalized EBITDA. At 1.08x, there is minimal cushion, a 10% EBITDA compression takes coverage below 1.0x.
Downside Stress Case
Apply a 15% revenue stress (moderate recession scenario) with 30% flow-through to EBITDA: Stressed EBITDA = $8.2M × 0.85 = ~$7.0M. Stressed FCCR = ($7.0M − $1.5M) / $6.2M = 0.89x: a covenant breach. This is precisely why addback quality is a first-order credit risk, not a documentation technicality. Overly aggressive normalization can cause DSCR to appear acceptable on paper but fail under stress.
Industry Standards: What Institutional Lenders Demand
The private credit market has grown rapidly, with corporate lending assets under management expected to exceed $2 trillion in 2026 and grow toward $4 trillion by the end of the decade. That scale demands rigorous underwriting discipline, particularly as deal structures evolve and covenant protections erode.
What Sophisticated Credit Teams Require
- Independent QoE Report: Lenders independently evaluate normalized EBITDA during underwriting. Seller-provided schedules are viewed as a starting point, not a conclusion. A Quality of Earnings report from an independent accounting firm is required on any transaction above $10M in debt.
- Documentation for Every Addback: Each adjustment must be clearly documented and justified. Excess owner compensation is accepted only after deducting the market cost of replacing the owner’s operating role. Anticipated cost savings are rejected if they depend on post-closing actions.
- Addback Caps: Many institutional lenders cap total adjustments at 20–25% of reported EBITDA. Addback schedules exceeding this threshold receive heightened scrutiny and require board-level credit approval.
- Durability Testing: Implemented price increases receive credit only if invoices and retention data show the increase is already in the run rate. Forward projections without a track record receive zero credit.
📊 Credit Performance Data Box
- Private Credit Default Rate (2025): Moody’s estimates the private credit direct lending default rate ranged between 1.6% and 4.7% in 2025, depending on whether distressed exchanges are included. (Source: Moody’s Ratings, April 2026)
- Distressed Exchanges: Roughly 65% of all corporate defaults in 2025 were distressed restructurings, not hard defaults, representing workouts, debt-for-equity swaps, and indenture modifications. (Source: Moody’s Ratings, May 2026)
- Leveraged Loan Index Default Rate: The trailing 12-month default rate of the US Leveraged Loan Index was 1.5% at Q3-2025 on a headline basis; including distressed liability management exercises, the rate reaches 4.3%. (Source: Northleaf Capital / PitchBook LCD, Q3 2025)
- Cliffwater CDLI Realized Losses (2025): The Cliffwater Direct Lending Index estimated realized losses for all BDC underlying loans at 0.70% for calendar year 2025, below the 1.01% annual historical loss rate for private debt. (Source: Cliffwater LLC / Dechert, March 2026)
- 2021 Vintage Underperformance: Deals underwritten in the 2021 vintage have seen weaker performance, likely due to post-COVID elevated earnings in specific sectors and liquidity pressures from elevated leverage and rates, a direct consequence of aggressive EBITDA normalization at origination. (Source: Northleaf Capital, Q3 2025)
Common Red Flags in EBITDA Addback Schedules
- Recurring costs relabeled as non-recurring: restructuring charges that appear in consecutive years are not one-time events.
- Stock-based compensation addbacks for debt capacity: SBC represents real economic value transferred to employees; many PE buyers exclude SBC specifically when calculating debt capacity.
- Pro forma acquisitions with no track record: buyers give zero credit for pro-forma add-ons from planned but unclosed acquisitions.
- Below-market related-party transactions presented without market-rate adjustment: related-party rent or management fees must be normalized to arm’s-length economics.
- Unsupported synergy assumptions: cost savings without signed vendor agreements or executed headcount reductions are hypothetical, not historical.
The Underwriting Checklist: EBITDA Normalization Diligence
Use this checklist as a systematic gate before any credit approval that relies on adjusted EBITDA:
Documentation Requirements
- ☐ Three full years of audited or reviewed financial statements (CPA-prepared at minimum)
- ☐ TTM financials through the most recent quarter-end
- ☐ Independent Quality of Earnings (QoE) report from a recognized accounting firm
- ☐ Detailed addback schedule with dollar amounts, descriptions, and supporting documentation for each item
- ☐ Market compensation study supporting owner pay normalization
- ☐ Arm’s-length appraisal or comp data for any related-party rent or fee adjustments
Analytical Questions to Answer
- ☐ What is the total addback as a percentage of reported EBITDA? Does it exceed 25%? If so, why?
- ☐ Have any addback categories appeared in more than one fiscal year? If so, they are not non-recurring.
- ☐ Does lender-underwritten EBITDA support the requested leverage at a minimum 1.1x FCCR under base case?
- ☐ Under a 15–20% revenue stress, does FCCR remain above 1.0x? If not, is the covenant threshold appropriate?
- ☐ Has the company made downward adjustments for any non-recurring revenue or one-time income items?
- ☐ Are any pro forma cost savings included? Have they been validated by signed agreements or completed actions?
- ☐ What is the realistic replacement cost for owner functions post-close?
- ☐ Does maintenance capex reflect actual historical spend, or a management-presented run-rate?
Final Credit Gate
- ☐ Compare lender-underwritten EBITDA to sponsor EBITDA, document the variance and its basis
- ☐ Size debt to lender EBITDA only; do not allow sponsor EBITDA to govern the debt quantum
- ☐ Confirm that covenant levels are set to lender EBITDA, not sponsor EBITDA, to ensure early-warning triggers fire before real impairment
Key Takeaways
- Lender EBITDA is always independent: Seller-provided addback schedules are a starting point. Every adjustment must be independently validated against documentation before it earns credit in leverage or coverage calculations.
- Normalized EBITDA is not the same as adjusted EBITDA: Adjusted EBITDA cleans reported earnings; normalized EBITDA answers what the business will earn under new, steady-state ownership, including costs the seller does not currently bear.
- Addback inflation creates vintage risk: The 2021 credit vintage demonstrates the consequence of aggressive normalization at origination, borrowers underwritten on peak, post-COVID earnings at high leverage ratios faced structural stress when earnings normalized and rates rose.
- The FCCR is the stress test that matters most: Interest coverage tells you about today. Fixed charge coverage, incorporating mandatory amortization and maintenance capex, tells you whether the business can service debt through a cycle, which is the only timeframe that matters for a multi-year credit.
- Documentation discipline is credit discipline: In private credit markets where realized losses remain below 1% annually for senior secured lenders, the difference between performing and non-performing credits often traces back to origination quality, specifically, whether addbacks were defensible and independently verified at close.


