
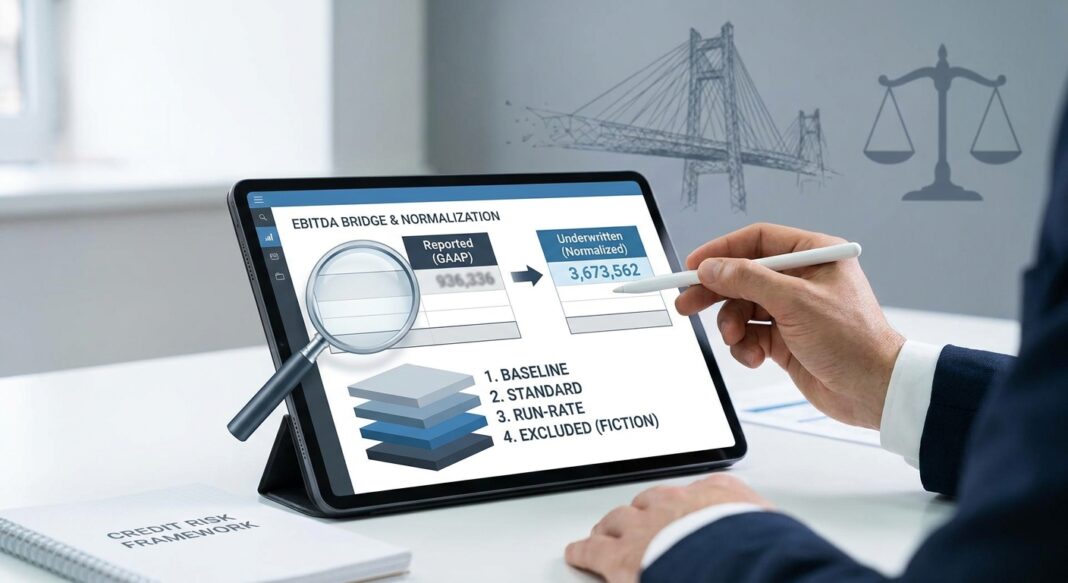
The Underwriting Challenge: When EBITDA Becomes a Moving Target
Imagine you are underwriting a $40 million unitranche facility for a private equity-backed manufacturing company reporting $10 million in Adjusted EBITDA. The sponsor’s CIM shows a clean bridge from $6.8 million reported EBITDA to $10 million adjusted, a $3.2 million add-back stack representing nearly 47% of the reported base. The numbers look compelling. The leverage ratio clears your threshold. The DSCR checks out at 1.3x. But should you believe any of it?
This is the central tension in credit underwriting. EBITDA as reported and EBITDA as underwritten are rarely the same number, and the gap between them is where credit risk lives. Sponsors and sellers are structurally motivated to maximize adjusted EBITDA: every dollar of adjusted EBITDA at a 6.0x multiple adds $6.00 to enterprise value, which determines deal pricing, debt capacity, and sponsor returns. Lenders sit on the other side of that equation, underwriting leverage ratios and coverage tests against an earnings figure they did not produce and cannot take for granted.
In today’s market, this discipline has become existential. Lender tolerance for speculative add-backs has narrowed materially, QoE scrutiny has intensified, and distressed exchanges have exposed the consequences of inflated earnings bases entering capital structures at elevated leverage. The underwriter’s job is to rebuild EBITDA from the general ledger up, not accept the sponsor’s bridge at face value.
The Framework: Four Layers of EBITDA Normalization
Professional credit underwriters analyze EBITDA adjustments across four distinct layers, each with different levels of credibility and risk weighting. A rigorous normalization process does not start with the sponsor’s adjusted figure and work backward; it starts with audited or tax-basis financials and reconstructs earnings from scratch.
Layer 1: Baseline EBITDA (Reported)
Start with GAAP net income from the most recent audited financials or tax returns, then add back interest expense, income taxes, depreciation, and amortization. This is non-negotiable and non-adjustable. Use trailing twelve months (TTM) as the primary period, but also examine a three-year historical average to identify trend directionality. A business with declining margins over 36 months but a strong TTM requires a different risk lens than a genuinely recovering credit.
Example, $10M EBITDA Manufacturing Company: Net income of $2.1M + interest expense $2.3M + taxes $0.8M + D&A $4.8M = Reported EBITDA of $10.0M. If sponsor-adjusted EBITDA is $13.2M, the lender must evaluate every dollar of the $3.2M add-back stack before accepting it as a collateral basis for debt sizing.
Layer 2: Standard Normalization Adjustments (High Credibility)
These are broadly accepted by institutional lenders and carry high evidentiary weight when documented:
- Excess owner compensation: Only the delta between actual pay and documented market-rate replacement cost is added back. Full owner comp removal is a seller-side metric (SDE), not a lender metric.
- One-time legal settlements: Accepted only if the underlying matter is fully resolved with no ongoing exposure or litigation tail.
- Transaction-related expenses: M&A legal, advisory, and due diligence fees incurred for the current transaction are broadly accepted when clearly tied to the sale process.
- Non-cash stock-based compensation (SBC): Addable in principle, but many PE buyers and lenders exclude SBC when calculating debt capacity because it represents real economic value transferred to employees.
Layer 3: Run-Rate and Pro Forma Adjustments (Medium Credibility)
These adjustments anticipate future performance and carry higher underwriting risk. Implemented price increases receive credit only when invoice data and customer retention rates already reflect the increase in the run rate. Anticipated cost savings are frequently rejected when they depend on post-closing actions that have not yet been implemented. Synergies in acquisition contexts are the most contested category, institutional lenders routinely apply haircuts of 25–50% to synergy-based EBITDA add-backs before including them in leverage calculations.
Layer 4: Recurring Expenses Dressed as One-Time (Zero Credibility)
This is the red flag category. The most consistently rejected add-back in lender QoE reviews is recurring operational cost reclassified as non-recurring. Underwriters should look for the same cost appearing in multiple periods under different labels, maintenance capex classified as growth capex, and normalized cost structures that produce margin profiles inconsistent with the company’s peer group. When a single add-back is rejected at a 6.5x multiple, the enterprise value impact is not $1; it is $6.50 per dollar of disallowed earnings.
Walking the Numbers: Underwriting a $10M EBITDA Manufacturing Credit
Return to our example. The sponsor presents $13.2M Adjusted EBITDA via a $3.2M add-back bridge. The lender’s QoE team decomposes it as follows:
| Add-Back Item | Sponsor Claim | Lender Credit | Rationale |
|---|---|---|---|
| Excess Owner Compensation | $750K | $500K | Market replacement cost deducted |
| One-Time Legal Settlement | $400K | $400K | Matter resolved, no tail risk documented |
| Transaction Advisory Fees | $350K | $350K | Current transaction only, fully documented |
| IT Upgrade (labeled one-time) | $600K | $0 | Same charge appeared in prior two years, recurring maintenance |
| Anticipated Cost Savings (post-close) | $900K | $0 | Not yet implemented; rejected per lender protocol |
| Pro Forma Price Increase | $200K | $150K | Partial credit, increase documented in invoices but not yet fully in run-rate |
| Total Add-Backs | $3,200K | $1,400K | $1.8M rejected |
Result: Lender-underwritten EBITDA = $10.0M reported + $1.4M credited = $11.4M, not $13.2M. At a 4.0x senior leverage multiple, this reduces supportable senior debt from $52.8M to $45.6M: a $7.2M difference in debt capacity that directly affects deal pricing, sponsor equity requirement, and return math. At the 7.2x total leverage the sponsor’s model implied, actual lender-tested leverage clears closer to 6.3x. That is a meaningful distinction for a credit committee.
DSCR Stress Test
Apply a 15% EBITDA haircut to model a mild revenue contraction: $11.4M × 0.85 = $9.69M stressed EBITDA. With annual debt service of $7.2M on a $45.6M term loan at SOFR + 550 bps (approximately 10.3% all-in as of mid-2026), stressed DSCR = $9.69M ÷ $7.2M = 1.35x: above the 1.25x institutional minimum threshold. Under a more severe 25% EBITDA stress, DSCR falls to 1.14x, breaching standard covenant floors and flagging material downside risk at current debt sizing.
What Institutional Lenders Look For: Market Standards and Credit Data
Add-Back Caps Are Now Standard Credit Infrastructure
Lenders are not simply scrutinizing add-backs qualitatively; they are embedding hard caps into credit documentation. In private credit agreements, lenders now commonly impose percentage-of-EBITDA caps on projection-based or non-recurring adjustments, time-based restrictions, and shared caps across multiple adjustment categories. This structural discipline reflects the industry’s response to years of EBITDA inflation eroding credit quality ahead of default cycles.
The market context underscores why this matters. Private credit lenders have maintained firmer positions on covenant inclusion, particularly for mid-market transactions. In the broadly syndicated loan market, approximately 90% of new loans in 2024 remained covenant-lite, but the private credit middle market has moved in the opposite direction, with maintenance covenants and quarterly leverage tests returning as standard documentation for PE-backed deals financed by non-bank lenders.
Key Credit Performance Data Points
📊 Credit Performance Data Box
- U.S. leveraged loan default rate: Peaked at 7.1% in September 2024, driven largely by distressed exchanges, more than 2x its long-term average and near the pandemic peak of 7.5% in September 2020. (Source: Moody’s via Capra Ibex, 2024)
- High-yield default rate: S&P reported a trailing 12-month high-yield default rate above 4% through September 2025, near the long-term average of ~4.5%. (Source: Valuation Research Corp., citing S&P, 2026)
- Senior secured loan recovery: First-lien senior secured loans have historically recovered roughly 70–80 cents on the dollar on an ultimate basis. Moody’s most recent estimates put expected first-lien recoveries at approximately 68%, down from the high-70s historical average, reflecting heavier first-lien debt loads in modern capital structures. (Source: Moody’s Ultimate Recovery Database via CLO Data, 2026)
- Middle market leverage: Middle market first-lien debt averaged 4.5x leverage as of Q3 2024 per PGIM, versus 5.8x in the broadly syndicated loan market. Average total leverage across S&P’s U.S. middle market credit estimate population hit 7x in 2024. (Source: ABF Journal / PGIM / S&P, 2025)
- Reported-to-adjusted EBITDA gap: The typical gap between reported and adjusted EBITDA in well-documented bridges runs 20–30% of reported EBITDA. Gaps materially wider than 30% are a consistent predictor of aggressive add-backs that lenders will challenge during QoE. (Source: Iconic / Pepperdine Private Capital Markets Report, 2025)
- Covenant-lite distressed exchange risk: According to Moody’s, deals with covenant changes boosting debt capacity amounted to as much as 40–300% of EBITDA, with 10% of credit agreements reviewed between 2024 and May 2025 containing such provisions, all involving PE-backed borrowers. (Source: Moody’s via Reuters/Investing.com, 2025)
The QoE Standard: Independent Recalculation, Not Verification
A Quality of Earnings (QoE) report is not a review of the sponsor’s bridge; it is an independent accounting firm’s recalculation of EBITDA from the general ledger up, testing every add-back and revenue line for accuracy and sustainability. Sophisticated lenders require a buy-side QoE on any transaction above a materiality threshold, and they treat the seller’s adjusted EBITDA as a starting point, not a conclusion. Lenders independently assess adjustments to determine whether they are reasonable, documented, and consistent with the lender’s own underwriting standards, the seller-provided schedule is the beginning of the analysis, not the end.
Credit Underwriting Checklist: EBITDA Normalization Due Diligence
Documentation Requirements
- ☐ Three years of audited or CPA-reviewed financial statements (GAAP basis)
- ☐ Three years of federal tax returns, reconcile to financial statements
- ☐ TTM financials bridged to most recent month-end
- ☐ General ledger support for every add-back exceeding $50K
- ☐ Independent QoE report from a recognized accounting firm
- ☐ Payroll records for owner/family compensation normalization
- ☐ Third-party documentation for related-party rent/management fee adjustments
Questions Every Underwriter Must Ask
- ☐ Does the tax return net income reconcile to the financial statements? If not, why not?
- ☐ Has any “one-time” cost appeared in more than one period? If so, it is recurring by definition.
- ☐ Is the adjusted margin profile consistent with the industry peer group? An outlier margin demands explanation.
- ☐ For run-rate adjustments: what is the documented evidence that the revenue or cost change is already in the run rate?
- ☐ For anticipated savings: have they been implemented? Can they be contractually confirmed?
- ☐ Does the adjusted EBITDA support the DSCR covenant floor under a 15–25% stress scenario?
- ☐ What is the lender’s EBITDA add-back cap in the credit documentation? Does it match industry standard?
Analytical Cross-Checks
- ☐ Run a three-year revenue CAGR check: does EBITDA growth outpace revenue growth? If so, scrutinize margin expansion assumptions.
- ☐ Calculate maintenance capex as a percentage of revenue and verify it is excluded from EBITDA (not capitalized to inflate earnings).
- ☐ Benchmark total leverage at lender-tested EBITDA against sector comps. Alert if leverage exceeds sector median by more than 1.0x turn.
- ☐ Confirm that working capital normalization is symmetric: revenue-side adjustments must be accompanied by corresponding cost-side adjustments.
Key Takeaways for Credit Underwriters
- EBITDA is a hypothesis, not a fact. Every adjusted figure represents a claim about future earnings capacity. Your job is to test the claim, not accept it. Treat seller-provided schedules as a starting point and rebuild from the general ledger independently.
- The gap tells the story. A reported-to-adjusted EBITDA bridge wider than 30% is a structural warning sign. It does not automatically disqualify a credit, but it demands line-by-line forensic scrutiny, not summary review.
- Lender-tested EBITDA drives real debt capacity. Any add-back that your credit committee will not accept in its leverage calculation is not real EBITDA for underwriting purposes, regardless of what the sponsor’s model shows or what the purchase price implies.
- Stress test the coverage covenant from day one. A 1.25x DSCR at closing is not a safety margin; it is the floor. Build your base case at 1.40x or above and model the DSCR breach point explicitly. Know at what EBITDA decline level your covenant is triggered before you close.
- Documentation is not a formality; it is the credit. The best underwriters do not simply ask whether an add-back is legitimate; they ask whether it is traceable, documented, non-recurring by verifiable evidence, and defensible to a credit committee six months into a workout. If the answer to any of those questions is uncertain, the add-back should be haircut or excluded.


