
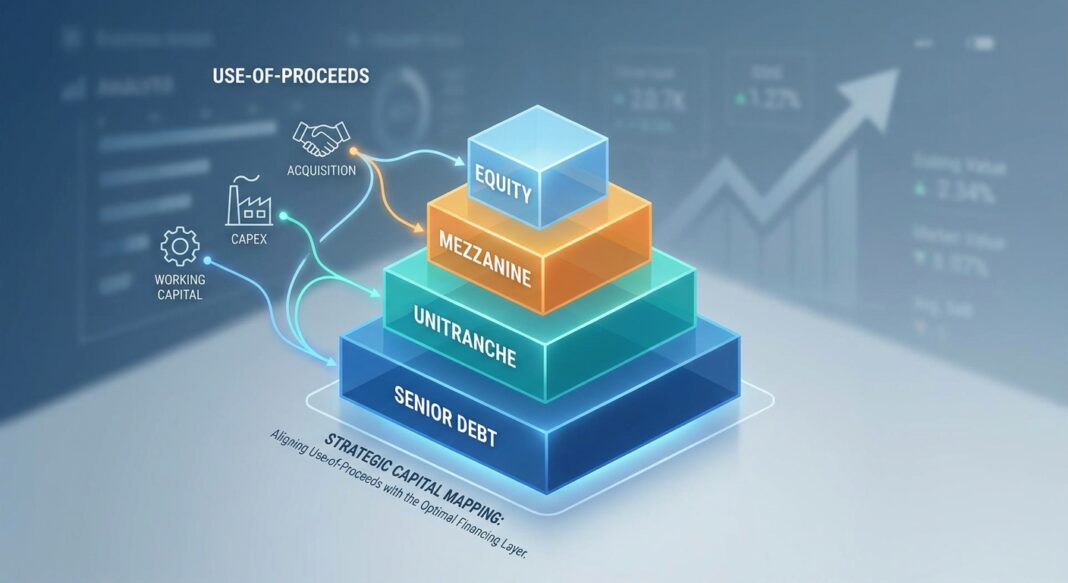
The Challenge: Growth Capital at the Inflection Point
Every lower-middle-market (LMM) operator eventually reaches the same inflection point: the business generates real cash flow, a strategic opportunity (an acquisition target, a new facility, a product buildout) is sitting on the table, and internal cash generation alone cannot fund it at the pace the market demands. The instinct is to call a banker or pick up a term sheet. The discipline is to stop, map the use-of-proceeds precisely, and then select the layer of the capital stack that prices that specific risk most efficiently.
This is the core challenge of growth-stage financing: the stack is not one decision. It is a sequence of decisions: each tied to a specific use, a specific risk, and a specific cost. A $10M EBITDA business funding a tuck-in acquisition has a fundamentally different capital structure than the same business funding a 24-month working capital ramp. Getting that mapping wrong is not a paperwork problem. It is a cash-flow problem that compounds on a fixed amortization schedule.
What follows is a practitioner’s guide to navigating the capital stack at the growth stage, from the cheapest senior debt available to the most patient equity at the top, with current 2026 market pricing, covenant realities, and a step-by-step playbook for identifying the gap, building the case, and negotiating the structure.
The Cost-of-Capital Spectrum: Banks to Equity
The capital stack for a growth-stage LMM business in 2026 runs from the cheapest secured debt to the most expensive dilutive equity. Understanding what each layer prices, what it funds, and what it requires is the foundation of every structuring conversation.
Layer 1: Senior Debt (Banks and Direct Lenders)
Senior debt is the cheapest available capital for a profitable LMM business. In 2026, senior term loans from direct lenders price at SOFR + 500–800 basis points depending on leverage and industry, per Refinitiv LPC quarterly LMM lender surveys cited by ctacquisitions.com. It carries no dilution and no board seat, but it requires monthly cash service, financial covenants, and often personal guarantees. Leverage capacity sits at 3.0x–3.7x EBITDA on a standalone senior basis; GF Data reported an average senior leverage multiple of 3.7x in Q1 2026 per ctacquisitions.com.
Best for: Working capital facilities, refinancing existing debt, capex against hard assets, and bolt-on acquisitions where senior leverage alone closes the gap.
Layer 2: Unitranche (Private Credit / Direct Lending)
Unitranche debt collapses the traditional senior-plus-mezzanine structure into a single instrument with one credit agreement, one lender group, and one covenant package. In 2026, unitranche pricing runs at SOFR + 500–700 basis points, with an all-in cost of approximately 9.5%–11% on a typical 5x leverage deal, per ctacquisitions.com. Leverage capacity extends to 4x–6x EBITDA, materially above what traditional senior debt will support. Original issue discount (OID) typically runs 2%–3% of funded principal at closing.
The speed premium is real: unitranche structures can close 30–45 days faster than syndicated alternatives, which sponsors frequently justify against the cost of a broken purchase agreement, per privateequitybro.com. The market has grown from roughly $20B in annual issuance in 2015 to over $200B in 2025 as direct lenders displaced traditional bank syndication for sub-$1B EBITDA borrowers, per ctacquisitions.com.
Best for: Platform acquisitions, management buyouts, and operator recapitalizations where speed, certainty, and leverage above 3.5x are all required simultaneously.
Layer 3: Mezzanine (Subordinated Debt with Equity Features)
Mezzanine sits between senior debt and equity in the stack, typically adding 1.0x–1.5x EBITDA of leverage on top of a senior tranche. In 2026, all-in yields on LMM mezzanine paper run 12%–15%, structured as a 10%–12% cash coupon, 1%–3% PIK interest, and 1%–2% equity warrant coverage, per ctacquisitions.com. Warrant coverage on true mezzanine ranges from 1%–5% of fully diluted equity in 2026 and is negotiable based on how much cash coupon the borrower can support versus deferring cost into PIK and equity upside, per ctacquisitions.com.
PIK interest, where coupon accrues onto principal rather than being paid in cash, has become increasingly prevalent. In 2025, public BDCs received an average of 8% of their investment income through PIK interest, reflecting the growing prevalence of PIK structures across private credit markets, per ibinterviewquestions.com.
Best for: Acquisitions where senior debt is capped, equity capacity is limited, and the target generates predictable free cash flow with a clear path to refinancing within five to seven years.
Layer 4: Preferred and Structured Equity
Preferred equity with a PIK toggle is the most common structured capital instrument in 2026, replacing traditional convertible notes that dominated the 2020–2022 SPAC era, per ctacquisitions.com. In the current rate environment, structured coupon rates have moved to 10%–14% with steadier warrant packages. Growth minority equity checks in the LMM cleared at 8.0x–11.5x EBITDA in 2025 per GF Data.
Best for: Operators seeking partial liquidity without a full sale, scale-up capital exceeding what debt alone can fund, or balance-sheet repair situations where leverage headroom is exhausted.
Layer 5: Common Equity
Common equity (whether contributed by a PE sponsor, family office, or management) forms the top layer of the stack. It is the most expensive capital on paper but the most patient and the most aligned with growth outcomes. Equity as a percentage of purchase price has risen from roughly 40% pre-pandemic to 51.7% in Q1 2026 per PitchBook’s Q1 2026 US PE Breakdown, cited by ctacquisitions.com, reflecting the discipline of a higher-rate environment.
Use-of-Proceeds Mapping: Matching the Layer to the Need
The single most common structuring error LMM operators make is treating all capital needs as interchangeable. They are not. Each use-of-proceeds has a natural home in the stack based on three variables: the risk profile of the investment, the cash flow available to service the layer, and the time horizon to repayment or exit.
| Use of Proceeds | Natural Stack Layer | 2026 Leverage/Sizing | Key Structural Feature |
|---|---|---|---|
| Working capital ramp | Revolver / ABL | 80–90% of eligible AR; 40–60% inventory | Borrowing base, dominion of funds |
| Equipment / capex | Senior term loan | 70–90% LTV on new assets | Asset liens, maintenance covenants |
| Tuck-in acquisition (<$25M EV) | Senior + seller note | 2.0x–3.5x EBITDA senior | Springing maintenance covenant on revolver |
| Platform acquisition ($25M–$150M EV) | Unitranche | 4.0x–6.0x EBITDA blended | Single covenant package, OID 2–3% |
| Acquisition requiring stretch leverage | Senior + mezzanine | 3.0–3.5x senior + 1.0–1.5x mezz | PIK toggle, warrant 1–5%, intercreditor |
| Minority recap / partial liquidity | Structured equity / preferred | 20–45% dilution | PIK coupon 10–14%, board observer rights |
| Full transition / succession | Control equity + senior debt | Full stack at 4.2x–5.0x total leverage | Rollover 10–30%, R&W insurance |
Sources: financely-group.com; ctacquisitions.com
The critical operating rule: borrow against the cash flow the use-of-proceeds will generate, not the best-case projection. Lenders underwrite to the base case; covenants are set against the base case; the margin call comes when the downside case is realised mid-amortization schedule.
Worked Example: The $75M Acquisition by a $8M EBITDA Platform
Consider a scenario: a regional services business with $8M of EBITDA wants to acquire a complementary operation at a $75M enterprise value (approximately 9.4x EBITDA). The combined entity would generate $14M of pro-forma EBITDA. The buyer has $8M of equity available. The gap is $67M.
The default 2026 LMM capital stack for this scenario, consistent with patterns described by ctacquisitions.com, would look like this:
- Unitranche (Direct Lender): $49M at 4.0x pro-forma EBITDA | SOFR + 575 bps (~10.0% all-in) | 6-year term, 1% annual amortization, bullet at maturity | OID: 2.5% | Single maintenance covenant: Total Net Leverage ≤ 5.25x tested quarterly
- Mezzanine Tranche: $14M at 1.0x pro-forma EBITDA on top of unitranche | 11% cash + 2% PIK + 2% warrant coverage on fully diluted equity | 7-year term, bullet maturity | Intercreditor agreement with unitranche lender
- Management Equity Roll / Sponsor Check: $12M common equity (~16% of $75M EV)
- Total Leverage: ~4.5x pro-forma EBITDA (within the 4.2x–5.0x LMM average per GF Data / PitchBook Q1 2026)
The blended cost of this stack, approximately 10.5%–11.5% on the debt layers: is materially cheaper than the 22%–28% implied cost of growth equity for the same capital, as benchmarked by ctacquisitions.com. The trade-off is fixed cash service obligations and a quarterly maintenance test the business must pass regardless of operating conditions.
Covenant Reality in 2026: What Layer You Choose Determines What You Sign
The covenant package is not a negotiation footnote; it is a structural feature that determines how much operating flexibility you retain and when your lender can intervene.
The divergence between public and private credit markets is stark. As of December 31, 2025, approximately 90% of outstanding syndicated loans featured covenant-lite structures, compared to only 14% for private credit senior financings, per FS Credit Opportunities Corp.’s FY2025 Form N-CSR filing with the SEC. At the lower end of the LMM, issuers with EBITDA below $50M, just 3% of private credit loans were covenant-lite as of the same date.
The mechanics matter. A maintenance covenant is a recurring financial test, usually quarterly, that a borrower must pass whether or not it has taken any new action. An incurrence covenant is a permissioning test triggered only when a borrower proposes a specific transaction, such as raising additional debt or paying a dividend, per privateequitybro.com. In private credit, maintenance covenants provide early warning signals, while incurrence covenants prevent actions that increase lender risk, and their use shifts with borrower size, maintenance tests are more prevalent with smaller borrowers, per Golub Capital.
One emerging trend: covenant-lite structures reached 21% of direct lending transactions in 2025, up from just 4% in 2023, per data cited by aspirations-group.com. However, this is concentrated at the upper end: for core LMM operators below $50M EBITDA, quarterly maintenance tests remain the norm, and borrowers should model covenant headroom explicitly before signing.
Practical structuring rule: If your business is seasonal, cyclical, or in an integration year post-acquisition, negotiate for incurrence-style covenant relief or a covenant holiday for the first two to four quarters. Most direct lenders will accommodate this with a tighter initial leverage step-down schedule rather than a full maintenance holiday.
The Gap Capital Playbook: Quantifying, Preparing, Running the Process
Once the use-of-proceeds is mapped and the stack layer is identified, execution follows a defined sequence. Cutting corners at any step extends timeline, widens pricing, or collapses the deal.
Step 1: Quantify the Gap with Precision
Build a lender-grade financial model with base and downside scenarios, with drivers that match how the business actually runs. The gap is not the difference between purchase price and equity check; it is the maximum debt service the business can support at 1.10x–1.25x fixed charge coverage in the downside case, subtracted from the total financing need. Size the debt layer to that number, not the best case. Clean working capital data (AR/AP agings and inventory that reconcile to the ledger) is non-negotiable for lender approval, per financely-group.com.
Step 2: Prepare a Lender-Grade Data Package
The materials should include three years of audited financials plus YTD, 24 months of monthly management accounts with variance analysis, a 12–36 month model (base and downside), AR and AP agings, a customer/supplier top-20 list, full legal package, and a tight use-of-funds memo that maps each dollar to a cash outcome and a repayment source. The use-of-funds memo is where most operators fail, vague language signals execution risk to underwriters and widens pricing, per financely-group.com.
Step 3: Run a Targeted, Competitive Process
Engage lenders that actually write your ticket size in your sector. An organized process run by an advisor generally lifts final pricing by 100–250 basis points versus a bilateral negotiation with a single fund, per ctacquisitions.com. Timing from signed IOI to funding on a mezzanine tranche typically runs 8–14 weeks, with the intercreditor negotiation and quality-of-earnings work driving the critical path. On unitranche, expect 4–8 weeks given the single-lender structure.
Step 4: Manage the Intercreditor Early
If the structure includes both senior and mezzanine layers, the intercreditor agreement (defining each lender’s rights in default, enforcement standstill periods, and PIK/payment waterfall) must be aligned before the LOI is signed. Leaving intercreditor negotiation to the back end of the process is the single fastest way to blow a closing timeline. For unitranche structures, this dynamic is eliminated: there is one lender, one credit agreement, and no intercreditor to negotiate.
Negotiation Guidance: Five Points That Move the Economics
- OID and Upfront Fees: On a $50M unitranche, a 2.5% OID versus a 3.0% OID is a $250K cash difference at close, fully negotiable in a competitive process. Push for an expense cap on lender counsel of $250K–$400K, which is market for LMM unitranche transactions, per ctacquisitions.com.
- PIK Toggle vs. Mandatory PIK: On the mezzanine tranche, a PIK toggle, where the borrower can elect to PIK coupon for defined periods, is materially preferable to mandatory PIK, which accretes automatically. A toggle preserves cash management flexibility without permanently adding to principal. Negotiate the toggle period to cover the integration year of any acquisition.
- Warrant Coverage: Warrants on mezzanine are negotiable downward when: (a) the business is profitable with strong coverage, (b) the process is competitive, and (c) the cash coupon is above 11%. An independent-sponsor deal typically prices 50–100 bps wider than a PE-sponsor deal of equivalent size, per ctacquisitions.com, closing that gap with a credible capital advisor is the single highest-ROI spend in the process.
- MFN Protection: Most-favored-nation provisions, which reprice your existing debt upward if you raise subsequent debt at wider spreads, should be resisted or neutralized. LMM lenders will typically drop MFN entirely if pushed on a competitive term sheet round, per ctacquisitions.com.
- Covenant Cushion: The set-point for any maintenance covenant (typically a net leverage or fixed charge coverage ratio) should be negotiated with at least 20%–25% headroom to your base-case projection. Lenders set the initial threshold; borrowers negotiate the starting point. Model the downside scenario against the proposed covenant level before executing the term sheet, not after.
Key Takeaways
- Map the use-of-proceeds first, then select the stack layer. Working capital belongs in a revolver or ABL; acquisitions at scale belong in unitranche or senior-plus-mezz. Conflating the two destroys pricing and structure.
- In 2026, the blended cost of a properly structured debt stack (9.5%–11.5%) remains materially cheaper than growth equity (22%–28% implied cost), but only when fixed charge coverage holds at 1.10x or better in the downside case.
- Unitranche dominates the $25M–$200M EV acquisition market for speed, certainty, and single-lender simplicity. It has captured over 70%–80% of deals in that range, per market data, and its pricing has compressed modestly in 2026 as private credit AUM surpassed $2.1 trillion.
- Covenant design is structural, not administrative. Maintenance covenants remain standard in the LMM private credit market, just 3% of loans to sub-$50M EBITDA issuers are covenant-lite. Negotiate headroom and integration holidays at term sheet, not at amendment.
- A competitive, advisor-run process improves final pricing by 100–250 basis points on the mezzanine layer versus a bilateral negotiation, a difference that compounds across a five-to-seven-year instrument tenor into a material economic outcome.


