
Market Headline: A Lender-Friendly Reset Takes Hold, But Dispersion Is the Defining Risk
Private credit entered mid-2026 having passed through one of its most turbulent stretches since the asset class went mainstream. Three converging forces (the outbreak of the U.S.-Iran military conflict in late February, an AI-driven reassessment of software credit quality, and a wave of investor redemptions at select non-traded BDCs) struck simultaneously and reshaped the lending environment with unusual speed. What began as a promising continuation of strong 2025 momentum gave way to concerns shaped by these converging and largely unforeseeable issues, according to Capstone Partners’ Q1 2026 Leveraged Finance Update.
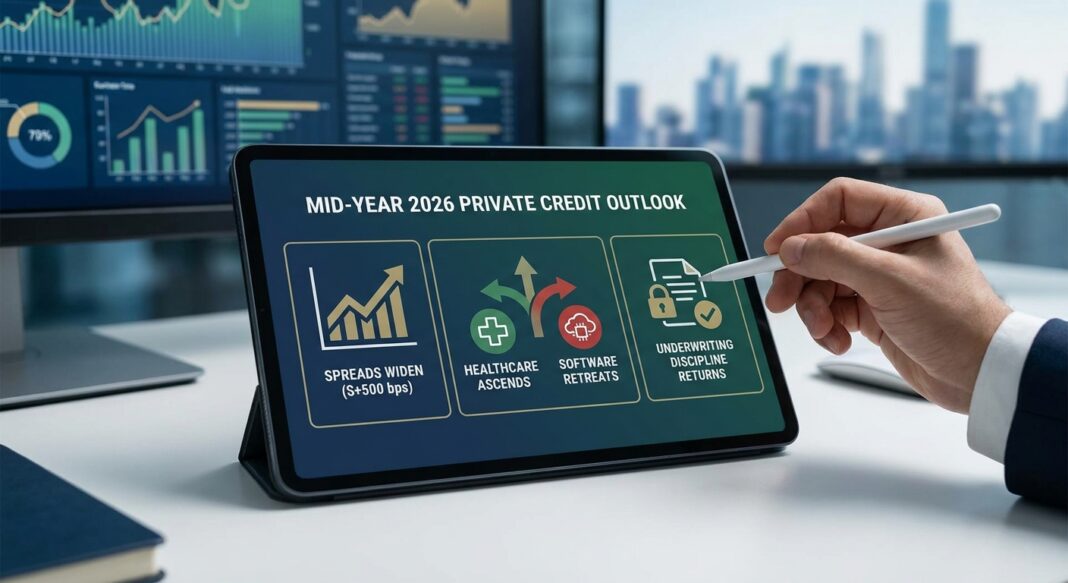
Yet the headline risk belies a constructive underlying dynamic for disciplined lenders. The market has reset in a more lender-friendly direction, Lord Abbett’s 2026 Midyear Outlook concludes: a view supported by spread widening back toward the SOFR+500 context, improved documentation standards, and a supply-demand balance that now favors capital providers with dry powder. More transactions to finance, less capital competing aggressively for each transaction, and greater ability to negotiate price and structure have collectively improved the setup for new loans, even as portfolio stress from 2021–2022 vintage exposures increases dispersion across managers. The second half of 2026 will be defined less by macro beta and more by manager skill in sector selection, covenant discipline, and cash flow underwriting.
Quantitative Market Snapshot
Key Market Metrics: As of Q2 2026
| Metric | Current Value (Q2 2026) | Prior Period (Q4 2025 / Q1 2026) | Source |
|---|---|---|---|
| Middle Market Unitranche Spreads | ~S+475–S+550 bps (standard); S+500 context broadly | Mid-400 bps context (YE 2025) | Hamilton Lane, April 2026; VRC Q2 2026 |
| 3-Month Term SOFR | 3.69% (June 2026) | 3.68% (March 2026) | VRC Q2 2026 Report |
| 5-Year U.S. Treasury Yield | ~4.23% (June 2026) | 3.92% (March 2026) | VRC Q2 2026 Report |
| Q2 2026 Direct Lending Volume | $29.2B across 138 transactions (through June 22) | $74.1B across 217 deals (Q1 2026) | PitchBook LCD, Q2 2026 Wrap |
| Private Credit H1 2026 Fundraising | $262B raised in H1 2026 (+30% YoY) | ~$201B H1 2025 (implied) | The Credit Crunch, July 2026 |
| Fed SLOOS: Bank C&I Tightening (Large & Mid-Market Firms) | +8.1% net tightening (Q2 2026) | Tighter standards reported across Q4 2025 / Q1 2026 | Federal Reserve FRED / SLOOS, May 2026 |
| LTM Leveraged Loan Default Rate (Issuer Count) | 1.36% (Feb 2026), below 10-yr avg of 1.71% | Distressed ratio rose to 8.89% (Feb 2026) from ~4–5% range in 2025 | Hamilton Lane, citing LCD/Pitchbook, April 2026 |
| First-Lien Loan Fair Market Value | 98.8% of cost (Q1 2026) | Stable; marginal softening from prior years | Heron Finance State of Private Credit Q2 2026 |
The rate backdrop remains firmly higher-for-longer. Market expectations continue to reflect a higher-for-longer rate environment, with the forward curve broadly flat as of June 2026, per VRC’s Q2 report. Expected yields increased by approximately 50 basis points during the second quarter, reflecting a continued upward shift in the forward SOFR curve. The Federal Reserve’s April 2026 SLOOS registered a net 8.1% of large domestic banks tightening standards for commercial and industrial loans to large and middle-market firms, a structural condition that continues to redirect borrowers toward private lenders. Banks reported tighter lending standards and basically unchanged demand for commercial and industrial loans to firms of all sizes, and also reported tighter standards for all categories of NDFI loans over the past year, the Fed’s April 2026 SLOOS confirmed.
Sector Analysis: Healthcare Ascends, Software Retreats, Energy and Defense Gain Traction
Healthcare: The New Dominant Sector
The most consequential sector rotation of 2026 has been the displacement of software by healthcare at the top of institutional lending league tables. Healthcare has claimed the top spot in institutional loan issuance for the first time since 2015, accounting for 14% of volume so far in 2026, according to PitchBook LCD. In the private credit market specifically, since the year began, the healthcare sector surpassed technology, which is dominated by software, to take the largest share of new deals by count. Structural drivers are compelling: demographic tailwinds, non-cyclical revenue models, and a well-understood risk profile relative to AI-disrupted software businesses. Lender appetite in healthcare is reinforced by high-profile deals: a $1.2 billion refinancing for Caris Life Sciences priced at S+500, led by Blue Owl and Blackstone, exemplifies the kind of tightly priced, sponsor-backed deal defining the sector’s 2026 activity.
Software: Repricing and Selective Withdrawal
Software’s fall from grace has been swift and well-documented. More than half of respondents to LCD’s Private Credit Market Sentiment Survey are actively reducing their allocation to the sector, either modestly or significantly. The trigger was a dual shock: AI-driven concerns about business model disruption and concentrated BDC exposure to pre-profit ARR businesses originated during the 2019–2022 zero-rate era. A record $25 billion of software-sector loans now trade below the distress threshold of 80 cents on the dollar, per Morningstar LSTA data. Critically, lenders that remain active in software are demanding structural protections: tighter covenants, wider spreads, and in some cases, fresh sponsor equity as a precondition for amend-and-extend transactions. Cash flow-based lenders focused on deeply entrenched, mission-critical offerings with long-term contracts and lower loan-to-values will be better positioned, Hamilton Lane notes, drawing a sharp line between durable and vulnerable software credits.
Aerospace, Defense, Energy, and Industrials: Rising Stars
Beyond the software-to-healthcare rotation, 2026 has been marked by a broad-based diversification of issuance, with seven of the top 10 sectors by volume increasing their share relative to both 2025 and their 10-year averages. Energy and aerospace/defense are standouts, with both sectors running meaningfully above historical norms. The geopolitical environment, including elevated oil prices following the Strait of Hormuz disruption, has simultaneously pressured energy-intensive credits and created underwriting opportunities in defense and infrastructure. U.S. utilities are increasingly engaging with private credit providers as they prepare for significant capital investment programs tied to infrastructure build-outs and rising power demand, S&P Global Market Intelligence reported, signaling a structural expansion of private credit’s mandate beyond middle-market corporate lending. Office CRE, by contrast, continues to face tightening appetite, with private credit appetite for office assets diminishing relative to other property and infrastructure-linked segments.
Implications for Borrowers, Operators, and Institutional Investors
What This Means for Borrowers and Operators
The era of covenant-lite, borrower-friendly structures is receding. Spreads ground tighter, leverage moved higher, and loan documents often became more flexible in the 2022–2025 period, but that pendulum has now reversed. Borrowers in software and energy-intensive sectors should anticipate not only wider spreads but stricter maintenance covenant packages, including FCCR thresholds (typically requiring ≥1.20x coverage on a maintenance basis) and tighter net leverage definitions. While 84.4% of new-issue spreads of LBOs financed in the direct lending market priced below S+550, spread pricing will likely tick up 25–50 basis points, particularly for deals that are lower in quality or in difficult-to-finance sectors, per PitchBook’s Q1 2026 survey cited by Capstone Partners. Companies with solid free cash flow generation, demonstrated FCCR headroom above 1.25x, and credible AI-resilience narratives will access capital at superior terms. Those with PIK-heavy structures, 2021-vintage leverage, or AI-exposed models should begin proactive dialogue with lenders well ahead of maturity dates.
What This Means for Institutional Investors and Lenders
The fundraising environment reflects bifurcation rather than retrenchment. Private credit managers raised $262 billion in H1 2026, 30% more than last year, with the growth entirely driven by Q2, when managers raised $173 billion. However, capital is concentrating sharply at the top: the number of sub-$1 billion fundraises fell 40% year-on-year, and the capital raised by those funds declined 30%. For allocators, the key governance question is vintage and sector composition. Debt/EBITDA ratios have been stable, with no material upward drift, and loan-to-value ratios remain conservative across segments, Heron Finance’s Q2 2026 benchmark report confirms, indicating the broad portfolio is not overleveraged. But stress is concentrated in 2021–2022 vintages and software-related exposures, where higher borrowing costs, weaker fundamentals, and AI-related disruption are contributing to increased use of restructurings and liability management strategies, VRC notes. The FSB’s May 2026 vulnerability report flags heightened regulatory scrutiny of bank-to-private-credit interconnections, a systemic risk channel that institutional allocators must now incorporate into due diligence frameworks.
Forward-Looking View: H2 2026 and Beyond
The second half of 2026 is likely to be defined by dispersion, between sectors, between vintages, and between managers. New deal demand together with a large refinancing wave is expected to gradually overtake private credit supply, creating an imbalance that allows lenders to preserve discipline, strengthen terms, and capture the illiquidity premium to public markets, Morgan Stanley Investment Management projects. The BDC maturity wall (23 of 32 rated BDCs carry unsecured debt maturing in 2026, totaling $12.7 billion) adds near-term technical pressure. Meanwhile, credit secondaries fundraising is up 6x year-on-year, creating a new liquidity layer that is beginning to reprice market dynamics. Direct lending’s addressable market continues to expand structurally: direct lending now matches the broadly syndicated loan market at $1.5–2 trillion in size and is forecast to reach $3 trillion by 2028, per Cleary Gottlieb. For disciplined lenders entering H2 2026, the combination of wider spreads, a higher base rate, improved documentation, and a sector rotation away from AI-disrupted credits represents the most favorable new-deployment environment in several years.
Key Market Insights for Bond Capital Clients
- Spread Reset Is Real and Durable: Middle market unitranche spreads have moved from mid-400s bps at year-end 2025 back to the S+500 context, with software-sector new issuance demanding 75–100 bps premiums above standard levels. The higher-for-longer SOFR environment (3.69% in June) translates to all-in yields that remain deeply attractive relative to public credit benchmarks, where high-yield OAS has compressed to approximately 285 bps, a historically thin risk premium relative to the private credit illiquidity premium.
- Healthcare Is the Structural Lender Rotation Trade of 2026: Healthcare has displaced software as the #1 sector by new deal count in private credit for the first time since 2015 (14% of institutional loan issuance YTD). Operators and sponsors in specialty healthcare, healthcare IT, and outsourced services should find deep and competitive lender pools in H2 2026, with pricing in the S+450–S+500 range for quality credits.
- Bank Tightening Extends Private Credit’s Structural Opportunity: The Fed’s April 2026 SLOOS confirms a net 8.1% of large domestic banks are tightening C&I standards for large and mid-market firms, and banks have tightened all terms on NDFI loans over the past year. This structural bank retrenchment, amplified by Basel IV implementation, continues to expand the addressable market for non-bank lenders, particularly in energy infrastructure, utilities, and industrials.
- Underwriting KPIs Are the New Alpha Signal: FCCR, net leverage, and cash-on-cash coverage ratios are increasingly the differentiating variables in deal selection. Lenders are stress-testing FCCR at 100 bps rate shocks, scrutinizing EBITDA add-backs (which can represent 30%+ of adjusted earnings), and tightening incurrence covenant thresholds. Borrowers should model FCCR coverage at no less than 1.25x under base-case assumptions, with meaningful cushion under downside scenarios, especially in floating-rate, highly leveraged structures.
- Capital Concentration Demands Manager Due Diligence: H1 2026 saw three times as many $10B+ private credit funds as in H1 2025, while sub-$1B fundraises fell 40% by count and 30% by capital. Allocators must distinguish between mega-manager scale advantages and genuine underwriting discipline. Non-accrual rates, PIK utilization, 2021–2022 vintage concentration, and software sector exposure remain the four critical portfolio health indicators heading into H2 2026.


