
Leverage Stories & Insights | Real Deal Case Study
The Story: A Brokerage Built on Acquisitions Faces a Reckoning
In 2021, PCF Insurance Services, a Lindon, Utah-based insurance brokerage founded by Peter C. Foy, completed a management buyout that vaulted the company into a new category of ambition. Armed with a growth-by-acquisition strategy and the backing of private equity minority investors including HGGC and Blue Owl, PCF went on a tear. By 2024, it had rebranded as Trucordia, ranked #19 on Business Insurance's Top 100 Brokers, and was managing over $8 billion in premium volume across more than 200 offices in approximately 40 states. The company had 5,000-plus employees and had completed 22 acquisitions in 2024 alone.
But the brokerage's explosive roll-up had a structural cost. Each deal added complexity, not just to operations, but to the cap table. By mid-2025, Trucordia's balance sheet carried a large unitranche debt facility and a fragmented ownership structure populated by minority investors who had accumulated stakes across multiple funding rounds. The governance picture was messy. The leverage picture was heavy. And the company (despite its scale and growth trajectory) needed to evolve its financial architecture if it wanted to compete at the very top of the insurance brokerage market.
The question facing CEO Felix Morgan and CFO Brandon Gray was deceptively simple: How do you fix the capital structure of a $5+ billion business without triggering a sale you're not ready for?
The Decision: Structured Equity Over an Exit
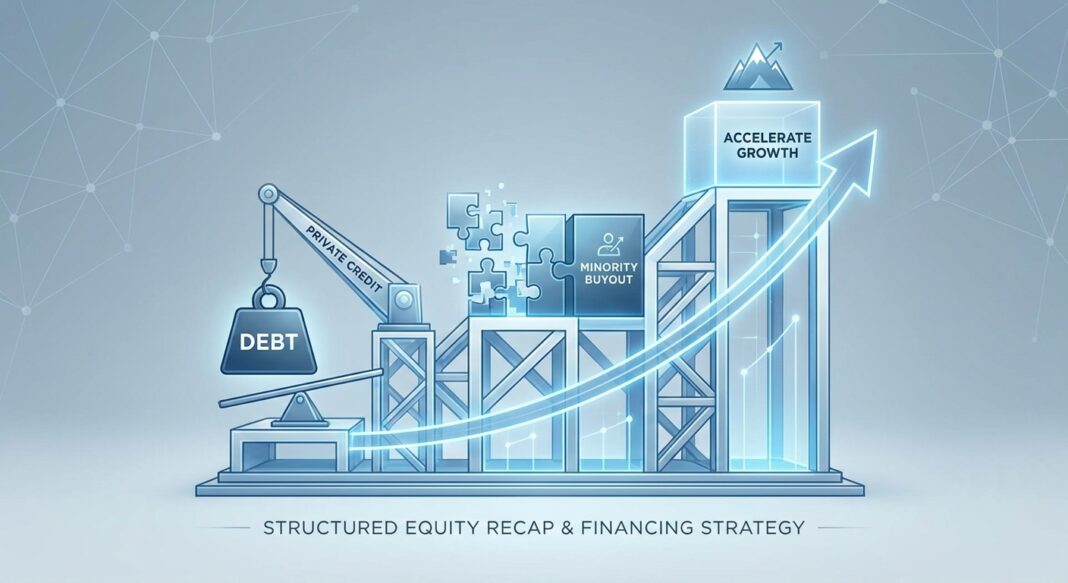
In June 2025, Trucordia announced one of the most instructive recapitalization deals of the year. The company would receive a $1.3 billion strategic investment from Carlyle's Global Credit platform: not a buyout, not a sale, and not a traditional bank refinancing. Simultaneously, the company executed a refinancing package comprising a $1.94 billion first lien term loan B and a $548 million second lien term loan B, arranged with Blue Owl Capital, plus a $400 million revolving credit facility. The proceeds replaced Trucordia's existing unitranche debt with a more cost-efficient multi-tranche structure.
The Carlyle structured equity investment served a dual purpose: it reduced Trucordia's leverage relative to equity, and it funded the repurchase of equity interests held by minority investors, simplifying governance in a single transaction. S&P Global Ratings estimated Carlyle would hold approximately 49% of Trucordia post-close, a meaningful but non-control stake that left the management team firmly in the driver's seat. The transaction valued Trucordia at $5.7 billion, up from a $4.7 billion valuation at the time of the prior Carlyle preferred equity investment in 2023.
Crucially, this was not a conventional private equity deal with a five-year exit clock and GP/LP misalignment baked in. Carlyle's strategy, executed through its Global Credit platform, explicitly targets “highly structured and privately negotiated solutions across the capital structure” for founder, family, and management-owned businesses, with a focus on long-term value creation, not fund cycle exits. For Trucordia, that distinction mattered enormously.
"The investment from Carlyle will reduce Trucordia's leverage, fortify our balance sheet, and enhance our financial flexibility."
Brandon Gray, CFO, Trucordia (June 2025)
The Outcome: What the Structure Made Possible
The immediate effects were structural and strategic. The refinancing from a unitranche facility to split first-lien/second-lien term loans improved Trucordia's cost of capital: unitranche debt, while flexible, typically carries a blended rate premium relative to layered senior/junior structures of equivalent risk. With all-in new-issue direct lending yields falling to approximately 9.3% in 2025 (down from 10.5% in 2024), the timing of the refinancing captured a meaningful rate compression window.
On the governance side, the minority buyout, funded through the Carlyle capital, eliminated the coordination costs and misaligned time horizons that come with a fragmented cap table. What had been a complex investor syndicate was replaced with a cleaner, two-party ownership structure: management/founders and one sophisticated institutional partner with aligned long-term incentives.
The counterfactual matters here. Had Trucordia pursued a traditional private equity sale to repair the capital structure and buy out minorities, it would have likely triggered a control change, a PE hold-period clock, and the attendant pressure to optimize for a five-to-seven-year exit. The structured equity recap, by contrast, preserved operational continuity and management authority, allowing CEO Felix Morgan to remain focused on Trucordia's "Ascend" growth strategy and pursue further acquisitions at a more deliberate pace. As Morgan noted publicly, M&A had shifted from being about scale to being about driving value into the organization, a nuance that only matters if you actually control the timeline.
The contrast with the overleveraged PE playbook is instructive. Consider the $45 billion 2007 LBO of TXU Corp. by KKR, TPG, and Goldman Sachs, financed with over $40 billion in debt, which ultimately filed the largest corporate bankruptcy in U.S. history after commodity prices shifted against the thesis. Excessive leverage, with no flexibility to adapt, is the enemy of operational durability. Trucordia's 2025 recap moved in the opposite direction: using structured equity to reduce leverage rather than pile it on, buying time and flexibility rather than extracting it.
The Lessons: A Framework for Builders Who Want to Stay Builders
The Trucordia deal is a microcosm of a structural shift that is reshaping how growth companies think about capital. Private credit markets are increasingly offering tools that founders and operators never had access to before: not just debt, but hybrid capital, structured equity, and bespoke solutions that sit between traditional lending and control-transfer equity.
1. The cap table is a strategic asset. Fragmented minority ownership creates governance drag and misaligned liquidity expectations. A structured recap that rationalizes the ownership table, even if it means bringing in one large institutional partner at a non-control stake, can unlock more operating freedom than staying with a complex syndicate.
2. Debt type matters as much as debt quantum. Trucordia's move from unitranche to a split first/second-lien structure improved cost efficiency without requiring a change of control. Understanding the pricing dynamics between loan structures (and the refinancing windows they open) is a skill operators often underinvest in.
3. Private credit is no longer just for LBOs. The market is seeing strong demand from founder and management-owned businesses looking to recapitalize without selling. Companies navigating transitions (ownership changes, governance simplifications, or acquisition-driven balance sheet complexity) are increasingly finding that privately negotiated solutions offer flexibility that syndicated markets and traditional PE simply cannot match.
4. Timing the rate cycle is real alpha. With direct lending spreads falling from 716 basis points in March 2023 to 544 basis points by year-end 2025, the refinancing arbitrage available to well-positioned borrowers has been substantial. Companies that proactively managed their debt maturities during this window locked in meaningfully lower cost of capital.
5. The exit clock is optional. The most dangerous feature of traditional PE capital is not the cost, it's the timeline. Growth businesses with compounding acquisition pipelines need partners whose incentives align with duration, not with fund vintage cycles. Structured equity from credit-focused platforms increasingly offers that alignment, making it a genuinely different product than control equity from a buyout fund.
Key Insights
- Structured equity recapitalization can simultaneously deleverage a balance sheet, simplify governance, and provide minority investor liquidity, without triggering a sale. Trucordia's $1.3B Carlyle deal is a live proof of concept.
- Valuation step-ups reward patience: Trucordia grew from a $4.7B valuation (2023 Carlyle preferred round) to $5.7B at the June 2025 recap, a 21% increase, without a change of control or dilutive equity round.
- Rate compression windows are finite. All-in direct lending yields fell from ~10.5% in 2024 to ~9.3% in 2025. Operators who refinanced in this window captured meaningful interest savings; those who didn't are now watching that window narrow.
- The TXU cautionary tale still applies: Over $40 billion in debt financing on a commodity-linked business with no hedging destroyed one of the largest LBOs in history. The line between leverage as a tool and leverage as a trap is drawn by cash flow visibility and structural flexibility, not by deal size.
- Private credit is structurally democratizing the recap market. What was once only available to large public companies or PE-backed platforms (bespoke hybrid capital, structured equity, multi-tranche refinancings) is now accessible to founder-led businesses with $50M+ EBITDA. The market has permanently expanded the toolkit.
Decision Framework: Should You Recap or Sell?
| Factor | Lean Toward Recap | Lean Toward Sale/Equity |
|---|---|---|
| Business stage | Compounding, mid-growth, acquisition pipeline intact | Mature, peak valuation, growth decelerating |
| Ownership structure | Complex cap table, minority buyout needed | Clean structure, ready for institutional handoff |
| Debt position | Overlevered but cash-generative; refinancing available | Debt-free or low leverage, equity round is additive |
| Operator intent | Founder/management wants to retain control and timeline | Founder is exit-ready; aligned with PE hold period |
| Rate environment | Spreads compressing; refinancing creates savings | Rising rate environment; equity cheaper than debt |


