
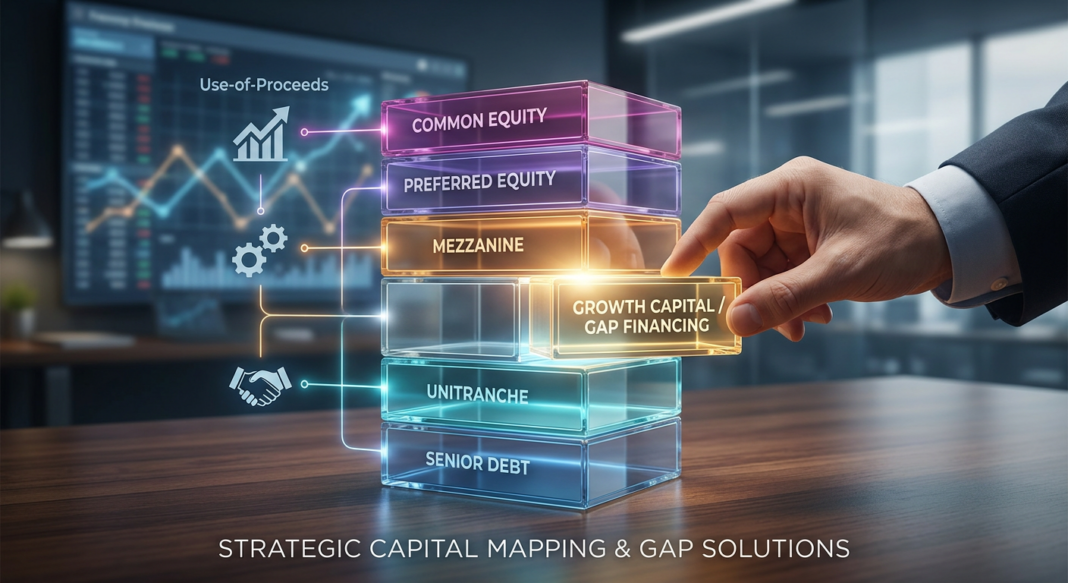
The Capital Challenge Nobody Prepares For
A company has found product-market fit, is generating $3–10 million in annual recurring revenue, and has a clear plan: hire a sales team, enter two new markets, and close a bolt-on acquisition. The plan is credible. The unit economics work. But the financing architecture is broken.
The founder calls the bank, the bank wants three years of EBITDA profitability and hard assets as collateral. The founder calls a Series A growth equity fund; they want explosive growth metrics, a 25% ownership stake, board seats, and a liquidation preference. Neither option fits. The company is stuck in what practitioners call the “gap capital zone”: past the point of seed risk, but not yet scaled enough for the cheapest institutional capital.
This gap is structural. You need $2M to hire three sales reps and double revenue, but raising a Series A for that amount signals weakness to institutional investors, so you’re stuck. Growth capital fills that gap. The companies that navigate this zone efficiently, matching funding instrument to specific use-of-proceeds, compress their cost of capital and protect their ownership. Those that don’t end up either over-diluted or under-funded.
This article is a practitioner’s guide to quantifying the gap, mapping it to the right layer of the capital stack, and executing the process that closes the financing.
Stage Definition: The Growth-Stage Capital Challenge
For the purposes of this framework, the growth stage begins when a company has proven product-market fit and is now solving a different problem: how to scale a business model it knows works. Growth stage capital is a structural choice that shapes how a company scales, deploys capital, and manages execution risk.
Seed capital bets on potential. Series A bets on market domination. Growth capital bets on proven unit economics at scale. That distinction is more than semantic; it defines the correct financing instrument.
Typical Use-of-Proceeds at This Stage
Use-of-proceeds determines structure. The four most common growth-stage capital deployments, and their corresponding structural implications, are:
- Working Capital Expansion: Scaling headcount, inventory, or receivables to support contracted revenue growth. Low-risk use-of-proceeds with high predictability. Best suited to asset-based or revolving credit facilities.
- Sales & Marketing Acceleration: Funding customer acquisition ahead of cash recovery. Revenue predictability matters. Best suited to revenue-based financing or venture debt with warrant coverage.
- Bolt-On Acquisitions: Buying competitors or complementary businesses to expand market share or product suite. Cash-flow leverage required. Best suited to unitranche or senior-plus-mezzanine structures.
- Bridge to Profitability or the Next Round: Extending runway 12–24 months to hit a valuation-inflecting milestone without a full equity raise. Best suited to venture debt or convertible notes.
The single most common structuring error at this stage is applying an equity instrument to a working capital or revenue-acceleration need, deploying the most expensive, most dilutive capital for the least risky use-of-proceeds.
The Cost-of-Capital Spectrum: From Banks to Equity
The capital stack remains the foundation of how companies are financed, a hierarchy of capital ranked from lowest risk (and lowest cost) to highest risk (and highest return). At its core, this reflects how founders structure debt versus equity in a more dynamic financing environment.
For growth-stage companies, the relevant spectrum spans five layers:
1. Bank Senior Debt (Cost: ~7–9% all-in)
Traditional bank revolvers and term loans remain the cheapest source of capital but carry the strictest access requirements. Banks require demonstrated EBITDA profitability, tangible asset collateral, and robust historical financials. For most growth-stage companies, bank debt is available only for working capital revolvers secured against receivables or inventory, not for growth investment. Covenant packages include both financial maintenance tests (quarterly leverage and coverage tests) and operational restrictions.
2. Asset-Based Lending (Cost: ~8–10% all-in)
ABL facilities are sized against a borrowing base of eligible receivables, inventory, and equipment rather than EBITDA. This makes them accessible to companies with strong asset values but limited earnings history. ABL is purpose-built for working capital cycles but unsuitable for acquisition financing or R&D investment.
3. Unitranche / Direct Lending (Cost: ~9.3–11.3% all-in before OID)
Unitranche debt is a single-tranche acquisition loan that combines what would otherwise be senior debt and mezzanine/sub debt into one instrument with one lender and one credit agreement. Total leverage typically runs 4–6x EBITDA, with a blended interest rate of 8–11% (SOFR + 500–700bps in 2026) under a single covenant package and a single intercreditor relationship.
The unitranche market grew from roughly $20 billion in annual issuance in 2015 to over $200 billion in 2025 as direct lenders displaced traditional bank syndication for sub-$1 billion EBITDA borrowers. For growth-stage companies with $3M+ EBITDA seeking acquisition financing or significant capex investment, unitranche has become the default institutional solution.
4. Mezzanine / Junior Capital (Cost: 12–20% total return)
Mezzanine debt is a hybrid financing solution positioned between senior debt and equity, offering growth capital with flexible terms and equity kickers. It typically sits between senior debt and equity in a company’s capital structure, offering lenders higher yields of 12–20% in exchange for subordinated positioning and greater risk. Structurally, it often includes regular cash interest payments, sometimes with a Payment-in-Kind (PIK) component that allows interest to accrue rather than be paid in cash, plus equity warrants or conversion rights that provide additional upside potential.
Mezzanine is the right instrument when a company has exhausted its senior debt capacity and needs to bridge the gap to equity, typically to fund an acquisition or a capital-intensive expansion that would otherwise require full equity dilution.
5. Preferred Equity / Growth Equity (Cost: 18–30%+ required return)
Preferred equity and institutional growth equity are the most expensive and most dilutive form of growth capital. According to Carta’s State of Private Markets data, median dilution in 2025 sits at approximately 19.5% for seed rounds and 18% for Series A rounds, actually higher than the peak of 2021, reflecting a market where capital has become more expensive and investors are demanding more ownership for the risk they take on.
Growth equity is the correct instrument only when the business model requires capital that cannot be serviced as debt, pre-profitability companies or those investing in R&D with uncertain payback timelines.
Structural Deep-Dive: The Growth-Stage Unitranche + Mezzanine Layer
For growth-stage companies executing bolt-on acquisitions or material expansions, the most efficient mid-market capital structure in 2026 is a unitranche term loan supplemented by a delayed-draw term loan (DDTL) facility, with mezzanine used only to fill the remaining gap between senior debt capacity and required deal size.
Illustrative Term Sheet: $40M Acquisition Financing for a $80M EV B2B Software Company
| Component | Amount | Pricing | Key Terms |
|---|---|---|---|
| Revolving Credit Facility | $5M | SOFR + 475bps | Asset-backed borrowing base; 3-year term; 0.5% unused fee |
| Unitranche Term Loan | $28M | SOFR + 600bps (~9.5% all-in); 2% OID | 6-year term; bullet repayment; 102/101/par call protection; single maintenance covenant (max leverage 5.5x stepping to 4.5x by year 3) |
| Delayed-Draw Term Loan (DDTL) | $7M | SOFR + 625bps; 1% commitment fee | Available 18 months post-close for add-on acquisitions; same covenant package as TL; pro forma leverage test at draw |
| Mezzanine / PIK Note (if needed) | $5–8M | 11% cash + 3% PIK; warrants for 3–5% of equity | 5-year term; bullet repayment; subordinated to unitranche; incurrence-only covenant package |
| Equity Contribution | $35–42M | Common or structured preferred | Sponsor or management rollover; target 40–50% of total capitalization |
The Mechanics of PIK in the Mezzanine Layer
PIK is the critical cash-preservation tool in the mezzanine layer. With PIK interest, you don’t pay cash right away: instead, the interest amount is added to the total loan balance, causing the principal to grow over time. Partial PIK structures (for example, 4% cash plus 6% PIK on a 10% total coupon) are especially common in mezzanine deals, splitting the difference between current cash service and balance sheet growth.
The compounding effect of PIK must be modeled explicitly. By year five, a $50 million mezzanine position at 11% PIK compounds to roughly $84 million of outstanding principal. The company’s cash interest burden looks manageable because only the senior debt shows up, but the total debt is growing quietly in the background. Operators must stress-test PIK accretion against exit timing scenarios before committing to PIK-heavy structures.
Payment-in-kind (PIK) usage has risen notably in private credit in recent years, with public BDCs now receiving an average of 8% of investment income via PIK. Once limited to mezzanine and subordinated debt, PIK is increasingly appearing in senior secured loan documentation, a broad-based increase suggesting that borrowers are increasingly struggling under higher interest burdens. This market signal matters: widespread PIK adoption is a late-cycle indicator that borrowers should monitor carefully.
Equity Kickers: Warrants and the True Cost of Mezzanine
Mezzanine debt has three defining structural features: its subordinated and unsecured position, its option for Payment-in-Kind (PIK) interest, and its equity kicker, almost always in the form of stock warrants. Equity kickers typically represent warrants or conversion rights providing equity upside of 3–8% of the loan amount, subordinated behind senior debt but ahead of equity in liquidation.
Every warrant granted to a mezzanine lender dilutes existing common equity. In a successful exit, the mezzanine lender’s equity kicker reduces the return available to the PE sponsor and management team, a cost that must be weighed against the benefit of reduced upfront equity contribution. The correct framing: warrants are not a free feature. They are deferred equity dilution, and they must be priced into the cost-of-capital comparison at close, not at exit.
Covenant Architecture: Maintenance vs. Incurrence in 2026
Covenant design is a material negotiation point, not boilerplate. The difference between a maintenance and incurrence regime can determine whether a lender has intervention rights during a performance trough, and therefore the degree of operational control a borrower retains.
Maintenance covenants require the borrower to satisfy specified financial tests (typically leverage ratios, interest coverage ratios, or fixed-charge coverage ratios) at regular intervals, usually quarterly. A maintenance covenant violation occurs automatically when the borrower’s financial performance deteriorates below the threshold, regardless of whether any other event has occurred.
Incurrence covenants, by contrast, restrict the borrower from taking specified actions (such as incurring additional debt, paying dividends, or making acquisitions) unless the borrower satisfies the relevant financial test at the time of the proposed action. The economic distinction is significant: maintenance covenants provide continuous monitoring through periodic testing and create tripwires that force renegotiation when borrower performance deteriorates, while incurrence covenants constrain only affirmative borrower actions and do not trigger intervention during passive deterioration.
The market divide is sharp and consequential: in the broadly syndicated loan market, approximately 90% of new loans in 2024 remained covenant-lite, continuing borrower-friendly documentation trends. However, private credit lenders have maintained firmer positions on covenant inclusion, particularly for mid-market transactions.
For growth-stage borrowers accessing private credit, expect at least one financial maintenance covenant in private credit deals under $50 million EBITDA, most commonly total leverage ratio tests with cushions above closing leverage. The covenant cushion (the headroom between the closing leverage multiple and the test threshold) is a critical negotiation variable. A 30% cushion is standard; borrowers should push for 35–40% to absorb integration costs and one-time charges during the growth phase.
A notable 2025–2026 dynamic: to stay competitive, many private credit funds are now providing “covenant loose” terms. While covenant loose loans typically have at least one maintenance financial covenant such as a quarterly tested leverage ratio, the cushions set are so generous that it would be unlikely to ever be triggered. Borrowers should understand the difference between covenant-lite and covenant-loose, the latter still carries technical trigger risk during distress.
The Gap Capital Playbook: Quantify, Prepare, Run the Process
Step 1: Quantify the Gap with Precision
The gap capital need must be defined with use-of-proceeds specificity, not as a round number. A lender underwrites a capital request against a concrete deployment plan, not a general growth narrative. The correct framework:
- Define the specific investment: What is being funded? Headcount? A specific acquisition target? A geographic expansion? Each has a different risk profile and lender appetite.
- Model the cash return on the capital: How much incremental revenue or EBITDA does the investment generate, and over what timeline? A $5M investment that adds $2M EBITDA in 18 months supports a very different debt structure than a $5M investment with a 4-year payback.
- Calculate the maximum serviceable debt: Run a conservative DSCR (Debt Service Coverage Ratio) calculation at 1.2x minimum coverage. This sets the ceiling on how much debt the business can structurally carry, and therefore defines how much of the gap must be filled with more expensive junior capital or equity.
- Size the gap: Total capital needed minus maximum senior debt capacity equals the gap. The gap is filled from the next most efficient layer of the stack: mezzanine first, then preferred equity, then common equity.
Step 2: Prepare the Materials
Growth-stage borrowers compete for lender attention against established middle-market businesses with longer track records. The materials package must compensate for the shorter operating history with quality of analysis and transparency of projections. A complete lender package includes:
- CIM (Confidential Information Memorandum): Business overview, market dynamics, competitive positioning, management team, and historical financials. Focus on the quality and predictability of revenue (ARR, churn, NRR) not just top-line growth.
- 3-Statement Financial Model: At minimum, a 5-year integrated P&L, balance sheet, and cash flow projection with clearly labeled assumptions. Include a base case, downside case (20% revenue miss), and stress case (40% revenue miss). Lenders underwrite to downside, not base.
- Use-of-Proceeds Schedule: Line-item mapping of how every dollar of capital is deployed. This is the most important document in the package; it tells the lender whether the capital creates the cash flow needed to service the debt.
- Covenant Compliance Analysis: Pro forma covenant headroom under each case at each quarterly test date for the first 3 years. Demonstrates management’s understanding of the covenant structure and builds lender confidence in financial discipline.
“We’ll hire more salespeople” isn’t a plan. Growth capital providers want detailed ROI projections per dollar deployed. The applications that close show exactly how $500K becomes $2M in new ARR within 18 months.
Step 3: Run a Structured Process
The process architecture determines negotiating leverage. Borrowers who approach a single lender for a bilateral deal will receive worse terms than those who run a structured, competitive process, even if they ultimately close with one provider.
- Identify 6–10 lenders by instrument: Map lenders by the specific instrument needed: direct lending for unitranche, mezzanine funds for junior capital, BDCs for small-cap unitranche, banks for the revolving facility. Dominant players in the LMM unitranche space include Ares Capital, Blue Owl Capital, Antares Capital, Twin Brook Capital Partners, Apollo Global Management’s direct lending arm, Carlyle Direct Lending, Golub Capital, and Monroe Capital.
- Issue an NDA + teaser simultaneously to all targets: Launch to all prospective lenders on the same day to create competitive tension and a defined timeline.
- Set a first-round IOI deadline (2–3 weeks): Collect Indications of Interest. Compare not just headline pricing but structure: OID, prepayment schedules, DDTL availability, covenant cushions, and amendment fee structures.
- Advance 3–4 lenders to full diligence and term sheet: Competing term sheets compress pricing and improve structure. A single competing term sheet, even one the borrower does not intend to accept, can move a primary lender on spread or OID by 25–50bps.
Execution speed is a genuine competitive advantage of direct lending: private credit can close within four weeks while bank deals may require 6–8 weeks for syndication. In time-sensitive acquisition situations, that speed premium can justify 50–100bps of additional spread.
Negotiation Guidance: The Five Structural Levers That Move the Deal
Once terms are on the table, borrowers should prioritize five structural variables in order of long-term cost impact:
1. OID and Upfront Fees
Unitranche loans typically carry 2–3% OID at funding. On a $50M loan, that means the borrower receives $48.5M but owes $50M of principal. The OID functions as upfront yield to the lender and amortizes over the loan life, on a 6-year loan, 2% OID equals roughly 33bps of annualized yield premium. Negotiating OID from 2.5% to 1.5% on a $30M unitranche saves $300K in proceeds at close. Push OID down before fighting on spread, lenders often concede OID more readily than headline margin.
2. Prepayment Schedule
Standard unitranche prepayment schedule in 2026 is 102/101/par over years 1, 2, and 3 respectively. Some lenders push for a 103/102/101/par schedule on more competitive deals; others accept 102/101/par. If refinancing is a realistic scenario within 2 years (for example, if the company plans to access the BSL market after a rating or scale milestone) negotiating a soft call (penalty only on voluntary prepayments, not M&A-driven repayments) matters materially.
3. Covenant Cushion and EBITDA Definition
The covenant test level and the definition of EBITDA used to calculate compliance are not fixed. Push for: (a) a 35–40% cushion over closing leverage at day one; (b) an EBITDA definition that includes 12 months of pro forma benefit from acquisitions and cost-out initiatives; (c) equity cure rights, the ability to inject equity to cure a covenant breach up to 2 times over the loan life without triggering a default.
4. DDTL Availability and Terms
For companies executing buy-and-build strategies, the Delayed-Draw Term Loan is often worth more than the headline unitranche. Many facilities include DDTLs of 0.5x–1.0x EBITDA for acquisitions or capital expenditures, available for 12–18 months. Negotiate the commitment fee (target below 1%), the draw condition (incurrence leverage test rather than a pro forma maintenance compliance), and the availability window (push for 24 months, not 12).
5. Warrant Coverage and Equity Kicker Terms (Mezzanine)
If the borrower elects to prepay the mezzanine instrument, the agreement should clarify whether make-whole or call protection applies to both the debt and the warrant value. Failure to define these aspects with specificity is a frequent source of post-closing disputes, especially when the company outperforms and the equity kicker becomes valuable. Negotiate warrant coverage as a percentage of fully diluted equity (target 3–5%, not 8–10%), specify a clear strike price methodology, and define warrant expiration tied to loan maturity rather than perpetual rights.
Current Market Terms: Data Points for Q2 2026
The following market benchmarks reflect conditions as of Q2 2026:
- Unitranche spread: Base rate at approximately 4.3% (3-month Term SOFR as of Q2 2026), with credit spreads of 500–700bps over SOFR for typical lower middle-market unitranche. Upper middle-market sponsored deals price tighter at SOFR + 425–475bps per Capstone Partners’ Winter 2025 data.
- OID: Average OID on private credit deals ran around 2–3% of funded principal in H1 2024, with compression toward 1.5–2.0% in 2025 as competition from the BSL market intensified.
- Mezzanine total return target: Investors typically target 12–20% total returns from mezzanine debt, comprising an 8–12% cash coupon, 2–4% from PIK accretion, 2–8% from equity participation, and 1–3% from origination and structuring fees.
- Private credit AUM: Global private credit assets under management reached approximately $2.1 trillion in 2025, up from $1.5 trillion a year earlier, providing significant deployment capacity across instruments.
- Refinancing dynamics: In Q1 2025, companies refinanced at least $7.3 billion of direct lending deals with syndicated loans, the second-highest quarterly figure for refinancing from private credit to syndicated loans in at least four years, with borrowers achieving an average spread saving of 263 basis points. Growth-stage borrowers should evaluate BSL refinancing as a 24–36 month exit from initial private credit facilities once scale qualifies.
Key Takeaways
- Match instrument to use-of-proceeds first. Working capital needs belong in revolvers and ABL. Revenue-acceleration needs belong in venture debt or revenue-based financing. Acquisitions belong in unitranche or senior-plus-mezz structures. Applying equity to serviceable-debt needs is the most expensive structuring mistake at the growth stage.
- Unitranche dominates mid-market acquisition financing in 2026, with all-in pricing of 9.3–11.3% before OID for typical LMM credits. The premium over a senior-plus-mezz stack is approximately $600–800K over a 5-year hold on a $50M financing, meaningful but frequently justified by execution simplicity.
- PIK is a cash-management tool, not a free lunch. A $50M mezzanine position at 11% PIK compounds to approximately $84M by year five. Model PIK accretion under multiple exit timing scenarios before accepting a PIK-heavy structure, delayed exits transform manageable PIK into a balance sheet liability that can block clean sales processes.
- Covenant design is a material economic variable. Private credit deals in 2026 retain maintenance covenants that the BSL market has largely abandoned. Negotiating a 35–40% cushion, a borrower-favorable EBITDA definition, and equity cure rights can be the difference between an amendable performance trough and a technical default.
- Run a competitive process every time. Even a single competing term sheet moves the primary lender on OID and spread. Direct lending markets are competitive, $2.1 trillion of AUM needs to be deployed, and borrowers with quality credits hold more leverage than they typically exercise.


