
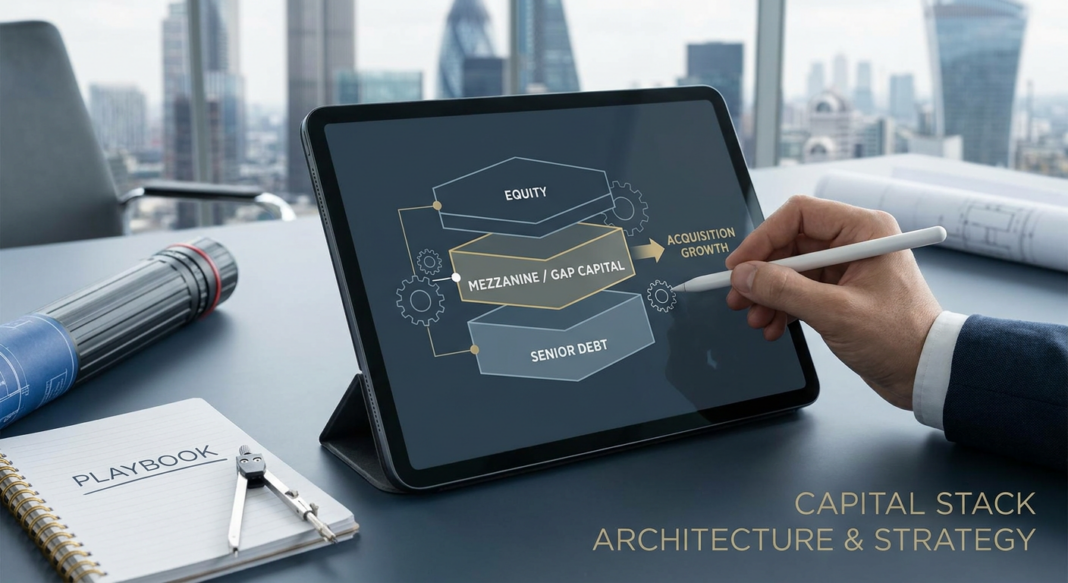
The Stage, The Gap, and the Structure That Bridges Them
There is a precise moment in a company’s life when conventional financing stops working cleanly. The business has moved past the venture-scale risk profile (it has revenue, it has EBITDA, it has a defensible market position) but it hasn’t yet matured into the kind of predictable free cash flow that broadly syndicated lenders underwrite against. It wants to acquire. It wants to scale. And the senior bank is willing to lend, but only so far.
This is the growth-stage acquisition problem: a company targeting a $15M to $50M transaction where senior debt covers 60–70% of the capital need, equity is expensive and dilutive, and the remaining gap demands a structured solution that sits between those two extremes. That solution is mezzanine financing, subordinated debt with equity features designed specifically for the risk and return profile of this moment in a company’s trajectory.
This article maps the full capital stack for that scenario, explains how to quantify the gap, and walks through the tactical playbook for preparing, running, and closing a mezzanine process.
Step 1: Map the Capital Stack Before You Call a Single Lender
The capital stack for a growth-stage acquisition doesn’t start with a term sheet. It starts with a sources-and-uses model that forces clarity on every layer of the transaction. As the vcbeast.com framework for sponsor-led deals makes clear, the best capital stack is not the one with the most leverage or the lowest equity check; it is the one that matches cash flow durability, lender appetite, seller needs, and governance constraints into a structure that can close and still support the business after day one.
For a $15M acquisition at a growth-stage company, the stack typically resolves into four layers:
- Senior Secured Debt (Banks or ABL lenders): Priced at SOFR + 250–375 bps. Typically sized to 2.5–3.5x EBITDA. Available to companies with proven cash generation and clean collateral. This is the cheapest capital in the stack but also the most constrained, lenders set the ceiling, not the borrower.
- Mezzanine / Subordinated Debt: Priced at 12–16% all-in, often structured as a cash pay coupon (8–10%) plus PIK (4–6%), with warrant coverage of 2–5% of fully diluted equity. Sits junior to senior debt but senior to preferred and common equity. This is the gap capital layer.
- Seller Note or Earnout: Typically 5–10% of transaction value, subordinated to all institutional debt. Bridges valuation disagreements and reduces upfront cash requirements. Terms should support post-close alignment, not paper over a price dispute.
- Equity (Sponsor or Management Rollover): The residual claim. Absorbs first loss. Expected to carry the highest return expectation and the longest duration. Dilution here is permanent, structure everything else to minimize how much of this layer is required.
The arithmetic is straightforward. Total target enterprise value: $15M. Senior debt capacity: $8M. Seller note: $1M. Equity gap to close: $6M. That $6M is the mezzanine mandate. As the Bond Capital use-of-proceeds framework outlines, modelling three stack scenarios (pure mezz, pure preferred equity, and a blended structure) against post-close FCCR (target: above 1.20x) and total leverage (target: below 5.0x EBITDA) clarifies the optimal path before any provider conversation begins.
Step 2: Understand the Mechanics Before You Negotiate the Price
Mezzanine debt is not a single instrument. It is a family of structures that sit on a spectrum between pure debt and preferred equity. Understanding each component is essential before entering any negotiation.
PIK vs. Cash Pay Split
Payment-in-kind (PIK) interest accrues to principal rather than being paid in cash, preserving liquidity in the early years of a leveraged acquisition when debt service pressure is highest. A typical mezz structure in the current market carries a 12–14% total coupon, split approximately 8% cash pay and 4–6% PIK. The PIK toggle provision (where the borrower can elect to PIK in any given period subject to conditions) provides additional operating flexibility but commands a pricing premium from lenders.
Warrant Coverage
Warrant coverage gives the mezz lender the right to purchase a defined percentage of fully diluted equity at a pre-agreed strike price. Standard coverage in the current middle market runs 2–5% of equity, with strike prices set at or near the acquisition valuation. Warrants are the lender’s equity upside, the mechanism by which a subordinated debt provider earns a blended return (debt yield plus equity participation) that compensates for its subordinate position in the capital structure.
Covenant Package
Mezzanine covenants are typically incurrence-based rather than maintenance-based; they are triggered by specific actions (new debt issuance, distributions, material asset sales) rather than requiring the borrower to maintain financial ratios on a quarterly test basis. This is materially less restrictive than a bank facility, which almost always includes maintenance covenants on leverage, interest coverage, and fixed charge coverage. Borrowers negotiating mezz terms should push hard to align covenant packages with incurrence mechanics and resist maintenance tests bleeding in through the subordinated layer.
Step 3: Run the Gap Capital Playbook With Institutional Discipline
Gap capital providers (mezzanine funds, BDCs, family offices, and credit opportunity funds) underwrite to a different thesis than senior lenders. They want EBITDA accretion visibility, a defensible strategic rationale, and a clear exit pathway. As the Bond Capital acquisition financing framework describes, the materials package must include four components to be taken seriously at the institutional level:
- Use-of-Proceeds Memo: A precise document mapping how the acquisition creates EBITDA accretion, with line-item specificity on revenue synergies, cost rationalization, and integration timeline.
- Three-Year Integrated Financial Model: Sensitivity-tested across revenue growth and margin compression scenarios. The base case should be credible, not aspirational, lenders triangulate against their own sector comps.
- Management Presentation: Strategic rationale, competitive moat, and exit pathway. This is where management demonstrates operational credibility alongside financial fluency.
- Clean Cap Table: Pre- and post-transaction ownership, with full disclosure of existing debt facilities, subordination arrangements, and any existing warrant or option overhang.
Process discipline matters as much as materials quality. Approach four to six gap capital providers simultaneously, not sequentially. Competitive tension compresses pricing and loosens structural terms. Issue a structured term sheet request with a defined response deadline. Require each provider to specify: cash pay vs. PIK split, warrant coverage percentage and strike mechanics, covenant package type, board observer rights, and change-of-control provisions. Evaluate all five dimensions together. As the Bond Capital framework notes, a 14% all-in facility with 3% warrant coverage and maintenance covenants may impose more real constraint on the business than a 16% preferred equity instrument with no covenants and no scheduled amortization.
Step 4: Negotiate Structure, Not Just Price
The most common error growth-stage borrowers make in mezzanine negotiations is optimizing for headline coupon while conceding on structural terms that impose far greater long-term cost. The negotiation framework should prioritize in the following order:
- PIK Toggle Flexibility: Push for the right to elect PIK in any period without requiring lender consent, subject only to no-default conditions. This is the most valuable operating flexibility in the structure.
- Warrant Strike and Coverage: Negotiate strike price at current valuation (not a discount) and limit coverage to 2–3% if the all-in yield is above 13%. Warrants are equity dilution, treat them with the same discipline as a primary equity round.
- Covenant Architecture: Resist any maintenance covenant in the mezz layer. If the senior lender already imposes maintenance tests, the mezz layer must be incurrence-only to avoid redundant trip wires.
- Prepayment Provisions: Standard mezz facilities carry call protection for years one through three (typically a 3-2-1 step-down). Push for a make-whole period no longer than 18 months, with a par call thereafter. This preserves the ability to refinance at lower cost as the business matures.
- Board Observer vs. Board Seat: Most institutional mezz providers request a board observer right, not a board seat. Concede the observer right, it’s information access, not governance control. Resist any provision that converts observer rights to full board representation upon a covenant event.
The capital stack, as the re-cap.com structural framework observes, is not just money. It is behavior, constraints, and relationships that shape how the company operates for years. Strong structures are designed for the downside; they preserve optionality when reality diverges from the model, and they avoid terms that turn a 20% revenue miss into a technical default.
Key Takeaways
- 🏗️ Build the stack before calling lenders. A complete sources-and-uses model (including senior debt, mezz, seller notes, and equity) defines the gap capital quantum before any provider conversation begins.
- 📐 Model three stack scenarios. Pure mezz, pure preferred equity, and a blended structure each produce different FCCR, leverage, and dilution outcomes. The optimal structure maintains coverage above 1.20x FCCR, total leverage below 5.0x EBITDA, and equity dilution below 15% of common.
- ⚙️ Understand PIK, warrants, and covenants as a system. Each component of a mezz structure interacts with the others. A low coupon with high warrant coverage and maintenance covenants may be more expensive in real terms than a higher-coupon, incurrence-only structure with limited equity participation.
- 🔄 Run a competitive process with institutional discipline. Four to six providers approached simultaneously, with a structured term sheet request and defined response deadline, produces materially better terms than a sequential search under time pressure.
- 🎯 Negotiate structure, not just price. PIK toggle flexibility, warrant strike mechanics, covenant architecture, prepayment provisions, and board rights each carry long-term operational consequences that outweigh short-term pricing differences of 50–100 basis points.


