
The Story: Fourteen Years, One Company, and a Question That Kept Coming Up
Note: The following company profile is a Hypothetical Scenario constructed to illustrate real structural mechanics and market conditions. All market data, statistics, and transaction benchmarks cited are sourced from public reports and industry research and are linked below.
Marcus had spent fourteen years building Ironwood Field Services, a B2B environmental compliance and inspection firm serving industrial clients across the Southeast. The business was not glamorous. It ran on long-term service contracts, a fleet of vans, and a team of 120 technicians who knew every OSHA citation form by number. But it was profitable, deeply, predictably profitable.
By 2024, Ironwood was generating $9.2 million in EBITDA on $38 million in revenue, carried no meaningful debt, and renewed more than 90% of its contract base annually. Marcus owned 100% of the equity. His accountant, his wife, and his golf partners all told him the same thing: “You should sell.”
But Marcus didn’t want to sell. He had two senior operators ready to ascend. The company was entering its most promising growth phase, a regional competitor had stumbled, and two acquisition targets had approached him. He believed Ironwood was worth far more in five years than today. What he wanted wasn’t an exit. He wanted to stop having all of his net worth tied up in a single closely held business while still running it.
This is the tension that sits at the heart of every founder’s late-stage capital decision, and it’s one the leveraged recapitalization was built to resolve.
The Decision: Two Paths, Two Very Different Futures
Marcus’s M&A advisor presented him with a straightforward menu. Option one: run a full sale process. At 6.5x EBITDA, Ironwood would fetch roughly $60 million. After taxes, transaction fees, and the standard rollover equity requirement from a PE buyer, Marcus would net somewhere between $32 million and $38 million, and would almost certainly be locked in for a 3-to-5-year hold with a new board, new reporting demands, and a clock running toward the next exit. He’d been in enough industry peer groups to hear how those stories often ended.
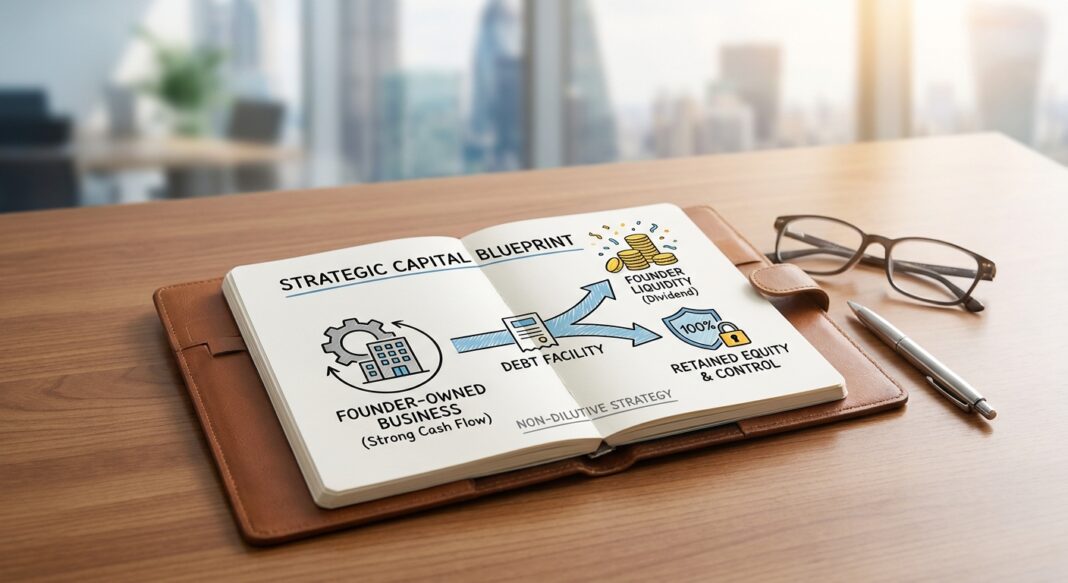
Option two was a leveraged recapitalization, a structure he’d heard about but never pursued. The mechanics were straightforward: the company borrows against its own cash flows and distributes the proceeds to the owner as a dividend, while the owner retains 100% of the equity and continues operating the business.
His advisor sketched the numbers. Ironwood had clean, recurring EBITDA of $9.2M. With no existing debt, the business could comfortably support a debt load of 3.5x EBITDA, a conservative multiple well within current market norms for a service business with its contract profile. That translated to a new senior credit facility of approximately $32 million, structured as a unitranche loan through a private credit lender at a rate of approximately SOFR + 475 bps (all-in near 9.5% at the time of structuring).
The $32 million proceeds would flow directly to Marcus as a dividend. Annual debt service would run roughly $3.0–3.4 million, leaving the business with approximately $5.8 million in post-debt-service EBITDA, still healthy, still growing. Marcus would retain 100% of the equity, remain in full operational control, and collect a life-changing check without triggering a taxable sale or ceding a seat at his own table.
He chose the recap.
The Outcome: Liquidity Today, Upside Tomorrow
Twelve months post-recap, Ironwood had closed one of its two target acquisitions, a $4.2M EBITDA tuck-in funded via incremental debt capacity unlocked by the acquired company’s own cash flows. Combined EBITDA was now tracking toward $13 million. Marcus had used a portion of his $32 million dividend to diversify personally into real estate and a diversified portfolio. His net worth was no longer a single-line item.
The counterfactual is instructive. Had Marcus sold at $60M and netted $35M post-tax, he would have received slightly more cash today, but forfeited his equity stake in a business now likely worth $80–90M on the same 6.5x multiple. The leveraged recap gave him meaningful personal liquidity while preserving the largest component of his wealth, the future enterprise value he believed in.
This isn’t just a hypothetical calculus. The macro backdrop bears it out. According to Bain & Company’s 2025 Global Private Equity Report, 30% of all companies currently in buyout portfolios have undergone some form of alternative liquidity event, with the industry raising a combined $410 billion through mechanisms including dividend recapitalizations, minority stakes, and secondaries, precisely because founders and sponsors alike are choosing to hold assets longer while still extracting interim value.
At the market level, the numbers confirm the trend. Through September 2024, year-to-date dividend recapitalization volume in the leveraged loan market reached $69.3 billion: surpassing the prior record set in 2021, according to PitchBook LCD data. And in early 2025, volume continued to accelerate: from January through mid-February 2025 alone, dividend recap volume hit $22.4 billion, a sharp jump from $14.0 billion during the same period in 2024, per analysis from Dechert LLP. Combined, 2024 and 2025 dividend recap activity totaled just under $200 billion: more than five times the combined total for 2022 and 2023, according to Moody’s data reported by Yahoo Finance.
The deals aren’t just bigger in aggregate, they’re bigger individually. Median dividend payout sizes reached $485 million in early 2025, up from $300 million in 2024 and $245 million in 2022, per PitchBook. The September 2024 recap of Belron (the windscreen repair giant backed by Clayton, Dublier & Rice and Hellman & Friedman) illustrated the upper end of the market: an €8.1 billion debt raise producing a €4.4 billion dividend to sponsors, in what was reported as the largest PE-backed dividend recapitalization ever executed.
The Lessons: When the Recap Wins, and When It Doesn’t
The leveraged recap is not a universal tool. It is a precision instrument, and its usefulness depends almost entirely on whether the business beneath the structure can reliably service the debt it takes on.
For businesses like Ironwood (high contract renewal, low capex intensity, recurring revenue, no meaningful cyclicality) the structure is a near-natural fit. The Pepperdine Private Capital Markets Report (2024) notes that lower middle market leveraged recapitalizations typically clear at 3x to 5x EBITDA in total debt, with pricing tied to prevailing senior secured rates plus a risk-based margin. That range provides a useful anchor: if your business can comfortably service 3–4x EBITDA in debt with meaningful cash flow remaining, you’re likely in the right zone.
The discipline in sizing is everything. As one credit advisory firm put it: “discipline in sizing the recap relative to the company’s EBITDA and free cash flow is what separates smart capital management from reckless financial engineering.” Owners must ask not just what they can borrow, but what the business can carry through an economic contraction, a key customer loss, or a 15% revenue miss.
There is also a more structural critique worth understanding. When PE sponsors use dividend recaps on portfolio companies, the incentive alignment question sharpens considerably. Academic research published by the NBER found that dividend recaps can have meaningful negative effects on some portfolio company stakeholders, precisely because the sponsor has already begun recouping their equity investment, which can reduce urgency to continue driving operational value. The recap-as-LP-return-mechanism, rather than the recap-as-founder-liquidity-tool, carries meaningfully different risk profiles.
For the founder-operator, however, the calculus is different. The owner stays exposed to the upside. The debt is the cost of early liquidity, not a wealth transfer to a third party. And crucially, no equity is surrendered: no board seats ceded, no liquidation preferences layered on, no PE clock ticking toward a forced exit. That alignment is real and it matters.
Finally, the market environment matters. The growth of private credit, with assets under management approaching $1.6 trillion according to Preqin, and projected to exceed $3.5 trillion by 2028 per BlackRock forecasts, has meaningfully expanded access for lower-middle-market founders who previously had no institutional debt market to tap. Non-sponsor direct lenders are now actively seeking founder-led businesses with strong cash flows, offering flexible terms and faster execution than traditional banks can provide.
Framework: Is Your Business a Recap Candidate?
- Cash flow predictability: Can you model 3–5 years of EBITDA with reasonable confidence? Recurring revenue, long-term contracts, and high customer retention are strong signals.
- Leverage headroom: Is your current balance sheet clean or lightly levered? Starting from zero debt is the strongest position for a recap.
- Debt service coverage: After the recap, does post-debt EBITDA remain above 1.5x annual interest expense, and stay there in a downside scenario?
- Operational independence: Do you want to keep running the business? The recap only makes sense if the equity you’re preserving has somewhere meaningful to go.
- Lender access: Private credit lenders are actively financing founder-owned lower-middle-market businesses, often for the first time in their capital history. The market has never been deeper.
Key Insights
- Liquidity and control are not mutually exclusive. A leveraged recap allows founders to extract meaningful personal liquidity, often $10M to $40M+, while retaining 100% of the equity and full operational authority. The two most common false choices in founder finance (sell the company vs. remain illiquid) are not the only options.
- The market is the deepest it has ever been for this transaction type. Combined 2024–2025 dividend recapitalization volume approached $200 billion, more than 5x the 2022–2023 combined total. Private credit, now approaching $1.6 trillion in AUM, has dramatically expanded lender access for founder-owned businesses that previously had no institutional debt market to tap.
- Sizing discipline is the difference between a great trade and a distressed one. Lower-middle-market recaps typically clear at 3x–5x EBITDA in total debt. Exceeding the business’s capacity to service that debt through an economic stress scenario is where recaps turn from liquidity events into liquidity crises. The structure only works when the underlying business is genuinely strong.
- The VC and PE critique is embedded in misaligned incentives, not in leverage itself. When PE sponsors lever a portfolio company to fund their own LP distributions, after already reducing their risk exposure, the alignment breaks down. When a founder uses the same mechanism to diversify personal wealth while remaining fully exposed to upside, the incentives remain tightly aligned. Same instrument, fundamentally different risk profile.
- The recap is a first step, not a final answer. For founders who believe their best exit is still three to seven years away, the leveraged recap functions as a bridge, unlocking today’s value without foreclosing tomorrow’s upside. Used correctly, it converts an illiquid, concentrated balance sheet into a diversified one, while leaving the engine of wealth creation, the operating business, fully intact and fully owned.


