
The Underwriting Question Every Lender Must Answer
Before a single covenant is set, before a leverage ratio is calculated, before a debt quantum is sized, a credit underwriter must answer one foundational question: How much of this EBITDA can I actually lend against?
In today’s private credit and leveraged lending markets, the gap between a borrower’s reported EBITDA and the earnings figure a disciplined lender will underwrite can be material. Sellers and sponsors routinely present adjusted EBITDA figures that reflect best-case assumptions, forward synergies, and a parade of “one-time” items that recur with suspicious regularity. As one legal practice note from Haynes Boone observes, lenders focus on adjusted EBITDA precisely because it should provide a clearer picture of a borrower’s ability to generate cash flows from core business activities, but only when adjustments are rigorously validated.
The stakes are high. Academic research using the 2013 Interagency Guidance on Leveraged Lending has demonstrated that non-GAAP EBITDA add-backs increase the likelihood of loan delinquency and default, and also increase the probability of a borrower experiencing a ratings downgrade. Getting the earnings base wrong does not simply affect pricing; it corrupts every downstream metric in the credit structure: leverage ratios, coverage ratios, covenant headroom, and debt sizing. This article provides a practitioner framework for building a defensible normalized EBITDA figure and avoiding the most common underwriting errors.
The Analytical Framework: The EBITDA Bridge
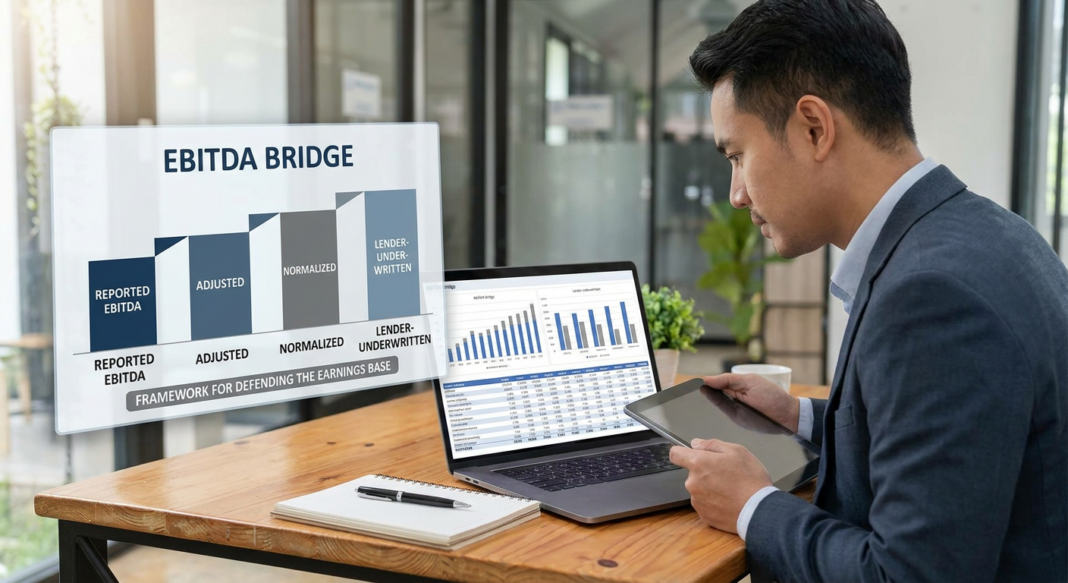
A rigorous normalization analysis requires building an explicit four-step EBITDA bridge:
- Reported EBITDA: GAAP net income plus interest, taxes, depreciation, and amortization as stated in audited or reviewed financials.
- Adjusted EBITDA: Reported EBITDA modified by removing non-recurring, non-operating, and owner-specific items that are legitimately excludable and clearly documented.
- Normalized EBITDA: The sustainable, recurring subset of adjusted EBITDA after run-rate alignment and evidence-backed pro forma considerations. This is the figure lenders ultimately underwrite.
- Lender-Underwritten EBITDA: The most conservative defensible number after the lender’s own independent review, stress haircuts on uncertain add-backs, and disallowance of items that cannot be verified.
Normalized EBITDA is a defensible estimate of a company’s sustainable, recurring operating earnings, adjusted to remove non-recurring, non-operating, and owner-specific items while reflecting a supportable run-rate for valuation and underwriting. The Quality of Earnings (QoE) analysis is the primary diligence tool used to validate this bridge, reconciling each adjustment from the general ledger to actual cash flow.
Illustrative Example: A $10M EBITDA Manufacturing Company
Reported Net Income: $3.2M
+ Interest, Taxes, D&A: $4.1M
= Reported EBITDA: $7.3M
Claimed Add-Backs (Sponsor Deck):
+ Owner compensation above market: $800K ✅ (supported by comp survey)
+ One-time legal settlement: $600K ✅ (court documents on file)
+ “Temporary” IT consulting: $550K ⚠️ (recurring for 3 consecutive years)
+ Cost savings from planned headcount reduction: $750K 🔴 (no executed plan, no severance accrual)
+ COVID-related revenue shortfall: $400K 🔴 (more than 4 years stale)
= Sponsor Adjusted EBITDA: $10.4M
Lender-Underwritten Normalized EBITDA: $8.7M
(Disallowing unverified cost savings and stale adjustments; discounting recurring consulting 50%)
Leverage Impact (at 5.0x): Sponsor sizing = $52M debt | Lender sizing = $43.5M debt
An $8.5M difference in maximum debt capacity driven entirely by add-back discipline.
Key Metrics Driven by the Normalized Earnings Base
- Total Leverage Ratio: Total Debt ÷ Normalized EBITDA, the primary sizing constraint.
- Senior Secured Leverage: First Lien Debt ÷ Normalized EBITDA, governs attachment point risk.
- Interest Coverage Ratio: Normalized EBITDA ÷ Cash Interest Expense, typically must exceed 2.0x–2.5x at close.
- Fixed Charge Coverage Ratio (FCCR): (EBITDA − CapEx − Taxes) ÷ (Interest + Scheduled Debt Service), the most rigorous cash flow test.
Lenders use the most conservative EBITDA definition because it drives debt sizing, covenants, and repayment capacity. In 2025, most core middle market transactions clear at approximately 5.0x total leverage for businesses with clean, verifiable earnings, while premium assets with stable margins may see 6.0x, but these are the exception, not the rule.
The Analysis: Walking the Bridge and Stress Testing
Step 1: Trace Every Add-Back to Source Documents
Each claimed adjustment must be traced back to general ledger entries, invoices, or legal documents. Lenders will only consider adjustments that can be clearly justified and traced back to the company’s financial statements. Items without documentary support are disallowed outright.
Step 2: Apply the Green / Yellow / Red Classification
Experienced underwriters apply a traffic light framework to proposed add-backs:
- Green-Light: Non-market owner compensation, personal expenses run through the company, duplicate vendor costs post-system migration, discontinued product lines with documented SKU elimination, one-time legal settlements with court records. These are objectively removable, documented, and not required to sustain revenue or gross margin.
- Yellow-Light: “Temporary” cost cuts without contracts, aggressive vendor renegotiations not yet executed, growth hires treated as add-backs rather than pro forma items, and restructuring charges that appear in multiple consecutive periods. Apply a discount (typically 25%–50%) rather than full credit.
- Red-Light: Evergreen consulting fees labeled “one-time,” recurring margin “buy-downs” recast as non-recurring, structural overhead that will return post-close, and projected cost savings with no implementation plan, executed severance, or third-party verification. These are disallowed entirely.
Step 3: Reconcile to Operating Cash Flow
A normalized EBITDA figure that does not reconcile to operating cash flow is a red flag. If EBITDA is increasing but operating cash flow is not, the earnings improvement may be entirely on paper: the result of accounting changes, deferred revenue recognition timing, or aggressive accrual management rather than genuine operational improvement. Lenders must compare EBITDA to the cash conversion cycle (CCC) and track working capital trends across multiple periods.
Step 4: Run Downside Scenario Analysis
After establishing normalized EBITDA, underwriters stress-test coverage and leverage under two standard downside cases:
- Base Case Stress (−15% EBITDA): Mild revenue shortfall or margin compression. Does leverage remain below 6.0x? Does interest coverage remain above 1.5x?
- Severe Stress (−25% to −30% EBITDA): Recessionary scenario or significant customer loss. Is the borrower still FCCR-positive? Can the business service cash interest without covenant breach or liquidity crisis?
Lenders start with normalized EBITDA and then test operating cash flow, the cash conversion cycle, and leverage and coverage metrics under downside cases. A credit that cannot sustain a 20% earnings haircut without breaching covenants should receive heightened scrutiny at the initial underwriting stage.
Industry Standards: What Institutional Lenders Look For
Add-Back Caps and Structural Protections
Because expansive add-backs can materially affect leverage outcomes, institutional lenders often impose caps, including shared caps expressed as a percentage of EBITDA, on projection-based or nonrecurring adjustments. These caps prevent the incremental layering of speculative add-backs that inflates the denominator of every leverage calculation. In private credit transactions, time-based restrictions are also common, limiting how far back or forward pro forma adjustments can reach.
A real-world illustration of add-back negotiation under distress: Sleep Number Corporation’s Twelfth Amendment to its credit agreement (filed with the SEC in 2025) expanded the definition of Consolidated EBITDA to include add-backs for cost actions implemented but not yet fully realized in trailing twelve-month results, subject to approval by the administrative agent. This illustrates both how EBITDA definitions are actively negotiated in restructuring contexts and why lenders must be vigilant about creeping definitional flexibility at origination.
Credit Performance Data: The Cost of Getting EBITDA Wrong
📊 Data Box: Default Rates & Credit Performance (2024–2026)
- Leveraged loan default rate (Moody’s): Projected to reach 7.5% by end-2025 and peak at 7.9% in Q1 2026, nearly double the 3.4% historical long-term average. (Source: Moody’s Ratings, July 2025)
- Distressed exchanges: Accounted for approximately 64% of all defaults in the first half of 2025, roughly the same pace as full-year 2024, which itself was the highest annual share on record. (Source: Moody’s Ratings, 2025)
- Senior direct lending credit losses: Senior direct lending has sustained annualized losses of 0.4% since 2017, compared to 1.1% for leveraged loans and 2.4% for high-yield bonds, underscoring the protective value of structural seniority and covenant discipline. (Source: Cliffwater CDLI-S / Morgan Stanley Investment Management, data through 2024)
- Private credit default rate (2025): U.S. private credit defaults rose to approximately 5.5% in Q2 2025, up from 4.5% in Q1 2025. (Source: CoinLaw / Moody’s composite data, 2025)
- Research finding on add-backs: Academic analysis using the 2013 Interagency Guidance demonstrates that marketing EBITDA including add-backs is generally not a reliable indicator of future EBITDA, and that companies tend to overestimate debt repayment, understating future leverage and credit risk. (Source: University of Houston / Bauer College of Business, “EBITDA Add-backs in Debt Contracting”)
Common Red Flags in Borrower-Presented EBITDA
- Add-backs growing faster than revenue: If normalized EBITDA is expanding faster than top-line revenue, the earnings improvement is being manufactured in the adjustments, not in the business.
- “One-time” items that appear in every period: Restructuring charges, integration costs, and legal settlements that appear across 3+ trailing twelve-month periods are not one-time by any reasonable standard.
- Large synergy assumptions without execution history: Pro forma cost savings require not just a plan but demonstrated prior execution of similar initiatives. Buyers increasingly expect a demonstrated history of successful execution before crediting synergies.
- Aggressive revenue recognition: Deferred revenue, unbilled receivables, and ASC 606 timing changes can inflate EBITDA without corresponding cash generation. Always align deferred revenue, unbilled receivables, and performance obligations across the QoE, net working capital analysis, and earn-out metrics.
- EBITDA-to-cash conversion below 80%: A healthy operating business should convert at least 80 cents of every EBITDA dollar into operating cash flow over a trailing twelve-month period. Persistent shortfalls signal either working capital deterioration or earnings quality concerns.
Underwriting Checklist: EBITDA Normalization Diligence
Documentation Requirements
- ☐ Three years of audited or reviewed financial statements (GAAP basis)
- ☐ Trailing twelve-month (TTM) management accounts reconciled to most recent audit
- ☐ Independent Quality of Earnings (QoE) report from a credentialed accounting firm
- ☐ General ledger support for each claimed add-back (invoice, legal document, payroll record)
- ☐ Cash flow statement reconciliation: EBITDA → Operating Cash Flow → Free Cash Flow
- ☐ Working capital bridge (monthly data, at minimum three years)
Add-Back Diligence Questions
- ☐ Has this item appeared in prior periods? If yes, how many consecutive years?
- ☐ Is the add-back operationally necessary to sustain current revenue and margin levels?
- ☐ For cost savings add-backs: Is there a signed vendor contract, executed separation agreement, or third-party validation?
- ☐ For pro forma hires: Are there offer letters, start dates, and productivity ramp assumptions?
- ☐ What percentage of total normalized EBITDA is represented by add-backs? (Industry benchmark: lenders become more skeptical when add-backs exceed 15–20% of the normalized figure)
- ☐ Does the seller’s QoE align with the lender’s independent accounting review? What are the discrepancies?
Structural Protections to Negotiate
- ☐ Cap non-recurring add-backs as a percentage of trailing EBITDA (commonly 10–15%)
- ☐ Restrict pro forma synergy add-backs to items with a 12-month sunset
- ☐ Define EBITDA in the credit agreement with reference to the lender’s approved normalization schedule
- ☐ Require quarterly EBITDA certification reconciled to GAAP financials
- ☐ Set maintenance covenant (leverage or FCCR) with meaningful headroom of 25–35% from close levels
Key Takeaways
- Normalized EBITDA is not a number; it is a process. Every add-back must be traced to source documentation, tested for recurrence, and independently validated before it earns a place in the underwriting model.
- The EBITDA definition governs everything downstream. Leverage ratios, covenant headroom, debt capacity, and interest coverage all flow from the earnings base. A $1M error in normalized EBITDA at a 5.0x multiple translates into a $5M mispricing of credit risk.
- Academic evidence confirms that inflated add-backs increase default risk. Research shows that loans underwritten to aggressive non-GAAP EBITDA figures exhibit higher rates of delinquency, default, and ratings downgrades over the loan’s life.
- Senior secured discipline is the single most effective risk mitigant. Senior direct lending has sustained annualized credit losses of just 0.4% over the 2017–2024 period, compared to 2.4% for high-yield bonds, a gap driven primarily by structural seniority and disciplined EBITDA underwriting, not luck.
- The current credit environment demands heightened vigilance. With leveraged loan default rates projected to reach 7.9% in early 2026, nearly double their long-term historical average, and distressed exchanges at record levels, the quality of the earnings base underwritten at origination is the most consequential risk management decision a credit team makes.


