
Why Lenders Obsess Over What They Don’t Lend
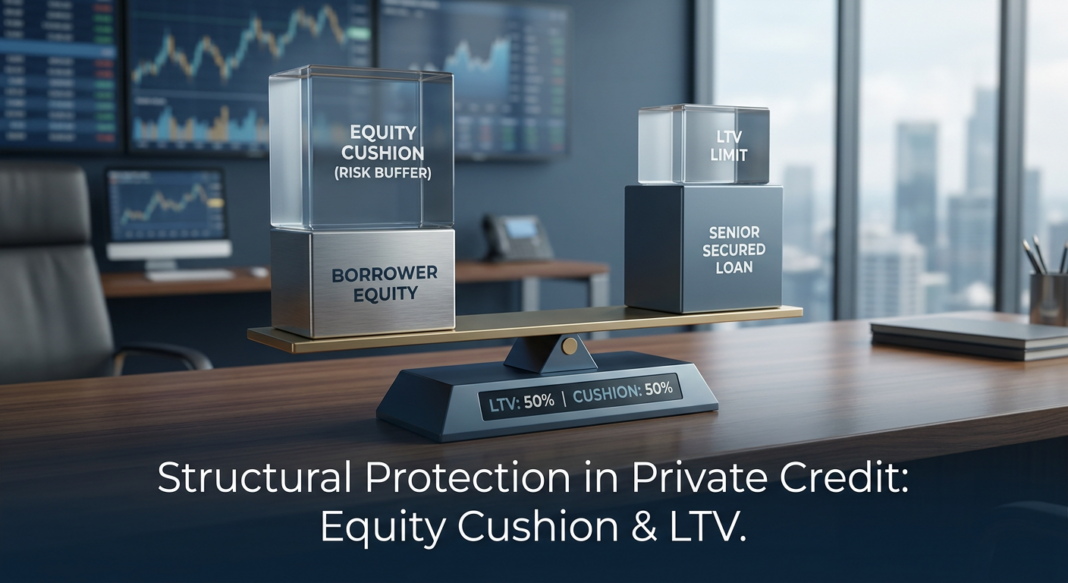
In private credit, one of the most counterintuitive truths is this: a lender’s safety doesn’t come from the interest rate they charge; it comes from the capital they refuse to lend. The gap between what a borrower’s business is worth and what a lender is willing to advance is called the equity cushion, and it is the single most important structural protection in senior secured direct lending.
For investors evaluating private credit funds, understanding equity cushion mechanics explains why senior secured loans can generate equity-like returns with significantly lower loss rates. For business owners seeking growth capital, understanding how lenders calculate this cushion determines how much debt they can access, and at what cost.
This article breaks down how equity cushions work, how lenders size them using loan-to-value (LTV) ratios, and why today’s private credit market has made these protections more critical than ever.
The Concept: Equity Cushion as a Loss Absorber
When a private credit lender makes a senior secured loan to a business, they do not lend 100% of the company’s enterprise value. Instead, they lend a fraction, typically 40% to 60%, leaving the remaining value as a buffer funded by equity (usually contributed by a private equity sponsor or the business owner themselves).
This buffer is the equity cushion. It represents the percentage of enterprise value that would have to be destroyed before the lender loses a single dollar of principal.
Loan-to-Value (LTV) is the inverse expression of the same idea:
- LTV = Total Debt ÷ Enterprise Value
- Equity Cushion = 1 − LTV
A deal with a 50% LTV has a 50% equity cushion. That means the company’s value must fall by more than half before the senior lender faces any impairment. The equity investors, who sit below the lender in the capital stack: absorb all losses first. This subordination is what gives senior secured lenders their structural advantage over every other class of capital in the business.
How It Works: A Concrete Example with Numbers
Imagine a private equity sponsor acquires a manufacturing business for $100 million in total enterprise value. The deal is financed as follows:
- Senior Secured Term Loan: $50 million (from a private credit lender)
- Sponsor Equity: $50 million (from the PE fund)
The LTV at close is 50%, meaning the equity cushion is also 50%.
Now consider two scenarios over a five-year hold period:
Scenario A, Business Underperforms: The company loses a major customer. Enterprise value falls 30%, from $100M to $70M. The lender is still fully covered, their $50M loan is backed by $70M of value. The equity investor has lost $20M of their $50M stake, but the lender is unimpaired.
Scenario B, Severe Distress: A broader industry downturn cuts enterprise value by 55%, from $100M to $45M. Now the lender faces a shortfall: their $50M loan is backed by only $45M of value, a $5M impairment. Crucially, the equity investor has been entirely wiped out, absorbing the first $50M of loss, before the lender loses anything.
This is the mechanical power of subordination. The equity cushion is not just a number on a term sheet; it is a structured loss-absorption sequence built directly into the deal’s architecture.
Lenders also protect themselves against value erosion over time by underwriting to EBITDA multiples rather than static asset values alone. If a lender advances 4.5x EBITDA on a business generating $10M annually, the implied debt is $45M. If EBITDA falls to $7M, the lender reassesses coverage, which is why leverage covenants (e.g., maximum debt/EBITDA of 5.5x) serve as an early-warning system before value destruction reaches critical levels.
Current Market Relevance: Why Equity Cushions Matter More in 2026
The post-2022 lending environment has made equity cushion analysis more consequential for both lenders and borrowers. Several converging forces are reshaping how cushions are sized and monitored.
According to the Federal Reserve’s Senior Loan Officer Opinion Survey (SLOOS), banks have reported tightened lending standards for commercial and industrial loans in the majority of survey periods since 2022, reducing advance rates and pushing middle-market borrowers toward private credit markets that can underwrite more complex risk, but at a price.
According to Cliffwater’s Direct Lending Index research, senior secured direct loans to middle-market companies have delivered gross yields in the range of 10%–12%+ through 2024 and into 2025, a spread premium that partly compensates lenders for liquidity risk, but is also a function of the elevated base rate environment.
According to Pitchbook’s 2025 Private Markets Annual Report, global private credit assets under management crossed $1.7 trillion in 2024, with senior secured direct lending representing the largest single strategy by deployment volume.
According to S&P LCD’s middle-market lending data, unitranche all-in pricing for sponsored transactions has generally ranged from SOFR + 500 to 575 basis points in recent deal flow: pricing that reflects both lender return requirements and the structural protections, including LTV limits, embedded in these deals.
According to Preqin’s private debt research, senior secured strategies have consistently posted lower realized loss rates than subordinated or mezzanine strategies across market cycles, empirically validating the protective value of equity cushions over time.
| Metric | Data Point | Source |
|---|---|---|
| Global Private Credit AUM | $1.7 trillion+ (2024) | Pitchbook 2025 |
| Senior Secured Direct Lending Yield | ~10%–12%+ gross (2024–2025) | Cliffwater CDLI |
| Unitranche Spread (Sponsored MM) | SOFR + 500–575 bps | S&P LCD |
| Typical Senior Secured LTV (MM Buyouts) | 45%–60% | Preqin Research |
| Bank C&I Lending Standards | Net tightening majority of periods since 2022 | Federal Reserve SLOOS |
Decision Framework: How Each Audience Should Use This
For Investors Evaluating Private Credit Funds:
- Ask for the weighted average LTV at origination across the fund’s portfolio. A fund averaging 55%+ LTV on senior secured loans is carrying meaningfully less structural protection than one averaging 45%.
- Track LTV drift: if underlying business values have declined since origination (EBITDA compression, multiple contraction), the current LTV may be materially higher than the original underwriting, even if no covenant has technically been breached.
- Compare equity cushion to loss-given-default assumptions. A 40% equity cushion provides no comfort if recovery rates in the sector are historically below 40% in distressed sales.
- Investors may consider examining how a manager’s realized loss rates compare to their stated LTV targets; this gap, or the lack thereof, is a meaningful signal of underwriting discipline over time.
For Business Owners and Operators Seeking Capital:
- Understand that lenders size loans off enterprise value, not revenue. A business generating $5M EBITDA valued at 6x ($30M EV) will typically access $13.5M–$18M in senior debt (45%–60% LTV), not a number tied to top-line revenue.
- Equity cushion requirements determine sponsor equity checks. If a private credit lender requires a 50% equity cushion on a $50M acquisition, the sponsor or owner must fund $25M in equity. Operators evaluating a leveraged recapitalization should model how much equity must remain in the business to satisfy lender LTV requirements.
- Higher-quality businesses (recurring revenue, low customer concentration, strong margins) command lower LTV requirements from lenders, meaning they can access more debt relative to value. Improving business quality is, structurally, the same as reducing borrowing cost.
Key Takeaways
- The equity cushion is the primary structural protection in senior secured private credit; it is the percentage of enterprise value that must be destroyed before a lender loses principal.
- LTV and equity cushion are two sides of the same coin. A 55% LTV means a 45% equity cushion. Every point of additional LTV narrows the lender’s margin of safety and widens the borrower’s risk exposure.
- Subordination is the mechanism that makes the cushion meaningful. Equity investors absorb losses first, in full, before senior debt is impaired; this sequencing is contractually enforced through the capital stack.
- In today’s environment, with bank lending standards still restrictive and private credit yields elevated, lenders have structural leverage to enforce tighter LTV discipline, making current vintage equity cushions among the more conservatively sized in recent memory.
- For operators, improving business fundamentals (EBITDA quality, revenue visibility, margin stability) directly increases the enterprise value against which debt is sized, expanding capital access without increasing proportional risk to lenders.


