
The Growth-Stage Financing Problem Nobody Warns You About
The scenario is more common than founders expect. You have $8M–$20M in revenue, proven unit economics, and a $15M acquisition target that would accelerate your roadmap by three years. Your bank stretches to $8M on a senior term loan. That leaves a $7M gap, and how you fill it will determine your cost of capital, your equity dilution, and your operational flexibility for the next five years.
This is the defining capital challenge of the growth stage: the business is too mature for venture equity terms, too early for broadly syndicated leveraged finance, and too acquisitive for organic cash flow alone. It demands a sequenced capital stack architecture: not a single funding call, but a deliberate layering of instruments matched to their appropriate risk, cost, and structural role. As the practitioners at bondtv.vaultai.ca frame it, navigating this requires mapping every dollar of use-of-proceeds before the first lender conversation begins.
Step 1: Map the Capital Stack from Top to Bottom
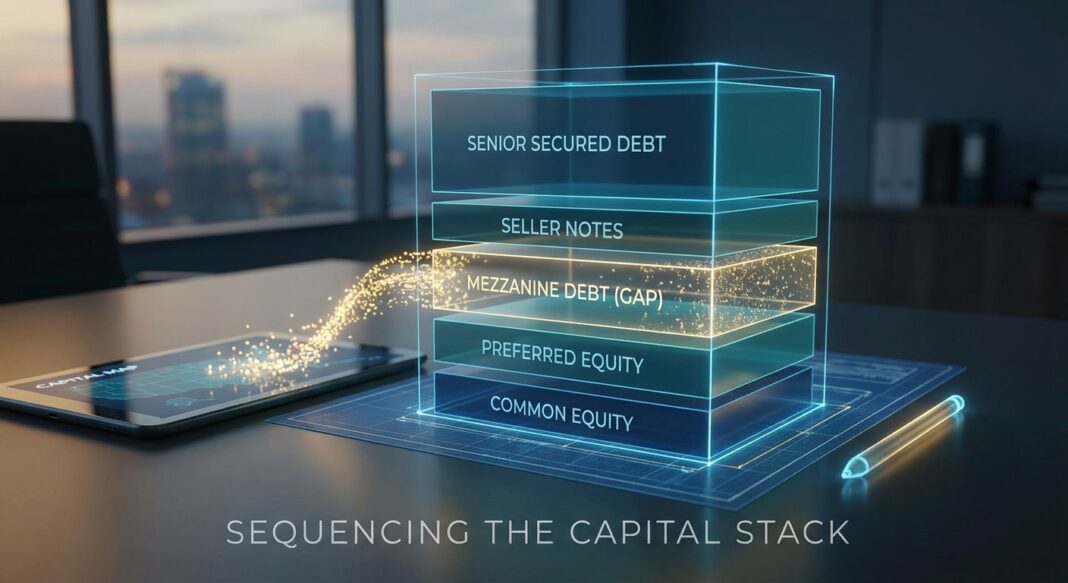
Before approaching any capital provider, operators must understand the hierarchy they are building within. The capital stack flows from lowest cost and highest seniority at the top, to highest cost and greatest flexibility at the bottom. Each layer serves a distinct function:
- Senior Secured Debt (Banks / Asset-Based Lenders): First-lien position, lowest all-in cost (typically benchmark + 250–450 bps for growth-stage borrowers), but the most restrictive. Covenants, collateral requirements, and DSCR maintenance tests define the ceiling on how much is available. In the $15M acquisition scenario, $8M in senior term debt is the starting anchor, not the finish line.
- Seller Notes / Earnouts: A negotiated deferred payment to the seller, often carrying a 5–8% coupon and subordinated to senior debt. In a $15M deal, a $1M seller note at 6% cash pay is a clean, low-friction gap filler that also keeps the seller commercially aligned through the integration period.
- Mezzanine Debt: Subordinated, unsecured or second-lien, priced at 12–18% all-in (cash pay plus PIK component), often with warrant coverage of 1–5% of fully diluted equity. Mezz fills the structural gap between what senior lenders provide and what equity investors will fund. It is expensive relative to senior debt, but it is cheaper than equity dilution at a growth-stage valuation multiple.
- Preferred Equity: No mandatory repayment schedule, no covenants, but the highest cost and greatest dilution. Preferred equity from a family office or BDC may carry a 14–18% preferred return with a liquidation preference, making it mathematically similar to mezz in cost but structurally less restrictive. As capitalxo.com notes, the cost-control-flexibility triangle governs every layer selection decision.
- Common Equity: The residual foundation. At the growth stage, issuing new common equity to fund an acquisition is typically the highest-cost path; it is dilutive at a stage where valuation multiples may not yet reflect the combined business. Common equity is appropriate as the sponsor’s co-investment layer, not as gap-filling capital.
Step 2: Quantify the Gap Before You Pitch Anyone
Systematic gap quantification is the entry requirement for any institutional capital conversation. The arithmetic is straightforward; the discipline to execute it before fundraising begins is not. Work backward from the acquisition price:
- Total enterprise value of target: $15M
- Senior debt capacity (anchored to your EBITDA and lender appetite): $8M
- Seller note (if applicable): $1M
- Remaining gap capital required: $6M
This $6M is the structural problem that demands a structured solution. Model three scenarios before approaching providers: (a) fill the gap entirely with mezzanine debt; (b) fill it entirely with preferred equity; (c) blend both. For each scenario, calculate your post-close leverage ratio, annual debt service coverage, and pro-forma equity dilution. The optimal structure maintains a Fixed Charge Coverage Ratio (FCCR) above 1.20x, total leverage below 5.0x EBITDA, and limits dilution below 15% of common equity, as the framework outlined at bondtv.vaultai.ca illustrates.
Step 3: Prepare the Materials That Institutional Providers Actually Underwrite
Gap capital providers (mezzanine funds, BDCs, family offices, and credit opportunity funds) underwrite to a different thesis than senior lenders. They are not making a collateral loan. They are making a business bet with downside protection built into the structure. Their diligence package requirements reflect that:
- Use-of-proceeds memo: A clear, one-page document showing how the acquisition creates EBITDA accretion and how each dollar of capital is deployed. Providers need to see that capital is going into value creation, not overhead.
- Integrated three-year financial model: Revenue growth, margin compression sensitivity tables, debt service waterfall, and covenant headroom analysis under a downside case. The model must include pro-forma synergies with realistic timing assumptions.
- Management presentation: Strategic rationale, competitive moat of the combined entity, and a credible exit pathway: whether that is a recapitalization, sponsor sale, or strategic acquisition.
- Clean cap table: Pre- and post-transaction ownership, existing debt obligations, and any outstanding warrants or options. Governance complexity is a diligence risk; clean it up before the process begins.
As vcbeast.com emphasizes in its capital stack design framework, a complete sources-and-uses schedule is the prerequisite to any credible financing conversation, if the uses are incomplete, the stack is fiction.
Step 4: Run the Process with Competitive Tension
Approach four to six gap capital providers simultaneously, not sequentially. Create a competitive dynamic. Issue a structured term sheet request with a defined response deadline, and require each provider to specify five things: coupon structure (cash pay vs. PIK split), warrant coverage or equity participation percentage, covenant package (maintenance vs. incurrence), board observer rights, and change-of-control provisions.
Evaluate responses across all five dimensions, not just the headline rate. A 14% all-in mezz facility with 3% warrant coverage and full maintenance covenants may be operationally more restrictive than a 16% preferred equity instrument with no covenants and no scheduled repayment, depending on your revenue visibility and integration risk. The financing cost comparison is not simply the coupon; it is the coupon plus the structural burden plus the equity cost of warrants at your projected exit multiple.
Step 5: Negotiate the Four Terms That Move the Most
Once you have competing term sheets in hand, the negotiation concentrates on four structural levers:
- PIK vs. cash pay split: Push for more PIK in years one and two to preserve integration-period cash flow. A 10% all-in structure split as 7% cash pay / 3% PIK is meaningfully better for near-term DSCR than a 10% full cash pay obligation.
- Warrant coverage: Negotiate coverage as a percentage of fully diluted equity at close, not a fixed share count. A fixed share count gets more expensive as the company grows; a percentage cap limits the provider’s upside participation to what was agreed at signing.
- EBITDA definition in covenant calculations: Ensure the covenant EBITDA calculation includes pro-forma synergies and excludes non-recurring transaction costs. A narrow EBITDA definition can manufacture covenant violations that have nothing to do with business performance.
- Call protection schedule: A 2%/1%/0% step-down over three years is market standard. For borrowers with strong EBITDA visibility, a no-call period in year one can sometimes be negotiated away entirely. Understand the prepayment economics before accepting boilerplate. As bondtv.vaultai.ca notes, every term on a term sheet has downstream consequences, model the cap table impact at three exit scenarios before signing.
Key Takeaways
- The capital stack is architecture, not a single transaction. Each layer (senior debt, seller notes, mezzanine, preferred, common equity) serves a distinct structural role and must be sized to its appropriate risk and cost.
- Quantify the gap before you pitch. Work backward from acquisition price to senior debt capacity to identify the precise quantum of gap capital needed. Model three fill scenarios and stress-test each against your FCCR and leverage targets.
- Use-of-proceeds drives underwriting. Institutional gap capital providers underwrite to value creation, not collateral. A clear use-of-proceeds memo tied to EBITDA accretion is the entry requirement for the conversation.
- Run a competitive process. Approaching four to six providers simultaneously, not sequentially, creates the negotiating tension needed to improve terms across coupon, PIK split, warrant coverage, covenants, and call protection.
- The four negotiable terms that matter most are: PIK vs. cash pay split, warrant coverage methodology, EBITDA definition in covenants, and the call protection schedule. Model the cap table at multiple exit scenarios before committing to any one structure.


