
Where You Stand in Line Is Everything
When a company borrows money, not all lenders are created equal. Some stand at the front of the repayment line. Others wait at the back. In the event of default, that position (more than the interest rate, more than the borrower’s credit score) determines who gets their money back and who absorbs the loss. This hierarchy is called the capital stack, and understanding it is the single most important concept for anyone evaluating private credit.
Whether you are an institutional investor allocating to a direct lending fund or a business owner weighing your financing options, the capital stack tells you who has priority, who carries risk, and what the true cost of each financing layer really is. In a market where pitchgrade.com estimates global private credit AUM has surpassed $1.7 trillion as of Q1 2026, knowing exactly where in the stack a given instrument sits has never been more consequential.
What the Capital Stack Actually Is
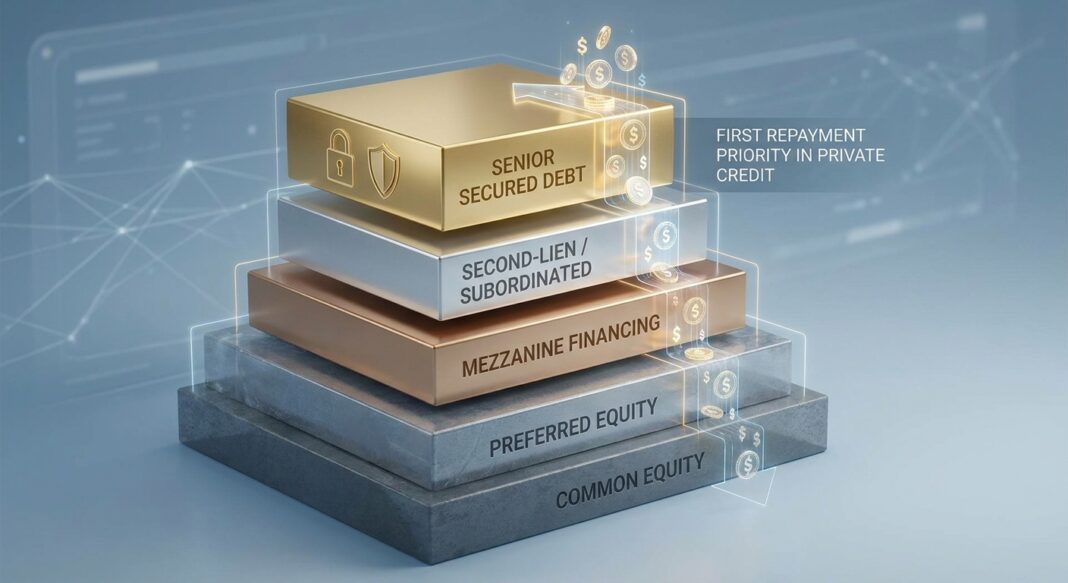
The capital stack is the ordered hierarchy of financial claims on a company’s assets and cash flows. Think of it as a waterfall: in good times, cash flows down and everyone gets paid. In a distress scenario, the waterfall runs dry before reaching the bottom, and whoever sits lowest absorbs the loss.
From top to bottom, the typical capital stack looks like this:
- Working Capital & Senior Secured Debt: First priority claim, backed by collateral (receivables, equipment, real property). Paid before all other long-term obligations.
- Unitranche / First-Lien Term Loans: A single blended instrument combining the economics of first- and second-lien debt, common in private credit transactions.
- Second-Lien / Subordinated Debt: Junior to senior secured; earns a higher coupon in exchange for absorbing losses before senior lenders.
- Mezzanine Financing: Sits between debt and equity; may carry equity warrants for additional upside.
- Preferred Equity: Has preference over common equity but is subordinate to all debt layers.
- Common Equity: Last in line; absorbs all losses first and receives residual value only after every creditor is made whole.
As bipwealth.com notes, senior secured debt is backed by collateral and holds priority over all other long-term creditors, in a liquidation scenario, senior secured lenders are first in line to recover their capital from the company’s assets.
How It Works: A Concrete Example with Numbers
Imagine a private equity sponsor acquires a manufacturing company for $100 million. The deal is financed as follows:
- $50 million: Senior secured term loan (private credit fund, SOFR + 575 bps)
- $15 million: Second-lien debt (SOFR + 950 bps)
- $10 million: Mezzanine note (14% PIK)
- $25 million: Sponsor equity
Now assume the company struggles and is sold in a distressed scenario for just $60 million. Here is how the proceeds distribute:
- Senior secured lender recovers $50 million: fully made whole.
- Second-lien lender recovers $10 million of their $15 million, a 33% loss.
- Mezzanine and equity holders receive nothing.
The senior secured lender lost nothing despite a 40% decline in enterprise value. The equity holder lost everything. This is the power of position in the capital stack, and it explains why most institutional private credit strategies concentrate on senior secured, first-lien lending rather than junior tranches.
Current Market Relevance
The structural migration of senior secured lending from banks to private credit funds is not a passing trend; it reflects permanent regulatory change. According to pitchgrade.com, Basel III capital requirements effectively require banks to hold $8–12M in Tier 1 capital for every $100M leveraged loan to a below-investment-grade borrower. After funding costs, credit losses, and overhead, bank return on equity for leveraged loans compresses to roughly 10–12%, making the business uneconomical compared to core lending franchises.
Private credit funds, unconstrained by risk-weighted asset rules, can hold the same loan and generate materially better risk-adjusted returns on deployed capital. The practical result: according to the same source, 75%+ of leveraged buyout financing in deals below $500M in EBITDA is now provided by private credit funds rather than banks.
This shift has also elevated covenant discipline. As blackstone.com highlights, private loans are typically senior secured with meaningful cushion below in the form of junior debt and equity, and the direct nature of private lending tends to produce stronger documentation and principal preservation mechanics than broadly syndicated alternatives.
For context on default performance: according to longangle.com, citing Proskauer’s Private Credit Default Index, default rates for direct lending have remained under 4% since 2021, a historically low figure that partly reflects the structural protections that senior secured positioning provides.
| Capital Stack Layer | Typical Spread (2026) | Risk Position | Source |
|---|---|---|---|
| Senior Secured (Large Cap) | SOFR + 425–500 bps | First lien, lowest credit risk | pitchgrade.com |
| Senior Secured (Middle Market) | SOFR + 500–650 bps | First lien, moderate borrower size risk | pitchgrade.com |
| Private Credit (Broad Market Share) | ~20% of leveraged credit | Displacing bank and bond market share | longangle.com |
| Direct Lending Default Rate (since 2021) | <4% | Historically low; senior security a factor | longangle.com |
Decision Framework
For Investors Evaluating Private Credit
Before committing capital to any private credit fund, investors consider one foundational question: where in the capital stack does this strategy operate? A fund marketing “private credit” could be deploying into senior secured first-lien loans, subordinated mezzanine notes, or distressed debt, three instruments with dramatically different risk profiles. As bipwealth.com observes, a subordinated debt fund and a senior secured direct lending fund are both technically private credit, but they occupy very different positions in the repayment line.
Investors evaluate: (1) lien position, first, second, or unsecured; (2) collateral quality, what assets back the loan and what are they worth in liquidation; (3) equity cushion below, how much junior capital absorbs losses before senior lenders are touched; and (4) covenant structure, what contractual protections allow the lender to intervene before a default becomes a recovery event.
For Operators Seeking Capital
Business owners evaluating financing consider the capital stack from the opposite direction: cost. Senior secured debt carries the lowest interest rate, because the lender takes the least risk. Mezzanine and equity are progressively more expensive, because those providers absorb risk first. Operators weigh the total cost of capital across each layer against their ability to service that debt from operating cash flows. Accessing private credit at the senior secured level typically means lower all-in borrowing costs than mezzanine alternatives, but may come with tighter covenants and collateral requirements that restrict operational flexibility.
Key Takeaways
- Position determines protection: In private credit, where you sit in the capital stack determines whether you recover capital in a distress scenario, not just whether the borrower is creditworthy today.
- Senior secured is the institutional standard: The majority of institutional private credit AUM is concentrated in senior secured, first-lien direct lending, reflecting the priority claim and collateral backing that structure provides.
- Bank retreat is structural, not cyclical: Regulatory capital requirements under Basel III have permanently reduced bank appetite for leveraged lending, creating durable origination opportunity for private credit funds in the senior secured space.
- Higher yield = lower stack position: Every incremental point of spread above senior secured rates reflects additional subordination risk. Investors evaluate whether that premium adequately compensates for the loss-absorption obligation it implies.
- The label “private credit” is not enough: Operators and investors alike should demand specificity (first-lien senior secured, second-lien, unitranche, or mezzanine) before drawing conclusions about risk, cost, or protection.


