
The Growth-Stage Acquisition Challenge: When Your Senior Lender Hits the Ceiling
Picture this: a founder-led professional services firm is generating $8M in EBITDA, growing at 25% year-over-year, and has identified a bolt-on acquisition at a $40M enterprise value. The company’s relationship bank will lend to 3.0x EBITDA, that’s $24M. The equity sponsor wants to contribute $8M. That leaves a $8M gap between what the bank will fund and what the deal requires. This is the defining financing challenge of the growth stage: a well-performing business trying to execute an acquisition whose capital requirement outpaces what conservative senior lenders will provide.
This gap is not an anomaly. It is structural. Mezzanine financing represents a critical component of leveraged buyout and growth capital structures, typically filling the gap between what senior lenders will provide and what equity investors wish to contribute. The question is not whether the gap exists, it almost always does, but how to quantify it precisely, map it to the right instruments, and negotiate a structure that doesn’t saddle the business with crippling debt service or unnecessary dilution.
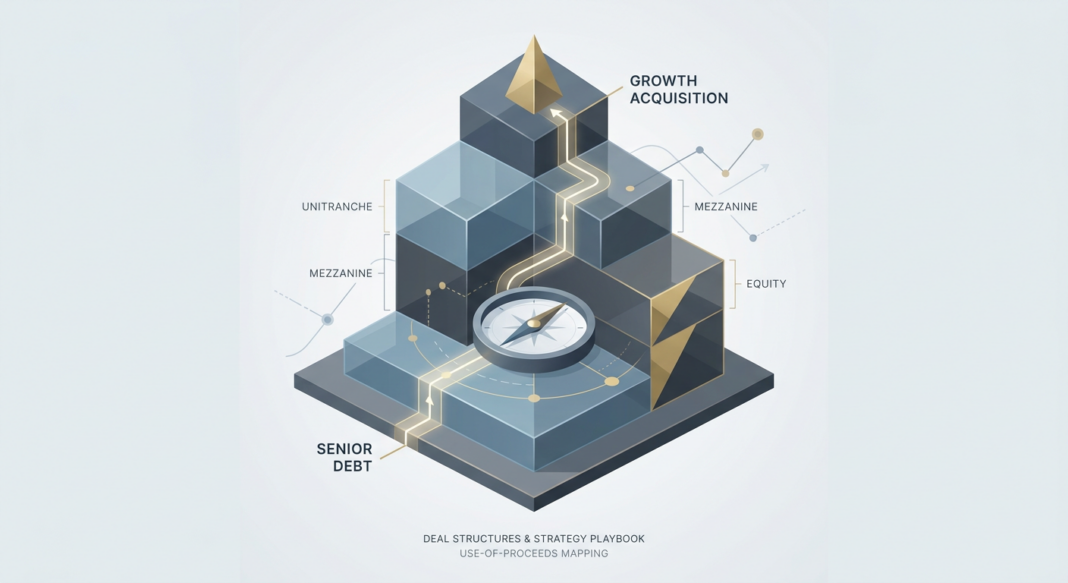
This article walks through the full capital stack available to a growth-stage company executing an acquisition: from senior bank facilities at the base to mezzanine, unitranche, and preferred equity at the top. We map each layer to its use-of-proceeds logic, explain the cost-of-capital trade-offs at each rung, and provide a tactical playbook for closing the gap.
Mapping the Cost-of-Capital Spectrum: From Banks to Equity
Understanding where you sit on the capital stack is the prerequisite for all deal structuring. Each layer of capital has a different cost, a different risk tolerance, and a different expectation of return, and each layer is appropriate for a specific use-of-proceeds profile.
Layer 1: Senior Bank Debt (Lowest Cost, Highest Constraint)
Traditional commercial banks price senior secured facilities at the tightest spreads available, typically SOFR plus 250–400 bps for well-performing middle-market companies, but they apply the strictest constraints on leverage and collateral. Most banks won’t extend a cash flow loan to companies with under $10–15M in EBITDA, and senior leverage is typically capped at 3.0–3.5x. Senior bank debt is ideal for working capital revolvers and modest acquisition financing where leverage fits within the box.
Layer 2: Unitranche / Direct Lending (Mid-Cost, Maximum Flexibility)
Unitranche has become the dominant structure for mid-market acquisition financing. Unitranche debt is a distinct financing arrangement in which senior and junior tiers of debt tranches are blended into a single offering, governed by a single credit agreement. A unitranche facility typically prices at SOFR plus 550–700 basis points (reflecting a blend of senior risk (SOFR plus 400–500 bps) and subordinated risk (SOFR plus 800–1000+ bps)) and the lender provides total leverage that can reach 5–6x EBITDA in a single facility, compared to 3–4x that a senior-only lender would typically provide.
This leverage extension is precisely what makes unitranche attractive for acquisition financing: it collapses the traditional senior/mezz structure into a single agreement, eliminates intercreditor negotiations, and compresses execution timelines. If unitranche financing can close 30 to 45 days faster than a syndicated alternative, sponsors often justify 50 to 100 basis points of extra spread by avoiding financing gaps, broken syndications, or delayed closings that jeopardize purchase agreements.
Market data confirms unitranche’s dominance: global private credit assets under management reached about $2.1 trillion in 2025, up from $1.5 trillion a year earlier, and direct lending accounted for 38% of private credit capital raised in H1 2025, with most private equity acquisitions financed with debt now funded through direct lending.
Layer 3: Mezzanine / Junior Capital (Higher Cost, Equity-Like Flexibility)
Mezzanine debt sits between senior debt and equity in the capital structure, paid after senior debt and before equity in a default or liquidation scenario. The term mezzanine, or "middle floor," reflects its middle position, with any debt paid after senior debt referred to as subordinated or junior debt. Mezzanine debt is typically unsecured or lightly secured, has higher interest rates than senior loans, and is often structured with warrants or equity participation.
Unlike conventional loans that prioritize security over returns, mezzanine debt operates in the nuanced middle ground, offering lenders substantial yields (typically 12–20%) while providing borrowers with flexible, non-dilutive growth capital. The return profile is confirmed by independent data: annualized returns for mezzanine debt are approximately 11.40%, compared to 9.00% for direct lending, 5.50% for leveraged loans, and 2.40% for investment grade, according to Proskauer and J.P. Morgan Global Alternative Investment Solutions data as of February 2026.
Layer 4: Preferred Equity and Growth Equity (Highest Cost, Minimal Dilution vs. Common)
At the top of the debt/equity boundary sits preferred equity and growth equity. Minority-stake capital is a flexible type of financing that can be a useful tool for entrepreneurs managing their own liquidity prior to a full sale: a business owner can sell a minority stake to a growth equity investor today, followed by a full exit in two to three years, allowing them to receive liquidity, diversify personal risk, and gain a value-add partner. However, median dilution in 2025 sits at approximately 19.5% for seed rounds and 18% for Series A rounds, according to Carta’s State of Private Markets data, making equity the most expensive capital on a long-run basis for founders who expect continued value appreciation.
Structural Breakdown: The $40M Acquisition at 5x EBITDA
Return to the example: an $8M EBITDA business acquiring a target at $40M (5.0x EBITDA). Here is how a practitioner would map the capital stack.
| Layer | Instrument | Amount | Pricing | Leverage Turn |
|---|---|---|---|---|
| Senior Secured | Unitranche Term Loan | $28M | SOFR + 575 bps | 3.5x EBITDA |
| Junior / Mezz | Mezzanine Note + Warrants | $8M | 14% (cash + PIK blend) | 4.5x EBITDA |
| Equity | Sponsor / Management Equity | $4M | Residual upside | – |
| Total | $40M | Blended ~11.5% | 4.5x Net Leverage |
Unitranche Layer: Key Term Sheet Elements
- Facility: $28M unitranche term loan (plus $3M revolving credit facility)
- Pricing: SOFR + 575 bps (consistent with core middle-market credits per Capstone Partners Winter 2025 Leveraged Finance Report, cited below)
- OID: 2–3% of funded principal, paid at close
- Amortization: 1% per annum (essentially bullet); mandatory amortization is relatively very rare on unitranche debt.
- Maturity: 5–7 years; the resulting instrument has a single interest rate and term, which is often five to seven years.
- Covenant: Maximum total leverage ratio (maintenance, tested quarterly); minimum fixed charge coverage ratio
- Prepayment: Call protection of 102/101/par in years 1/2/3
Mezzanine Layer: Key Term Sheet Elements
- Facility: $8M subordinated note
- Pricing: 10% cash pay + 4% PIK (payment-in-kind), accruing to principal; flexible repayment terms may include features such as payment-in-kind interest, balloon payments, and long maturities, which can support companies that are growing, even if they currently lack sufficient cash on hand.
- Equity Kicker: Warrants for 3–5% fully diluted equity at a fixed strike equal to current enterprise value; warrants give lenders the right, but not the obligation, to purchase a predetermined number of shares at a specific price within a certain time frame.
- Maturity: 6 years (one year behind unitranche)
- Subordination: Governed by a negotiated intercreditor agreement or subordination agreement with the unitranche lender
A Note on PIK and Covenant Stress
The growing use of PIK features deserves attention in current market conditions. Once limited to mezzanine and subordinated debt, PIK is increasingly appearing in senior secured loan documentation. While many managers argue for a distinction between "good" and "bad" PIK, this broad-based increase suggests that borrowers are increasingly struggling under higher interest burdens. Borrowers should model PIK accretion carefully against projected free cash flow and exit timelines, PIK that compounds into a bullet repayment at maturity can create a significantly larger balance than the original principal.
Unitranche vs. Traditional Senior/Mezz Split: When Each Structure Wins
The choice between a unitranche and a split senior/mezz capital structure is a genuine trade-off, not a default decision. The traditional leveraged finance structure requires a borrower to negotiate with multiple creditor groups: a senior lender or syndicate, a mezzanine provider, and potentially a second-lien lender. Each layer has its own documents, covenants, pricing, and enforcement rights. The intercreditor agreement between these parties is among the most complex and contentious documents in any financing. Unitranche eliminates this layering.
Choose Unitranche When:
- Speed is paramount. Competitive auction processes with tight exclusivity windows favor unitranche’s single-lender decisioning and compressed documentation timeline.
- Simplicity matters post-close. The ability to work with a single lending group simplifies ongoing portfolio management, particularly during covenant modifications or add-on acquisitions.
- The deal is mid-market. Unitranche is typically preferred when speed and certainty of execution matter, such as competitive auction processes where a financing contingency could cost the deal. It also works well for mid-market transactions where the added complexity of separate tranches and an intercreditor agreement is not worth the marginal cost savings.
Choose Traditional Senior/Mezz Split When:
- Absolute cost is the priority. Bifurcating the capital stack lets you source senior debt at tighter bank pricing and mezz from a specialized provider, potentially reducing blended cost by 50–100 bps versus an all-in unitranche.
- The deal is large enough to absorb complexity. For transactions above $75–100M, the legal and advisory costs of a split structure are justified by the savings on spread.
- The mezz provider adds strategic value. Some mezzanine funds bring operational expertise, board representation, or add-on deal flow that creates value beyond the economics of the instrument.
Covenant Design: Maintenance vs. Incurrence
Covenant selection is one of the most negotiated elements of any mid-market acquisition financing. A maintenance covenant requires the borrower to meet certain financial metrics on a regular basis, such as quarterly. An incurrence covenant is only tested if the borrower takes a specific action, like attempting to take on more debt.
The emergence of "covenant-lite" unitranche facilities for stronger credits has blurred the lines between middle market and broadly syndicated loan terms. However, unlike the BSL market where over 90% of senior syndicated loans carry no meaningful maintenance covenants, most middle market unitranche facilities retain at least one financial maintenance covenant.
For borrowers, the key negotiation point is the headroom built into the maintenance covenant levels. Because the leverage ratio drives maintenance testing, incurrence baskets, pricing mechanics, excess cash flow sweeps, and in many cases amendment negotiations, its definition receives significant scrutiny and heavy negotiation between the parties. Operators should push for: (a) an EBITDA definition that includes pro forma add-backs for cost synergies and integration charges; (b) an equity cure right permitting a sponsor to inject capital to remedy a covenant breach; and (c) step-up levels in the maximum leverage ratio to accommodate the first 12–18 months post-close when integration costs are highest.
The Gap Capital Playbook: Quantify, Prepare, Run the Process
Step 1: Quantify the Gap Precisely
The gap is the difference between what senior lenders will provide and what the total financing requirement demands. Map it across three scenarios: base, downside, and post-integration. A gap that looks like $8M in the base case can balloon to $14M in a downside, and a lender who re-underwrites on a downside basis will expect you to have modeled it first. Build a sources-and-uses table that is specific to the acquisition’s closing conditions, working capital adjustment mechanism, transaction costs, and any deferred consideration (earnouts, seller notes).
Step 2: Prepare Materials That Match the Instrument
Different capital providers require different materials. Senior lenders focus on collateral quality and downside coverage. Unitranche lenders focus on EBITDA durability, customer concentration, and recurring revenue. Mezzanine providers focus on the equity cushion below them and the exit multiple required to generate a return on their warrants. Calibrate your CIM, financial model, and management presentation to the specific risk lens of the provider you are targeting. For unitranche and mezz simultaneously, prepare separate lender decks, not one generic document.
Lenders may consider financial health, creditworthiness, operational stability, industry outlook, use of funds, collateral availability, management team, debt-service capacity, and growth potential. Lenders may request financial statements, the current cap table, financial projections, details on the use of funds, and legal and regulatory compliance information.
Step 3: Run a Parallel Process
For acquisitions, never run a sequential capital raise. Approach senior/unitranche and junior capital sources simultaneously. Structure the process so you receive term sheets within the same two-week window. This creates negotiating tension, prevents lenders from exploiting information asymmetry, and compresses the overall timeline. The speed premium is real: if unitranche financing can close 30 to 45 days faster than a syndicated alternative, sponsors often justify 50 to 100 basis points of extra spread. Run the process fast, every day of financing gap is a day of deal risk.
Step 4: Build Optionality Into the Structure
In a volatile credit environment, private credit enters 2026 facing its most challenging environment since the 2008 financial crisis, prudent borrowers build structural optionality into their capital stacks. This means: (a) negotiating an uncommitted accordion facility in the unitranche agreement that can be activated for future add-on acquisitions; (b) limiting PIK toggle use to genuine cash flow stress scenarios rather than default PIK from day one; and (c) including a most-favored-nation pricing clause in the mezz agreement to benefit from market tightening on any future refinancing.
Structuring and Negotiation Guidance
For Operators
- Negotiate the EBITDA definition first, not the spread. A 25 bps reduction in margin is worth far less than securing a broad EBITDA definition with run-rate synergy add-backs, which expands your covenant headroom and reduces the risk of a technical default in year one.
- Demand an equity cure right. Many credit agreements permit sponsors to inject equity to cure covenant violations. The equity contribution is added to EBITDA or reduces debt for covenant calculation purposes, restoring compliance. This provision is standard in sponsor-backed deals and should be a non-negotiable ask in founder-led acquisitions too.
- Push back on warrant coverage in the mezz. Mezzanine providers will often open at 5–8% warrant coverage. The negotiation range is 2–5% for strong credits with clear exit visibility. Tie the warrant exercise price to a defined exit multiple rather than a flat share price to align both parties around the same outcome.
- Model the call premium carefully. Unitranche facilities typically carry 12–18 months of call protection. If your acquisition thesis involves a near-term refinancing into the BSL market once the company scales above $15M EBITDA, negotiate a shorter soft call window, or build the call premium cost into your acquisition model from day one.
For Investors and Advisors
- Watch PIK concentration risk. The IMF’s 2025 Financial Stability Report found that around 40% of private credit borrowers have negative free cash flow, up from 25% in 2021. In a portfolio of growth-stage acquisition financings, track PIK accretion across your portfolio as a leading indicator of refinancing stress, not just a yield enhancement.
- Assess the intercreditor structure before the credit. In a split senior/mezz structure, the intercreditor agreement governs enforcement timelines, standstill periods, and credit bidding rights. These terms can be as value-determinative as the underlying credit quality in a distressed scenario.
- Verify the use-of-proceeds mapping in the credit agreement. A facility drawn for "general corporate purposes" is a weaker lender position than one with specific permitted use carve-outs tied to the acquisition closing mechanics and working capital requirements.
Key Takeaways
- The gap is structural, not situational. Growth-stage acquisition financings almost always generate a gap between what senior lenders will advance and what the deal requires. Quantifying that gap across base and downside scenarios is the first act of responsible capital strategy.
- Unitranche dominates mid-market acquisition financing in 2026. With leverage capacity of 5–6x EBITDA, pricing at SOFR plus 425–700 bps depending on credit quality, and execution timelines 30–45 days faster than syndicated alternatives, unitranche is the default structure for most mid-market acquisitions, but it is not always the cheapest option.
- Mezzanine fills the gap where unitranche hits its ceiling. For acquisitions requiring leverage beyond 5x EBITDA, mezzanine provides the incremental capital through a blend of cash pay interest, PIK, and equity kickers, at a blended yield of 12–20% that must be modeled against free cash flow and exit assumptions before committing.
- Covenant design is as important as pricing. The EBITDA definition, equity cure rights, maintenance vs. incurrence covenant structure, and step-up leverage levels collectively determine how much operational flexibility the borrower retains post-close, and should be negotiated with the same rigor as the spread.
- Run a parallel, time-compressed process. Capital providers across the stack (bank, unitranche, and mezz) should receive materials simultaneously, not sequentially. Parallel processes create pricing tension, accelerate closing, and prevent any single provider from extracting information rents during a bilateral negotiation.


