
The Growth-Stage Financing Problem: Too Big for the Bank, Too Early for Cheap Equity
A company generating $8M in EBITDA has just signed a letter of intent to acquire a competitor at a $40M enterprise value. The incumbent senior lender will stretch to 3.5x EBITDA, roughly $28M. The founders are unwilling to raise equity at a valuation they consider punitive. The gap between what the bank will lend and what the deal requires is $12M. That gap is exactly where mezzanine financing lives.
Mezzanine financing (subordinated debt sitting between senior secured facilities and common equity in the capital stack) is one of the most misunderstood and underutilised instruments in the mid-market. Growth-stage operators often encounter it only under pressure, when the capital gap has already become a deal-breaker. Understanding when to deploy it, how to price it, and what terms to accept or push back on is a material competitive advantage.
This article maps the full decision logic: from identifying the gap, through placing mezzanine correctly in the capital stack, to negotiating term sheet provisions that protect the borrower’s long-term flexibility.
Where Mezzanine Sits: The Capital Stack in a Growth Transaction
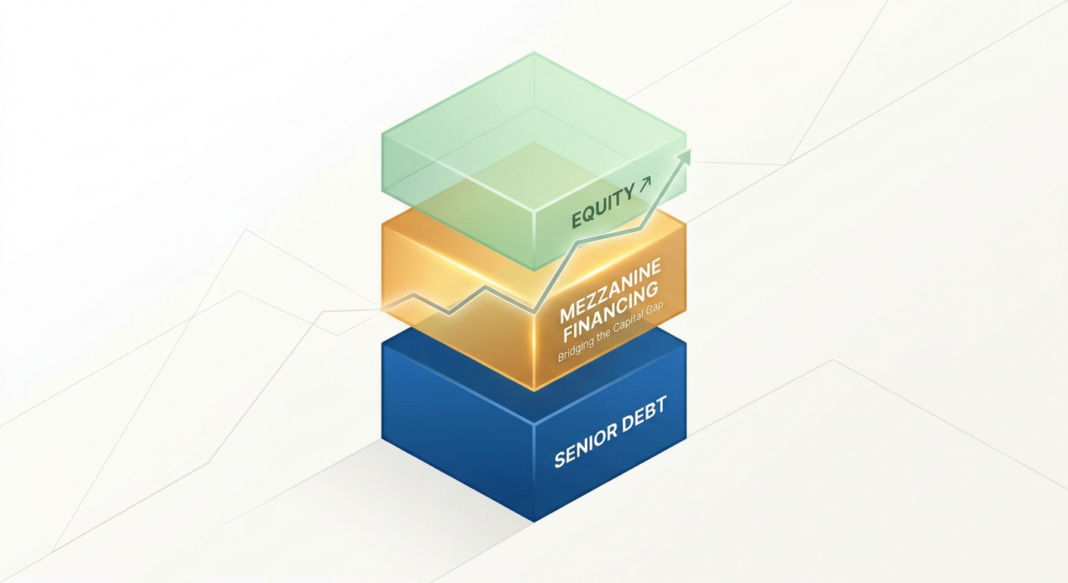
The capital stack is the layer-by-layer ordering of all funding sources by repayment priority and risk. As re-cap.com explains, each layer reflects a distinct risk-return profile: senior debt carries the lowest cost and the highest legal priority; equity sits at the top with the most risk but the most upside; mezzanine occupies the subordinated middle, accepting higher risk than senior lenders in exchange for higher yield: typically delivered through a combination of cash interest, payment-in-kind (PIK) accrual, and equity participation features.
In a typical growth acquisition structure, the stack looks like this:
- Senior Secured Debt (First Lien): 3.0x–4.0x EBITDA. Bank or direct lending facility. Lowest cost; first claim on assets. Pricing in the current market: SOFR + 400–550 bps for sponsor-backed mid-market credits.
- Mezzanine / Subordinated Debt: 1.0x–2.0x EBITDA incremental leverage. Unsecured or second-lien. Cash coupon of 8–12% plus PIK of 2–4%, with equity kickers (warrants or co-investment rights) providing the lender an additional 100–200 bps of return to reach an all-in IRR target of 14–18%.
- Preferred Equity: Optional bridge layer where a pure debt instrument is insufficient but full common dilution is undesirable. Carries a defined liquidation preference, typically 1x non-participating as market standard per alvren.com, plus a dividend coupon.
- Common Equity / Founder Rollover: Residual claim; captures all upside after debt obligations are satisfied.
Mapping this to the $40M acquisition example: $28M senior + $12M mezzanine = 100% of the purchase price, with zero equity dilution if the business can service both layers from operating cash flow. The trade-off is increased leverage and the cost of the mezzanine coupon.
Use-of-Proceeds Dictates the Instrument: When Mezzanine Is the Right Choice
The use-of-proceeds is the single most important input in capital structure design. The same $12M gap has a different optimal solution depending on what it is funding:
| Use of Proceeds | Optimal Instrument | Why Mezzanine Works Here |
|---|---|---|
| Bolt-on acquisition (cash generative target) | Mezzanine or unitranche | Acquired EBITDA services the incremental debt; defined exit via refinancing at maturity |
| Growth capex / platform build-out | Mezzanine with PIK toggle | PIK feature preserves cash during ramp; converts to cash pay once returns are realised |
| Shareholder recap / partial liquidity | Mezzanine or preferred equity | Monetises equity value without a full exit; seller retains upside |
| Covering operating losses / survival capital | Not mezzanine | Mezzanine is for growth, not distress; lenders will not underwrite deteriorating credits |
As flowcap.com notes in the context of growth-stage financing more broadly, capital deployed toward survival rather than scale produces the worst outcomes, for both borrower and lender. The clearer the use-of-proceeds narrative, the stronger the mezzanine underwriting story.
The Gap Capital Playbook: Quantifying, Preparing, and Running the Process
Step 1: Quantify the Gap Precisely
Before approaching any mezzanine provider, the borrower must define the gap with precision. This means producing a sources-and-uses table that identifies total transaction cost (including fees, working capital adjustments, and transaction expenses), maps confirmed senior capacity, and isolates the residual as the mezzanine target. Imprecise gaps (those with undefined working capital needs or unfunded contingencies) signal poor deal preparation and reduce lender confidence before a term sheet is issued.
Step 2: Build the Credit Story Around EBITDA Coverage
Mezzanine lenders underwrite to total debt service coverage, not just senior coverage. A company with $8M EBITDA and $28M senior debt at SOFR + 475 bps (blended ~9.5%) carries roughly $2.7M in annual senior interest. Add $12M mezzanine at a 10% cash coupon ($1.2M) and total cash debt service approaches $4M, a coverage ratio of approximately 2.0x. Lenders want to see a minimum of 1.5x total coverage with a clear path to deleveraging. Three-year financial projections showing EBITDA growth, cash conversion, and debt paydown are non-negotiable supporting materials.
Step 3: Run a Dual-Track Process
Growth-stage borrowers should approach mezzanine as a competitive process, not a one-lender negotiation. The mid-market mezzanine universe includes BDCs (Business Development Companies), specialist mezz funds, insurance company private credit desks, and family office credit platforms. Running three to five simultaneous conversations allows the borrower to benchmark pricing, compare covenant packages, and create genuine optionality. alvren.com advises borrowers to negotiate debt terms only after equity interest is established, the same sequencing logic applies here: confirm senior capacity first, then open the mezzanine process with a defined role and clear subordination framework.
Step 4: Evaluate the All-In Cost, Not Just the Coupon
The headline cash coupon on a mezzanine facility understates the true cost of capital. Warrant coverage (the right of the mezzanine lender to purchase equity at a pre-agreed price, typically representing 1–5% of fully diluted equity) adds an implicit cost that only materialises at exit. Borrowers should model the IRR impact of warrant dilution under base and upside scenarios. If the company exits at 8x EBITDA, a 3% warrant package on a $100M exit represents $3M of value transferred to the mezzanine lender above and beyond interest payments. This is the equity kicker cost and it must be modelled explicitly before term sheets are accepted.
Negotiation Guidance: Where Borrowers Have Leverage
Mezzanine term sheets are not standardised, and borrowers with a credible credit story and a competitive process have meaningful room to negotiate. Key battlegrounds include:
- PIK vs. Cash Pay Split: Push for a higher PIK component during the investment phase and a toggle feature that allows the borrower to elect cash or PIK based on liquidity conditions. This preserves free cash flow for growth without breaching coverage ratios.
- Warrant Coverage Percentage: Negotiate the strike price and coverage percentage aggressively. A lower strike price benefits the lender; a higher floor valuation (set to last-round or current appraised enterprise value) protects the borrower from excessive dilution.
- Covenant Package: Mezzanine facilities historically carry incurrence-based covenants (triggered only when the borrower takes a specific action) rather than maintenance covenants (tested quarterly regardless of action). In the current market, some lenders are pushing for hybrid packages. Borrowers should resist quarterly-tested leverage maintenance covenants at the mezzanine level if they are already subject to them at the senior level, double-trigger covenant structures create unnecessary cross-default exposure.
- Prepayment Flexibility: Most mezzanine facilities include call protection: typically non-call for two years, then declining premiums (102, 101, par) in years three through five. Negotiate for the ability to refinance at par after year three, particularly if the business is likely to qualify for cheaper senior-only financing as it scales.
- Change of Control Provisions: Mezzanine lenders frequently include put rights triggered by a change of control. Ensure these are subordinated to the senior facility’s consent mechanics and do not create an acceleration event that undermines the senior lender’s intercreditor position.
Key Takeaways
- Map the gap before approaching lenders. A precise sources-and-uses table with confirmed senior capacity is the foundational document for any mezzanine process. Imprecise gaps kill deals before term sheets are issued.
- Mezzanine is a growth instrument, not a rescue instrument. Lenders underwrite to EBITDA coverage and growth trajectory. Businesses using subordinated debt to fund operating losses will not find willing counterparties at reasonable terms.
- The all-in cost includes warrant dilution. Model equity kicker impact under base and upside exit scenarios before accepting any term sheet. The headline coupon systematically understates the true cost of capital.
- Run a competitive process. The mid-market mezzanine universe is fragmented. Three to five simultaneous lender conversations benchmarks pricing, sharpens covenant terms, and creates the negotiating leverage needed to push back on unfavourable structure.
- Covenant architecture matters as much as pricing. Incurrence-based covenants at the mezzanine level, combined with resistance to double-trigger maintenance tests, preserve operational flexibility and reduce cross-default risk across the full capital structure.


