
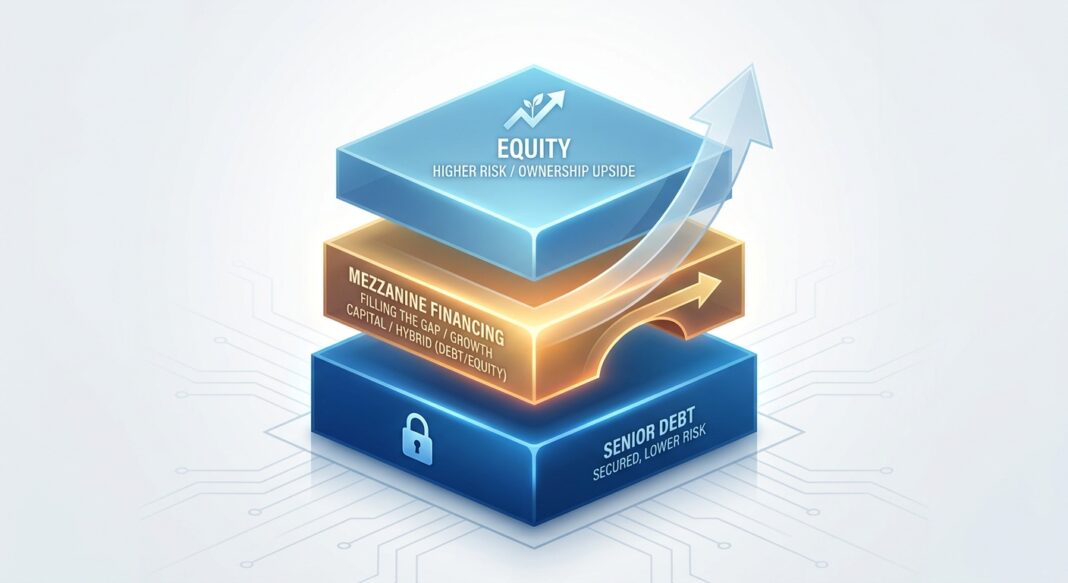
The Growth-Stage Acquisition Problem: Too Much Deal, Too Little Debt
A profitable, founder-led business with $8M in EBITDA has identified an add-on acquisition. The target is priced at $45M, roughly 5.6x EBITDA. The senior lender, a regional bank, will extend a term loan at 4.0x EBITDA, or approximately $32M. The equity the owner is willing to commit covers another $5M. That leaves an $8M hole in the capital stack, a figure too large to ignore and too small to justify a full equity round.
This is the classic growth-stage acquisition gap: the point where conventional bank financing ends and uncut equity begins. Filling it intelligently (without over-leveraging the business or surrendering disproportionate ownership) is precisely what mezzanine financing is designed to do. Understanding its mechanics, pricing, and negotiation dynamics is essential for any operator or advisor navigating an acquisition, recapitalization, or management buyout at this stage.
Mezzanine Financing: Component Breakdown
Mezzanine debt occupies the layer of the capital stack sitting between senior secured debt and common equity. As the re-cap.com capital stack framework illustrates, junior or subordinated debt holders accept higher risk than senior lenders (and are compensated accordingly, typically at 12–18% all-in returns) while remaining structurally senior to all equity holders in a liquidation waterfall.
A mezzanine facility is rarely a single instrument. It is typically an engineered combination of several features:
- Cash Pay Interest: A current coupon, commonly in the 8–12% range, paid quarterly or semi-annually. This is the baseline cost of capital the business must service from operating cash flow.
- PIK (Payment-in-Kind) Interest: An additional yield component, often 2–4%, that accrues to the principal balance rather than being paid in cash. PIK protects near-term liquidity but compounds the debt load over time and must be modelled carefully.
- Equity Kickers / Warrants: To bridge the gap between their risk profile and their return target, mezzanine lenders frequently require equity warrants, the right to purchase a small percentage of company equity (typically 1–5%) at a nominal strike price. These warrants provide the lender with upside participation if the company performs, and they are the primary point of economic negotiation.
- Subordination Agreement: Mezzanine debt is contractually subordinated to the senior facility. The senior lender will require an intercreditor agreement that restricts the mezzanine lender from accelerating or enforcing remedies during a standstill period, typically 90–180 days.
Illustrative Term Sheet: $8M Mezzanine Tranche for a $45M Acquisition
| Term | Detail |
|---|---|
| Facility Size | $8,000,000 subordinated term loan |
| Maturity | 5 years (bullet, with PIK accrual) |
| Cash Pay Coupon | 9.5% per annum, quarterly |
| PIK Margin | 3.0% per annum, accruing to principal |
| All-In Yield (pre-warrant) | ~12.5% |
| Warrant Coverage | 3% fully diluted equity, 7-year term, $1 strike |
| Covenants | Minimum EBITDA; Total Leverage ratio (maintenance); Restricted payments basket |
| Call Protection | No-call Year 1; 103 / 102 / 101 / par thereafter |
| Intercreditor | 90-day standstill; senior lender consent for amendments |
| Security | Second lien on substantially all assets; subordinated to senior facility |
The full capital stack for the $45M acquisition now reads: $32M senior term loan (4.0x EBITDA) + $8M mezzanine (5.0x pro forma total leverage) + $5M sponsor equity. Total leverage sits at 5.0x, aggressive but manageable for a business with stable, recurring cash flows.
Mezzanine vs. the Alternatives: Navigating the Cost of Capital Spectrum
Before committing to mezzanine, operators should map the full range of options against the access-versus-cost trade-off. The spectrum, from cheapest to most expensive, runs as follows:
- Senior Bank Debt (4–7% all-in): Lowest cost, maximum restrictiveness, capacity-constrained by asset coverage or cash flow leverage limits. In this scenario, the bank has drawn the line at 4.0x.
- Private Credit / Unitranche (9–12% all-in): A single-lender solution that blends senior and subordinated economics into one facility. Unitranche eliminates intercreditor complexity but typically prices higher than pure senior debt and may still require an equity co-invest. As the alvren.com capital stack sequencing framework notes, matching the instrument to the stage of risk is the core discipline.
- Mezzanine (12–18% all-in with warrants): Fills the gap between senior capacity and equity. Preserves control, avoids dilution beyond the warrant strip, and is repaid ahead of equity on exit.
- Preferred Equity (15–22% targeted return): Hybrid instrument sitting above common equity; carries no mandatory cash coupon in many structures but participates in liquidation ahead of founders. Preferred equity suits situations where cash flow cannot support any additional debt service, but it is more dilutive than mezzanine when warrants are limited.
- Common Equity: Most expensive in dilution terms. Appropriate for high-uncertainty phases (discovery, product development, or distressed restructuring) where lenders cannot underwrite stable cash flows, as the firstratefunding.net funding staircase model articulates.
For a cash-generative acquisition at 5.0x leverage, mezzanine is the structurally optimal choice: it preserves founder control, avoids the full dilution of a preferred or common equity round, and prices the risk appropriately given the business’s demonstrated EBITDA.
The Gap Capital Playbook: Quantify, Prepare, Run the Process
Step 1: Quantify the Gap Precisely
Before approaching any mezzanine provider, the operator must define the gap with precision. This means running a sources-and-uses table at multiple leverage scenarios, stress-testing debt service coverage under a downside EBITDA case (typically 20–25% below plan), and identifying the maximum PIK accrual the balance sheet can absorb without triggering covenant violations by Year 3. Do not approach mezzanine lenders with a range, arrive with a specific number and a rationale.
Step 2: Prepare the Diligence Package
Mezzanine providers underwrite both the credit and the equity story. The data room must include three years of audited financials, a trailing-twelve-months management accounts package, a detailed integration plan for the acquisition target, a five-year financial model with clearly labelled assumptions, and a clean cap table reflecting post-close ownership. Warrant coverage will be negotiated against the equity value implied by the model, so the assumptions must be defensible.
Step 3: Run a Targeted, Competitive Process
Unlike bank syndications, mezzanine markets are relationship-driven and thinner. Target four to six providers: two or three specialist mezzanine funds, one or two BDCs (Business Development Companies), and potentially the senior lender’s affiliated credit fund if one exists. Distribute a teaser and CIM simultaneously, set a two-week indication deadline, and use competing term sheets to anchor the warrant coverage and call protection negotiation.
Negotiation Guidance: Where Borrowers Have Leverage
The three highest-value negotiation points in a mezzanine term sheet are warrant coverage, PIK toggle optionality, and covenant headroom:
- Warrant Coverage: Lenders will open at 5–7% fully diluted equity. Push toward 2–3% by demonstrating a conservative leverage profile and strong DSCR (Debt Service Coverage Ratio). If the business has contracted or recurring revenues, use that predictability as a direct argument against the equity kicker size.
- PIK Toggle: Negotiate the right to toggle between cash pay and PIK at the borrower’s election for a defined period (typically years 1–2). This preserves near-term liquidity flexibility without permanently compounding the principal balance.
- Maintenance vs. Incurrence Covenants: Mezzanine facilities standardly include maintenance covenants tested quarterly. Negotiate for wider headroom, 20–25% cushion to plan EBITDA, and carve-outs for integration costs in the first 12 months post-close. An incurrence-only covenant package (tested only when taking a specific action, such as making a distribution or incurring additional debt) is worth pursuing but rarely achievable in sub-$20M mezzanine facilities without a strong competitive process.
The intercreditor agreement is a non-negotiating point on substance, the senior lender’s requirements will govern, but the standstill period and the mezzanine lender’s amendment consent rights are worth reviewing carefully. A mezzanine lender with broad consent rights over material amendments to the senior facility creates operational friction that compounds over a five-year hold.
Key Takeaways
- The gap is structural, not accidental. Senior debt capacity ends where credit policy sets it. Mezzanine is the purpose-built instrument to fill that gap without full equity dilution.
- All-in yield is the only honest price. Compare cash coupon, PIK accrual, and warrant economics together, not the headline rate alone.
- Warrant coverage is the primary negotiation lever. Arrive with a clear equity valuation rationale and use competitive tension across term sheets to compress the kicker.
- Model the PIK compounding effect explicitly. PIK interest that accrues for five years materially increases the debt load at maturity and must be stress-tested against exit valuation assumptions.
- Match the instrument to the risk stage. Mezzanine suits cash-generative businesses with predictable EBITDA. For earlier-stage businesses without stable cash flows, preferred equity or convertible structures are more appropriate, even at a higher dilution cost.


