
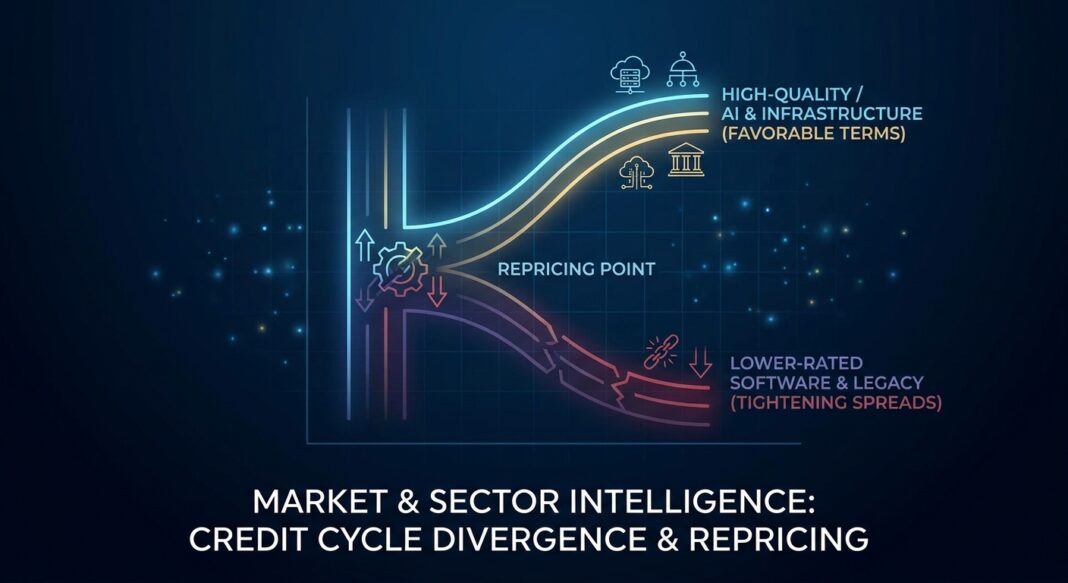
The Great Credit Bifurcation: Private Credit Reprices as the K-Shaped Market Hardens
Market & Sector Intelligence | Bond Capital | April 27, 2026
I. Market Headline: A Structural Break, Not a Cyclical Blip
The first quarter of 2026 has delivered the clearest evidence yet that the post-GFC private credit supercycle is entering a new, more demanding phase. Leveraged loan primary activity fell to approximately $235–$241 billion: a 32–34% contraction year-over-year, marking the slowest start to a year since the 2020 pandemic shock. Refinancings and repricings, which had driven volume through 2024 and into early 2025, collapsed by 42% and 39% respectively, as the repricing cycle exhausted itself and a second wave of inflationary pressure, triggered by Brent crude surging above $120/bbl in what analysts are calling the “March Oil Shock”, forced the Federal Reserve to pause its rate-cutting cycle entirely.
What has emerged is not a uniform contraction but a bifurcated one. A K-shaped market now defines the credit landscape: mega-cap, investment-grade-proximate borrowers continue to access capital on favorable terms, while a growing cohort of lower-rated, software-heavy, and highly leveraged middle-market borrowers faces widening spreads, tighter covenants, and, in the most stressed cases, redemption gates and sponsor bailouts. As sikich.com noted in its Q1 2026 credit market update, “market access favored higher-quality borrowers, with growing pressure on lower-rated credits and increasing divergence expected to persist.”
This is not purely a cyclical story. It is a structural repricing of underwriting discipline (of leverage tolerance, covenant construction, and liquidity architecture) that will define credit conditions well into 2027.
II. Quantitative Market Snapshot
| Metric | Current Reading (Q1 2026) | Prior Period | Source |
|---|---|---|---|
| Leveraged Loan Primary Volume | ~$241B total; ~$70B net new | ~$355B (Q1 2025); 32–34% decline YoY | sikich.com |
| High-Yield Bond Spread (B-rated) | ~3.17% spread premium | ~2.65% (Q4 2025); +52 bps widening | investor.wedbush.com |
| Leveraged Loan Spread Widening (Active Market) | +~100 bps (Feb–Mar 2026) | Favorable pricing conditions in January 2026 | sikich.com |
| U.S. Private Credit Default Rate | 9.2% (Fitch, 2025 full-year record) | 8.1% (2024); double-digit for <$30M EBITDA cohort | atlaspeakresearch.com |
| Distress Ratio (Loans <80 cents) | 7.23% (March 2026) | Highest level in 3 years | investor.wedbush.com |
| Public BDC Discount to NAV | ~78 cents on the dollar (Mar 12, 2026) | ~85 cents (Jan 2026); ~par (early 2025) | atlaspeakresearch.com |
| Software Sector Avg. Leverage (Private Credit) | 7.4x EBITDA | 5.9x broader loan pool average | atlaspeakresearch.com |
| Private Credit Market Size (Global) | ~$1.8T–$2.5T (AUM-basis dependent) | ~6% of U.S. GDP; expected to double in 5 years | cressetcapital.com |
KPI Threshold Shift: Lenders are visibly tightening underwriting standards around leverage multiples. Software-sector credits at 7.4x debt-to-EBITDA are under acute scrutiny, while the broader market is gravitating toward credits carrying 5.5x or below. Fixed Charge Coverage Ratio (FCCR) requirements are tightening in parallel, as floating-rate loans, the dominant structure in private credit, leave cash flows maximally exposed to a Fed that has now paused its easing cycle. Borrowers whose interest expense exceeds current earnings (a condition the IMF estimated afflicted more than one-third of private-credit borrowers following the 2022–2023 rate shock) face the most acute refinancing pressure.
III. Sector Analysis: Where Lender Appetite Is Contracting, and Where It Is Expanding
Software / SaaS, Red Flag. Software has become the single most consequential stress point in private credit. Representing approximately 16% (~$235B) of the U.S. loan market and an estimated 20% of private credit portfolios, the sector is experiencing a confluence of structural headwinds: equity values down ~22% since January 2026, sales growth decelerating from 18% to 10% YoY, roughly 50% of software loans rated B- or below, and a looming maturity wall with ~30% of loans due by 2028. The rise of agentic AI, which threatens to automate the workflows that underpin SaaS seat-count economics, is accelerating a valuation rethink that analysts have termed “SaaSPocalypse.” Lenders are actively reducing new originations in the sector and repricing existing covenants upward, according to atlaspeakresearch.com.
Media & Legacy Tech, Deeply Distressed. Cumulus Media’s second Chapter 11 filing in eight years, to restructure $592 million in debt, and New Fortress Energy’s Restructuring Support Agreement are emblematic of a broader liquidity freeze for legacy operators with high leverage and deteriorating business models. These borrowers are the “lower arm” of the K-shape, and lender appetite is effectively closed to new commitments absent rescue-financing structures at double-digit all-in yields.
AI Infrastructure, Energy & Hard Assets, Active and Favored. Capital is rotating decisively toward sectors with tangible collateral, contracted cash flows, and macro tailwinds. Oracle’s successful pricing of a $38 billion debt package for AI-integrated data center expansion, alongside strong demand for Silver Lake’s $20 billion Electronic Arts buyout financing, confirms that high-quality, cash-flow-positive businesses retain robust access to capital even in a constrained environment. Asset-backed credit strategies tied to equipment leasing, infrastructure, and royalty streams are attracting increased institutional allocation, partly because they offer superior collateral protections and, under restored full bonus depreciation rules, meaningful tax advantages for qualified investors, as noted by cressetcapital.com.
Healthcare, Selectively Open but Supply-Chain Cautious. Hologic’s successful $7.25 billion loan pricing signals that healthcare credits with strong fundamentals remain viable. However, the 100% pharmaceutical tariff implemented in April 2025, now marking its one-year anniversary, continues to inject uncertainty into supply chains with international exposure, making lenders cautious about complex, globally distributed healthcare operators.
IV. Implications for Institutional Investors and Operators
For Borrowers: The cost of capital has risen materially for any issuer below BB-rated quality. Spread widening of 100 bps in the active market, combined with a Fed on hold, means all-in debt costs for leveraged buyouts and recapitalizations have risen by roughly 80–120 bps from January 2026 levels. Borrowers facing 2026–2027 debt maturities (particularly in software, media, and highly leveraged consumer sectors) should engage lenders now, before the maturity wall concentrates further pressure on weaker credits. Asset sales and liability management exercises, while dilutive, may represent the only viable path to liquidity for the “lower arm” cohort.
For Lenders and Investors: The private credit redemption wave (with BCRED facing $3.7B in requests, BlackRock HLEND receiving $1.2B (9.3% of NAV), Cliffwater’s Corporate Lending Fund seeing ~14% redemption requests, and Morgan Stanley’s North Haven PIF accepting only 45.8% of tendered shares) is a structural warning about semi-liquid vehicle design, not necessarily a signal of broad credit deterioration. As atlaspeakresearch.com documents, the stress is concentrated in wealth-channel, semi-liquid BDC structures, not in traditional closed-end institutional direct lending funds whose capital lockups broadly match loan maturities. Institutions should audit their vehicle exposure accordingly. Public BDC discounts to reported NAV, now at ~78 cents, also create potential entry points for investors willing to accept mark-to-model uncertainty in exchange for income yield.
Underwriting Standards in Transition: Valuation credibility is now a first-order concern. FSOC has explicitly flagged that identical loans can carry materially different valuations and accrual statuses across BDCs, that payment-in-kind (PIK) income can mask true credit deterioration, and that the absence of a robust secondary market makes real-time risk pricing structurally difficult. Investors should require lenders to disaggregate PIK versus cash income and to disclose software and technology concentration before committing new capital.
V. Forward-Looking View: Selectivity Is the New Alpha
The public credit market, by contrast, continues to function efficiently. As pimco.com documents, investment-grade and high-yield corporate bond markets are exhibiting depth, breadth, and transaction cost metrics near post-GFC bests, a reminder that the liquidity debate in 2026 is not a public credit story but a private credit structural architecture story.
Looking ahead 3–6 months, three forces will determine whether the current bifurcation stabilizes or deepens: (1) the Federal Reserve’s ability to resume easing if the oil-driven inflation impulse fades, which would provide critical FCCR relief to floating-rate borrowers; (2) the pace of software sector defaults, which, at 7.4x average leverage and rising loan-to-enterprise-value ratios, could accelerate if equity multiples compress further; and (3) whether semi-liquid private credit vehicles continue to face redemption pressure, which, if sustained, could force asset sales that reprice broader private credit marks downward.
The asset class is not in crisis. As cressetcapital.com concludes, “spreads in the 5% range continue to offer meaningful compensation over public credit alternatives, and middle-market borrowers still need flexible capital.” But the era of indiscriminate yield-chasing is over. Capital availability, covenant construction, sector concentration, and vehicle liquidity architecture are now the differentiators, and the investors and operators who master that selectivity will define the next phase of the credit cycle.
Key Market Insights
- Volume collapse is structural, not seasonal: Q1 2026 leveraged loan primary activity fell 32–34% YoY to ~$241B, led by a 42% drop in refinancings and 39% drop in repricings, the weakest opening quarter since the pandemic. Deal concentration is extreme, with 40%+ of Q1 institutional volume coming from just five mega-transactions.
- Spread bifurcation is widening fast: High-yield B-rated spreads moved from 2.65% to 3.17% in Q1, while investment-grade spreads held flat, a >50 bps divergence in one quarter that signals deep investor risk aversion toward leveraged credits and a structural recalibration of underwriting standards around FCCR and leverage multiples.
- Software is the pivotal sector: With 7.4x average EBITDA leverage, ~20% private credit portfolio exposure, and equity values down 22% since January, the SaaS/software sector is the single largest source of near-term default and mark-to-model risk. Operators and lenders with concentrated software exposure need active portfolio triage now.
- Semi-liquid vehicle gates signal a structural design flaw: Redemption requests across BCRED, HLEND, Cliffwater, and North Haven PIF, ranging from 7.9% to 14% of NAV, are the first real stress test of the wealth-channel private credit distribution model. Institutional investors must distinguish between closed-end direct lending (low run risk) and evergreen/interval vehicles (elevated mismatch risk) when assessing portfolio liquidity.
- Hard assets and AI infrastructure are the growth lanes: Capital is rotating toward asset-backed credit, energy infrastructure, and AI data center financing: sectors offering tangible collateral, contracted cash flows, and, under current tax policy, enhanced after-tax returns via bonus depreciation. This rotation is structural, not tactical, and will likely persist through the end of 2026 regardless of the macro outcome.


