
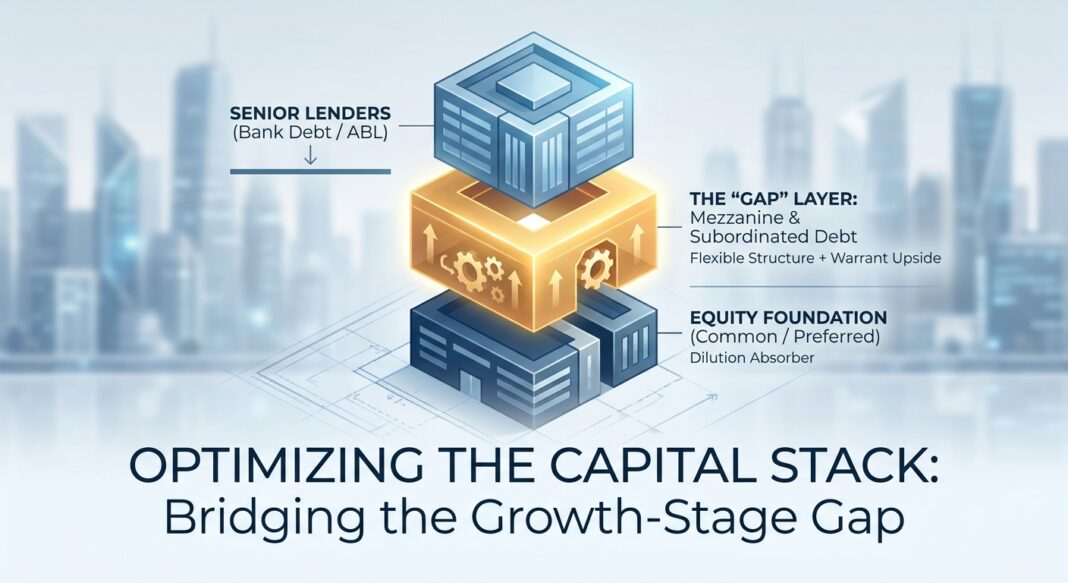
The Growth-Stage Financing Gap Nobody Talks About Honestly
You have $3M–$8M in annual revenue, proven unit economics, and a credible path to scale, but your bank just told you they can lend against 3x EBITDA and your EBITDA is still thin. The equity round you’re contemplating implies valuation dilution you can’t stomach at this stage. You’re not broken. You’re caught in the growth-stage financing gap: the point where senior debt capacity runs out before your capital need is fully funded, and equity dilution carries too high an opportunity cost to use for operational leverage.
This gap is structural, not situational. As capitalxo.com explains, every capital stack is organized by repayment priority: senior lenders sit at the top with first-lien claims, equity absorbs risk at the bottom, and everything in the middle must be deliberately engineered. The problem for growth-stage businesses is that the middle is rarely filled by accident. It requires a deliberate playbook.
Mapping the Capital Stack at the Growth Stage
Before structuring anything, map the full cost-of-capital spectrum available to a growth-stage business. Each layer carries a different price, a different claim on your cash flow, and a different set of governance consequences:
- Senior Bank Debt (cheapest, most restrictive): Typically priced at Prime + 2%–4% with first-lien collateral, maintenance covenants, and personal guarantee requirements. Capacity is constrained by asset coverage or EBITDA multiples, usually 2x–3.5x for businesses at this stage.
- Asset-Based Lines of Credit: Advance rates of 70%–85% on eligible receivables and 50%–60% on inventory. Higher availability than cash-flow lending for businesses with strong working capital assets, but revolving structures that don’t fund long-term growth initiatives.
- Subordinated / Mezzanine Debt (the gap layer): Priced at 12%–18% all-in, often combining a cash coupon with PIK (payment-in-kind) interest and an equity kicker via warrants or a revenue participation feature. Sits behind senior debt in the repayment waterfall, which is why it costs more, but it is still debt, meaning no board seats and no equity dilution beyond the warrant strip.
- Preferred Equity: Structured as dividend-bearing preferred shares with liquidation preferences. Carries 20%–30%+ return expectations and typically introduces governance rights. Appropriate for businesses that cannot service additional fixed debt obligations.
- Common Equity / Venture Capital: Most expensive on a dilution-adjusted basis. As lendity.com illustrates with Swiss-market founder data, giving up 25% equity in a round that funds what is essentially operational scaling frequently destroys more exit value than the interest cost of debt alternatives.
The growth-stage imperative is straightforward: fill the gap between senior debt capacity and total capital need using the cheapest subordinated instrument your cash flow can service, reserving equity for true inflection-point investments where the return multiple justifies the dilution.
The Mezzanine Structure: Component Breakdown
Consider a practical example. A $20M revenue B2B software business with $2.5M EBITDA is pursuing a $12M acquisition of a complementary product line. The senior bank will lend 3x EBITDA, call it $7.5M. The buyer has $2M in equity to contribute. That leaves a $2.5M gap.
A mezzanine tranche structured to fill this gap might look as follows:
- Principal: $2.5M subordinated term note
- Cash Coupon: 10% per annum, paid quarterly
- PIK Toggle: Option to PIK 3% of the coupon in years 1–2, accruing to principal, preserving near-term cash flow during integration
- Warrant Coverage: 3%–5% equity warrant on a fully diluted basis, exercisable at a pre-agreed strike price, providing the mezzanine lender upside participation without taking a board seat
- Maturity: 5 years, with no amortization in years 1–2 (interest-only) then straight-line repayment
- Covenant Package: Incurrence-based covenants (triggered only when the borrower takes new action, such as additional debt or a dividend) rather than maintenance covenants that test ratios quarterly, a critical distinction that preserves operational flexibility
The total cost of this structure is approximately 13%–14% all-in, significantly cheaper than raising equity at a dilutive valuation. As re-cap.com notes, the capital stack is not just an abstract concept; it directly determines who gets paid in what order and what each capital provider’s risk-return expectation must be. Pricing the mezzanine layer at a level that reflects its subordinated position is essential to attracting capital while keeping total stack cost manageable.
The Gap Capital Playbook: Four Steps to Execution
Step 1: Quantify the Gap with Precision
Don’t approach the market with a round number. Model total project cost, senior debt capacity (tested against lender advance rate formulas and EBITDA multiples), available equity, and the residual. Document your post-close pro forma leverage ratio and DSCR (debt service coverage ratio) under base, downside, and upside scenarios. Mezzanine lenders underwrite to exit, not just cash flow, show them a credible path to repayment or refinance within the loan term.
Step 2: Prepare a Subordinated Debt Information Memorandum
Unlike a senior bank package, a mezzanine IM needs to address equity-like questions: What is the business worth? What does the exit landscape look like? What are the downside protection mechanisms? Include a capital structure diagram showing the full stack, the intercreditor framework, and the waterfall analysis at multiple exit values. As peachtreecap.com emphasizes, capital structure planning should precede lender conversations, not follow rejection.
Step 3: Run a Targeted Process
The mezzanine and subordinated debt market is relationship-driven. Target private credit funds, BDCs (Business Development Companies), family office credit desks, and insurance company credit arms that have mandates in your deal size range. For sub-$5M gap tranches, also consider revenue-based lenders and structured growth debt providers. Run three to five simultaneous conversations to create pricing tension. Never approach a single source sequentially; it eliminates your negotiating leverage entirely.
Step 4: Negotiate Structure, Not Just Rate
The rate headline matters less than the structural terms that govern your flexibility over the loan’s life. Priority negotiation points for borrowers include:
- PIK optionality: Secure the right to defer cash interest in early years; this is operational insurance, not a signal of weakness.
- Warrant coverage and strike price: Push for warrants sized at 3%–5% of equity, not 10%+, and negotiate a strike price at or above current valuation to minimize dilution at exit.
- Covenant type: Incurrence over maintenance, always. A quarterly maintenance covenant on leverage or coverage can trigger technical default during a perfectly manageable operational quarter.
- Intercreditor agreement terms: Ensure the subordinated lender’s standstill period (the window during which they cannot take enforcement action while the senior lender is in control) is clearly defined and workable, typically 90–180 days.
- Prepayment flexibility: Negotiate soft call protection (a declining prepayment premium, e.g., 3%/2%/1% over three years) rather than hard no-call provisions that lock you out of refinancing if your business improves faster than projected.
Key Takeaways
- 🔑 The growth-stage financing gap is structural: Senior debt capacity is constrained by cash flow and collateral; the gap between that ceiling and total capital need must be engineered deliberately using subordinated instruments.
- 🔑 Mezzanine debt fills the gap at a fraction of equity’s dilution cost: A 13%–15% all-in mezzanine tranche, even with warrant coverage, typically preserves far more exit value than a priced equity round at growth-stage valuations.
- 🔑 Structure matters more than rate: PIK optionality, incurrence covenants, and soft-call prepayment terms are the terms that determine whether your capital stack supports or constrains you as the business scales.
- 🔑 Run a parallel process: Approaching three to five subordinated lenders simultaneously creates pricing tension and gives you the leverage to negotiate structural concessions that a single-source process never achieves.
- 🔑 Model the full waterfall before signing: Every layer of the capital stack changes who gets paid and in what order at exit. Stress-test your exit proceeds across multiple scenarios before committing to any structure that introduces liquidation preferences or warrant dilution.


