
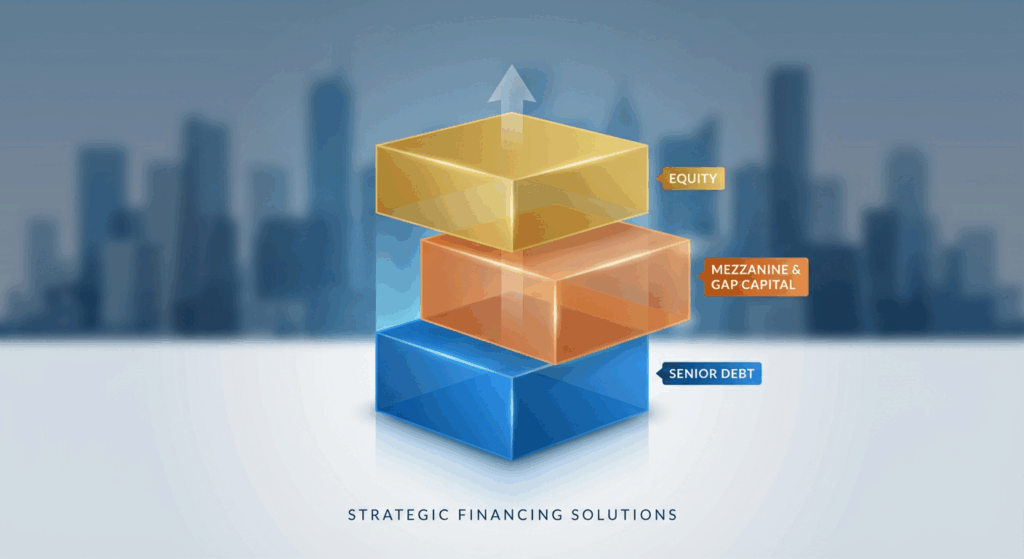
The Growth-Stage Acquisition Problem: You Have the Deal, Not the Stack
You are running a $15M–$40M revenue business. You have built product-market fit, your unit economics are proven, and an acquisition target has landed in front of you, one that would accelerate your market position by two or three years. The problem is structural: your senior bank will stretch to 3x EBITDA, your equity sponsor either wants too much dilution or is not ready to re-underwrite the full platform. Between the senior debt ceiling and the equity floor, there is a funding gap of $8M–$20M that neither instrument wants to own alone.
This is the defining capital challenge of the growth stage, and it is precisely the scenario that the middle of the capital stack was designed to solve. Understanding how to structure that gap, price it correctly, and negotiate it efficiently separates operators who close transformational deals from those who watch competitors do it instead.
Mapping the Cost of Capital Spectrum at This Stage
The capital stack is a hierarchy of risk and return. As outlined by corporatefinanceinstitute.com, each layer (senior debt, subordinated debt, preferred equity, and common equity) carries a distinct risk profile, repayment priority, and pricing expectation. For a growth-stage acquisition, the relevant spectrum looks like this:
- Senior Bank Debt (3.0x–3.5x EBITDA, ~SOFR + 200–275 bps): First-lien, lowest cost, most restrictive. Available from community banks, regional banks, and SBA lenders for established cash-flow businesses. Covenant-heavy: typically maintenance-tested leverage and coverage ratios quarterly. This is your foundation layer, but it will not reach the acquisition price alone.
- Private Credit / Unitranche (4.0x–5.5x EBITDA, ~10%–13% all-in): Direct lenders can underwrite deeper leverage in a single facility, eliminating the senior/mezz intercreditor complexity. Useful when speed or certainty of close matters more than minimizing blended cost.
- Mezzanine Debt (5.0x–6.0x EBITDA, ~13%–17% all-in, often with PIK toggle or warrant coverage): Subordinated to senior debt, unsecured or second-lien. The canonical gap-filler. Mezzanine lenders accept a longer payoff horizon in exchange for higher current yield, deferred PIK interest, and sometimes a small equity co-investment or warrant strip (typically 1%–3% fully diluted).
- Preferred Equity (~18%–22% preferred return, non-dilutive to common until conversion): Sits below all debt but above common equity. Preferred equity providers do not require debt-service coverage but do require a clear liquidity path. Best used when the business cannot sustain additional fixed charges but can credibly project an exit or recap within three to five years.
- Common Equity (target IRR 25%–35%+): The most expensive capital in the stack. Every dollar of equity gap-fill is a dollar of ownership transferred permanently. Use common equity for genuinely transformational risk (new markets, platform bets) not to bridge a financing gap that debt or preferred can cover more cheaply.
As capitalxo.com notes, poorly structured stacks often result from adding layers reactively rather than designing the architecture to match the business’s risk profile and cash flow capacity from the outset.
Structuring the Gap: The Mezzanine Playbook for a Growth-Stage Add-On
Consider a concrete scenario: a $12M EBITDA services platform pursuing a $70M enterprise-value bolt-on acquisition. The senior lender will fund to 3.5x, providing $42M. Equity (existing sponsor or management rollover) can contribute $15M. That leaves a $13M gap. This is a textbook mezzanine financing mandate.
Illustrative term sheet elements for the $13M mezz tranche:
- Principal: $13,000,000
- Coupon: 13.0% per annum (cash pay), with a 2.0% PIK toggle available in years one and two at borrower election, capitalizing to principal
- Warrant Coverage: 2.0% fully diluted equity in the combined platform, exercisable at a nominal strike; economic kicker aligned with exit multiple
- Maturity: 6 years, with no amortization; bullet repayment
- Call Protection: Non-callable years one and two; 103 call premium in year three, 101 in year four, par thereafter
- Covenants: Incurrence-based (no maintenance tests); negative pledge on material assets; change of control put at 101
- Intercreditor: Standard subordination agreement; 90-day standstill in favor of senior lender on enforcement action
The PIK toggle is a critical liquidity management tool: in an integration year where free cash flow is temporarily compressed, the borrower can defer 2 points of interest to principal rather than stress senior debt service coverage. The warrant strip provides the mezz lender equity upside without requiring a formal equity co-investment, keeping the common equity cap table cleaner.
The Gap Capital Playbook: Quantify, Prepare, Run, Negotiate
Step 1: Quantify the Gap with Precision
Model the acquisition sources and uses at three leverage scenarios (conservative, base, upside). Identify the exact dollar quantum sitting between senior debt capacity and available equity. Do not round. Lenders price to the specific quantum and coverage ratio. A $13M gap priced at 13% costs $1.69M annually in cash interest, model that against projected post-close free cash flow before approaching any provider.
Step 2: Prepare the Information Package
Mezzanine lenders underwrite the combined entity, not just the acquirer. Your information memorandum must include: three years of audited financials for both entities; a detailed integration plan with synergy bridge; pro forma capitalization table showing all layers; and a five-year cash flow model stress-tested at 20% revenue haircut. As corporatefinanceinstitute.com highlights, each debt layer uses the equity cushion below it as its primary loss buffer, lenders will scrutinize that cushion intensely.
Step 3: Run a Focused Process
Target six to ten mezzanine lenders with demonstrated experience in your sector and deal size. Avoid a broad auction that signals desperation. The goal is two to three competitive term sheets, enough to create pricing tension without turning the process into a commodity exercise. Timing matters: mezzanine credit approvals typically require four to six weeks from term sheet to commitment letter. Build that into your deal timeline.
Step 4: Negotiate the Structure, Not Just the Rate
Rate is the headline, but structure is where value lives or dies. The highest-leverage negotiation points for borrowers in a mezzanine context are:
- PIK flexibility: Push for a full PIK toggle in years one through three, not just years one through two. Cash flow during integration is notoriously variable.
- Warrant coverage percentage and dilution mechanics: Negotiate the warrant strike price (nominal vs. fair market value) and whether warrants are on a pre-money or post-money basis. A 2% warrant on a $100M platform is $2M of value, fight for every basis point of that coverage.
- Call protection duration: Lenders want two-year hard no-call; borrowers should target 18 months or a make-whole premium structure that steps down rapidly. If you anticipate a refinancing event within 24 months, this is a material economic term.
- Covenant package: Incurrence-based covenants (triggered only when the borrower takes an action) are structurally superior to maintenance covenants (tested quarterly regardless of action). Push hard for incurrence-only, particularly on leverage and coverage tests.
- Equity co-investment rights: Some mezz lenders request the right to co-invest in future equity rounds. Agree to notification rights only; avoid granting pro-rata participation rights that constrain future capital raises.
Key Takeaways
- The gap between senior debt and equity is a structural problem, not a size problem. Mezzanine and preferred equity exist precisely to bridge this layer, using common equity to fill it is an expensive default, not a strategy.
- PIK toggles preserve liquidity during integration. Deferred interest capitalizes to principal but protects free cash flow in the quarters immediately post-close when the deal is most vulnerable.
- Warrant coverage is negotiable, treat it like equity dilution. A 2% fully diluted warrant on a $100M platform at exit represents $2M of ownership transferred. Model every basis point.
- Incurrence covenants outperform maintenance covenants for acquisitive platforms. Maintenance tests create covenant stress during normal operational variability; incurrence tests only trigger when the borrower acts.
- The capital stack is architecture, not assembly. Each layer must be sized, priced, and documented relative to the layers above and below it: intercreditor terms, cash flow allocation, and refinancing timelines must all be modeled as a system before signing any single instrument.


