
The Growth-Stage Capital Problem Is Always a Sequencing Problem
A company generating $8M in annual recurring revenue with 25% EBITDA margins and a clear acquisition target sitting in front of it faces a deceptively simple question: How do we fund the next move without destroying the cap table? The answer is never a single instrument. It is a deliberate sequence of layers: each matched to a specific use of proceeds, risk profile, and cost tolerance.
At the growth stage, roughly $5M to $30M in revenue, businesses have typically outgrown the venture seed model but are not yet large enough to access broadly syndicated leveraged loan markets. This is the gap. And navigating it requires operators to think like architects, not applicants. The capital stack, as CapitalXO notes, must be designed deliberately, layer by layer, because each instrument added affects the cost, control, and flexibility of every layer above and below it.
Step 1: Map the Use-of-Proceeds Before Touching the Market
Before selecting any financing instrument, operators must decompose the capital need into discrete use-of-proceeds buckets. Each bucket carries a different risk profile and, therefore, demands a different financing layer.
- Working Capital: Revolving credit facility, asset-based line, or revenue-based facility. Short-duration, self-liquidating. Banks are the correct source when receivables and inventory support the borrowing base.
- Organic Growth (hiring, marketing, R&D): Growth debt, revenue-based financing, or a term loan with amortization aligned to the revenue ramp. This is where private credit and specialty lenders play, particularly for SaaS or recurring-revenue businesses where traditional banks underwrite poorly.
- Acquisition Financing: Cash-flow term loan, unitranche, or a senior/mezz split depending on leverage tolerance. The acquired EBITDA services the debt, so underwriting shifts to pro forma combined cash flow.
- Recapitalization or Owner Liquidity: Subordinated debt, preferred equity, or a structured secondary, typically priced higher because proceeds do not directly generate new cash flow for the business.
- Business Succession or Management Buyout: Full capital stack reconstruction: senior secured debt at the base, mezzanine in the middle, and rollover or new equity at the bottom.
This decomposition is not academic. Lenders underwrite use-of-proceeds directly. A $10M ask for an acquisition will receive meaningfully different terms than the same $10M ask for a recap. Getting this mapping wrong before approaching the market costs both time and pricing.
Step 2: Place Each Bucket on the Cost of Capital Spectrum
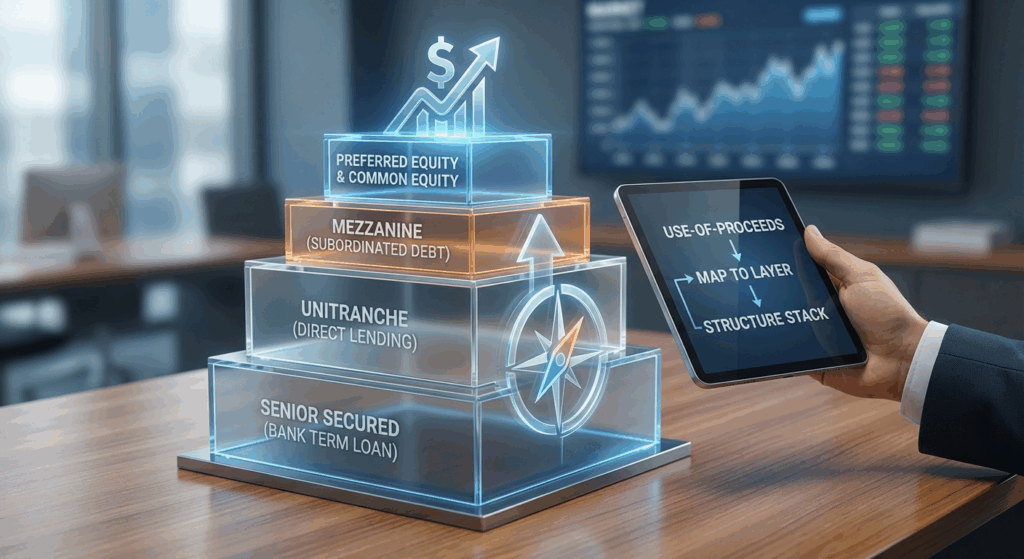
The capital stack, as explained by the Corporate Finance Institute, runs from senior secured debt at the lowest cost to common equity at the highest. For growth-stage companies in 2025–2026, the practical spectrum looks like this:
| Layer | Instrument | Indicative All-In Cost | Control Impact |
|---|---|---|---|
| Senior Secured | Bank term loan / ABL revolver | 7%–10% (SOFR + spread) | Maintenance covenants, reporting |
| Unitranche / Direct Lending | Private credit term loan | 10%–13% | Incurrence covenants, more flexible |
| Mezzanine | Subordinated note (cash + PIK) | 13%–18% (blended cash/PIK) | Equity kicker or warrant coverage |
| Preferred Equity | Structured preferred with liquidation preference | 15%–22% (IRR) | Board observer, protective provisions |
| Common Equity | PE minority / growth equity | 25%+ IRR expectation | Board seats, governance rights |
The operator’s job is to push as much of the required capital as far up the stack, toward senior secured, as the use-of-proceeds and business profile will support. Every dollar of equity avoided at 25%+ cost is a dollar of long-term enterprise value retained by the founder or existing shareholders.
For growth-stage companies with predictable recurring revenue but limited hard assets, the unitranche structure (a single blended-rate facility from a direct lender that combines what would traditionally be a senior and subordinated tranche) has become the dominant instrument in the $10M–$75M deal size range. It eliminates inter-creditor complexity, accelerates execution, and offers incurrence-based covenant packages that provide operating flexibility unavailable in traditional bank structures.
Step 3: The Gap Capital Playbook
Gap capital is the financing that sits between what a conventional bank will lend and what a pure equity provider must fund. Quantifying, packaging, and closing this gap is the core skill of growth-stage capital formation.
Quantify the Gap
Start with a three-scenario model: base, downside, and stress. The gap is the delta between what senior lenders will advance (typically 3.0x–4.0x EBITDA for a cash-flow loan, or a defined borrowing base for an ABL) and the total capital required for the stated use-of-proceeds. If the acquisition requires $20M and the bank will lend $12M at 3.5x trailing EBITDA of $3.4M, the gap is $8M. That $8M must come from the mezzanine layer, preferred equity, or seller financing.
Prepare the Materials
A credible growth-stage credit package includes: (1) a management presentation with a clear use-of-proceeds narrative, (2) three years of audited or reviewed financials plus a trailing twelve-month bridge, (3) a detailed pro forma showing combined leverage and coverage ratios post-transaction, and (4) a customer cohort or revenue retention analysis if recurring revenue is a key underwriting metric. The quality of this package directly determines which lenders engage and at what speed.
Run a Competitive Process
Never approach a single lender for gap capital. A focused process engaging four to six direct lenders, two to three mezzanine funds, and one structured equity provider simultaneously creates the optionality needed to negotiate effectively. The goal is competing term sheets, not just a single offer. As angelinvestorsnetwork.com highlights in its 2026 growth capital guide, the approval timeline for non-bank private credit can range from 30 to 90 days, meaningfully faster than traditional bank processes, which itself is a negotiating variable when a deal has a closing deadline.
Step 4, Negotiation Guidance: Where the Structure Actually Gets Made
Once competing term sheets are in hand, negotiation focuses on five structural variables:
- Covenant Package: Push hard for incurrence-only covenants in private credit deals. Maintenance covenants, particularly a leverage covenant tested quarterly, create refinancing risk in any revenue softness scenario. If a maintenance covenant is unavoidable, negotiate the threshold with a 20%–25% cushion to projected performance and build in a cure right.
- PIK Toggle: For mezzanine tranches, a PIK toggle, allowing the borrower to elect to pay interest in kind rather than cash during stress periods, is a meaningful liquidity protection. Lenders will price this optionality, but the premium is often worth the downside protection.
- Prepayment Flexibility: Growth-stage companies frequently refinance as they scale into lower-cost structures. Negotiate for a soft call schedule (103/102/101/par) rather than make-whole provisions, which can effectively lock the borrower into the facility for its full term.
- Warrant Coverage and Equity Kickers: Mezzanine lenders routinely request warrant coverage of 3%–8% of fully diluted equity. Negotiate the strike price (typically at the current valuation or a modest premium), the anti-dilution provisions, and whether warrants are net-exercisable. A structured buyout right at a predetermined multiple of invested capital can cap the lender’s upside and protect the cap table at exit.
- Reporting and Information Rights: Agree on a reporting cadence upfront. Monthly financials with a 20-day lag and quarterly compliance certificates are standard. Lenders who request board observer rights in a debt instrument, rather than equity, should be pushed back; this conflates the risk profile of the instrument with equity governance rights.
Key Takeaways
- Use-of-proceeds determines the instrument: Working capital belongs at the senior secured layer; acquisitions can support unitranche or senior/mezz structures; recaps and owner liquidity sit lower in the stack and cost more.
- The unitranche has become the default growth-stage structure for $10M–$75M transactions: it collapses inter-creditor complexity, accelerates closing, and delivers incurrence covenant flexibility unavailable from bank lenders.
- Quantify the gap before approaching the market: The gap is the delta between senior capacity and total capital required. Every dollar of that gap closed with subordinated debt rather than equity is enterprise value preserved.
- A competitive process is not optional: Engaging four to six lenders simultaneously is the only reliable mechanism for generating the term sheet competition needed to negotiate cost, covenants, and equity features effectively.
- The five negotiation levers: covenant package, PIK toggle, prepayment flexibility, warrant coverage, and reporting rights, determine the long-term cost and control burden of any growth-stage financing. Operators who understand each lever enter the room with a meaningful structural advantage.


