
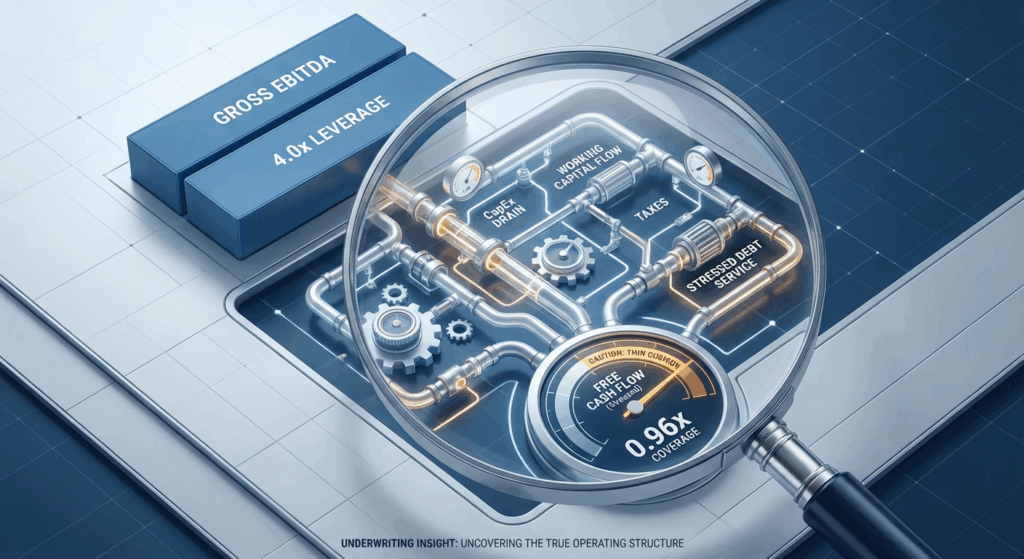
The Underwriting Challenge: Predicting Durability
In credit markets, the distance between "approved" and "default" is often measured in the resilience of a borrower’s cash flow, not the magnitude of their accounting profits. While headline multiples (Total Debt / EBITDA) provide a quick shorthand for leverage, they fail to capture the nuances of capital intensity, working capital volatility, and margin compression risks. Effective underwriting requires moving beyond static ratios to dynamic stress testing.
As noted in recent market analysis on debt capacity, the higher interest rate environment has constrained total leverage profiles, compressing acceptable ranges from the historical 6.0x+ down to 4.0x–5.0x for many middle-market transactions. For underwriters, this shift necessitates a more rigorous focus on Debt Service Coverage Ratios (DSCR) and Fixed Charge Coverage Ratios (FCCR) under adverse scenarios. The objective is not merely to determine if a borrower can pay today, but whether they can absorb a shock and still perform tomorrow.
The Framework: Cash Flow Logic Over Accounting Proxies
The core of rigorous underwriting lies in converting EBITDA, an accounting proxy, into Unlevered Free Cash Flow (UFCF). The underwriting framework must sequence these metrics correcty, ensuring that risk is not obscured by isolation biases. As highlighted in broader underwriting guides, problems often arise not because a metric is wrong, but because it is interpreted without scrutiny of the assumptions behind it.
A robust stress-testing framework involves three distinct steps:
- Normalization: Adjusting reported EBITDA for non-recurring items, pro-forma synergies (with haircuts), and owner add-backs to arrive at a defensible "Adjusted EBITDA."
- Conversion: Subtracting Maintenance CapEx, Cash Taxes, and Change in Net Working Capital (NWC) to arrive at Pre-Debt Free Cash Flow.
- Sensitization: Applying specific stress variables (revenue decline, margin contraction, interest rate expansion) to test the breaking point of the capital structure.
The Analysis: Stress Testing a $10M EBITDA Borrower
To illustrate the methodology, consider a manufacturing company seeking a senior term loan. The headline figures present a healthy business:
- LTM EBITDA: $10.0 Million
- Proposed Debt: $40.0 Million (4.0x Leverage)
- Interest Rate: 8.0% (Interest Expense ~ $3.2M)
Step 1: The Cash Flow Conversion
While 4.0x leverage appears standard, the cash flow conversion reveals a tighter picture. If the business requires $1.5M in maintenance CapEx and historically consumes $0.5M in working capital to support growth, the math changes:
$10.0M EBITDA – $1.5M CapEx – $0.5M NWC – $2.0M Taxes = $6.0M Free Cash Flow
Against $3.2M in interest and $2.0M in mandatory principal amortization (5%), the total fixed charges are $5.2M. The Base Case FCCR is roughly 1.15x ($6.0M / $5.2M). This provides a very thin margin of error despite the "reasonable" 4.0x leverage multiple.
Step 2: The Downside Scenario
A standard downside case might assume a 10% revenue decline and a 100bps compression in gross margin due to input cost inflation. If these factors reduce EBITDA to $8.0M, the flow-through looks like this:
$8.0M EBITDA – $1.5M CapEx – $1.5M Taxes = $5.0M Free Cash Flow (assuming NWC flat)
With fixed charges remaining static at $5.2M, the coverage ratio drops to 0.96x. In this scenario, the borrower is burning cash after debt service, necessitating a draw on their revolver or an equity injection to stay current. This analysis reveals that the structure is fragile, despite acceptable headline leverage.
Industry Standards and Red Flags
Institutional lenders and rating agencies typically require a "covenant cushion" of 20-30% on cash flow metrics. According to recent Basel Committee principles regarding credit risk management, banks are expected to operate under a sound credit-granting process that explicitly considers stress scenarios.
Common red flags identified in this process include:
- High Fixed Cost Base: Companies with high operating leverage suffer disproportionate EBITDA declines when revenue softens.
- Aggressive “Adjusted” EBITDA: If more than 15-20% of the EBITDA comes from “add-backs” rather than operations, the actual cash available to service debt is likely overstated.
- CapEx Definitions: Borrowers often classify ongoing expenses as “Growth CapEx” to exclude them from coverage ratios. Underwriters must scrupulously reclassify these as maintenance if they are required to sustain current revenues.
Data indicates that leverage multiples are cyclical, but debt capacity, driven by cash, is structural. In LBO scenarios, lenders are currently capping leverage where the Fixed Charge Coverage Ratio remains above 1.25x in the base case and above 1.0x in a downside scenario.
Underwriting Checklist: Due Diligence Requirements
To effectively assess these risks, the dilation process must be methodical:
- Verify Quality of Earnings (QoE): Request a third-party QoE report to validate the sustainability of EBITDA adjustments.
- Model “The Break”: Calculate exactly how much revenue or margin must perform before the FCCR hits 1.0x. If revenue only needs to drop 4% to breach, the deal is likely too risky.
- Assess Collateral Liquidity: In a default scenario, how quickly can inventory be converted to cash?
- Review Covenant Definitions: Ensure the credit agreement defines “EBITDA” and “Fixed Charges” in a way that matches your underwriting model, preventing the borrower from engineering compliance.
- Stress Interest Rates: Always model the floating rate component at the forward curve plus a spread margin (e.g., +200bps) to ensure serviceability in a rising rate environment.
Key Takeaways
- Cash is King: EBITDA is a valuation metric; Free Cash Flow is a repayment metric. Underwrite to the latter.
- Leverage is Relative: A 4.0x deal can be riskier than a 5.0x deal if the borrower has high CapEx or volatile working capital.
- Stress Test Early: Identify the “break-even” point for EBITDA before issuing a term sheet.
- Watch the Add-Backs: Heavily adjusted EBITDA numbers distort true debt capacity; scrutinize them relentlessly.
- Cushion Matters: A 1.15x coverage ratio leaves virtually no room for operational error or economic headwinds.


