
The Foundation of Risk and Return
In March 2026, the private credit market is navigating what researchers are calling a “liquidity and valuation-credibility repricing.” As redemption gates strain certain semi-liquid funds and valuations come under scrutiny, one fundamental concept remains the bedrock of safety and return: The Capital Stack.
Whether you are an investor seeking yield or a business operator seeking capital, understanding where a specific instrument sits in the capital stack is the single most important factor in determining risk exposure. It answers the critical question: “If things go wrong, who gets paid first?”
This article breaks down the mechanics of the capital stack, focusing on the distinction between senior and subordinated positions, and applies these timeless principles to the specific market conditions of early 2026.
The Concept: The Layered Cake of Finance
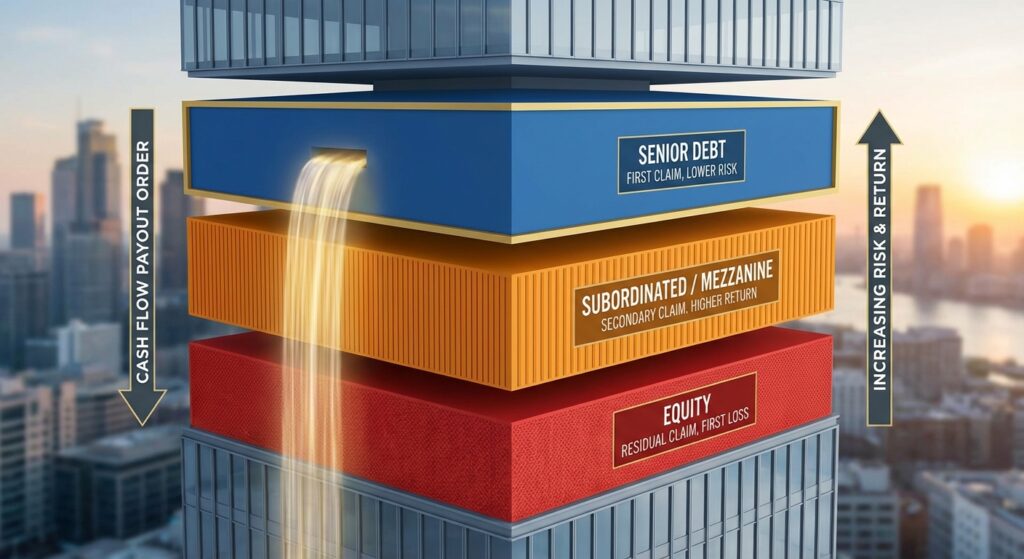
The capital stack represents the hierarchy of rights and priorities within a company’s capital structure. You can visualize it as a layered cake, where cash flows from operations or a sale are poured from the top down.
- Senior Secured Debt (Top Layer): This layer has the first claim on cash flows and assets. It is typically “secured” by collateral (receivables, inventory, IP). Because it takes the least risk, it commands the lowest cost of capital, though in the current 2026 rate environment, “lowest” is relative.
- Subordinated / Mezzanine Debt (Middle Layer): This capital sits behind senior debt. It only gets paid after senior lenders are satisfied. To compensate for this increased risk of loss, it demands higher coupon payments, often mixing cash interest with “PIK” (Payment in Kind) or equity warrants.
- Equity (Bottom Layer): This is the ownership layer. In a downside scenario, equity is the first to be wiped out (the “First Loss” position). In an upside scenario, equity captures all residual value after debt obligations are met.
How It Works: The $100 Million Example
To understand the mechanics of subordination, consider a hypothetical software company, TechCo, valued at $100 million.
The Structure:
- Senior Debt: $40 million (Interest rate: SOFR + 6%)
- Equity: $60 million (Sponsor capital)
Scenario A: Growth (Upside)
TechCo is sold for $150 million. The Senior Lender receives their $40 million principal back plus accrued interest. The Equity holders receive the remaining $110 million. The lender’s upside is capped; the equity upside is unlimited.
Scenario B: Distress (Downside)
TechCo faces headwinds, perhaps due to the AI disruption risks noted in recent market reports, and is forced to liquidate for only $30 million.
Result:
- Senior Lender: Receives $30 million (recovering 75% of principal).
- Equity Holders: Receive $0 (a 100% loss).
This “equity cushion” ($60 million in the starting scenario) protects the lender. The thicker the cushion (lower Loan-to-Value ratio), the safer the debt. In 2026, as valuations are tested, the thickness of this cushion is the primary metric disciplined managers are scrutinizing.
Current Market Relevance (Q1 2026)
The theoretical mechanics of the capital stack are currently colliding with a shifting macroeconomic reality. According to Atlas Peak Research (March 2026), the market is experiencing stress where “illiquid middle-market loans have been packaged inside semi-liquid structures.” This makes the structural priority of investments vital.
Here are three key data points shaping the capital stack today:
- Yields at the Top of the Stack: With base rates (SOFR) hovering around 4.3%, senior direct lending is generating yields of 10-12%+. According to Capital Founders, this creates a scenario where senior debt offers equity-like returns from the last decade with significantly better downside protection.
- Institutional Allocation Shifts: Family offices have doubled their private credit allocations from 2% in 2023 to 4% in 2024, with trends continuing into 2026, as investors seek these higher yields higher up the stack.
- Lender Protections: Following bank retrenchments driven by regulations like Basel III, private lenders now occupy the senior status previously held by commercial banks. This structural shift is viewed by many not as a cycle, but as a permanent change in how middle-market companies are financed.
Decision Framework
For Investors: The “Risk-Adjusted” Question
When evaluating private credit funds, investors must determine if the extra yield of junior debt justifies the risk. In a zero-rate environment, investors often reached for mezzanine debt to hit return targets. Today, with senior secured loans yielding double digits, the decision framework shifts.
Ask: “Is it worth moving down the stack to chase an incremental 2-3% return when senior debt already provides 10-12%?”
For Operators: The Cost of Dilution vs. Debt
For founders and CFOs, the capital stack represents a trade-off between control (equity) and obligation (debt).
Evaluate: While senior debt comes with strict covenants and mandatory interest payments, it is non-dilutive. Raising equity at depressed valuations (the “down round” risk mentioned in valuation reports) permanently reduces founder ownership. Utilizing senior debt, provided the business has stable cash flows to service the ~11% cost, effectively “rents” capital rather than selling ownership.
Key Takeaways
- Seniority is Safety: In a liquidation event, senior lenders are paid first. Equity takes the first loss.
- The Rate Environment Has Changed the Calculus: High base rates (SOFR ~4.3%) mean “safe” senior debt now pays returns historically associated with riskier assets.
- Focus on the Cushion: Investors should focus on Loan-to-Value (LTV) ratios to ensure there is enough equity beneath them to absorb valuation shocks.
- Structural Discipline: As noted by Atlas Peak, stress in 2026 is concentrated in “semi-liquid” structures; understanding the liquidity terms of your specific vehicle is as important as the underlying assets.
- Strategic Capital: For operators, debt is currently expensive but may still be cheaper than the long-term cost of equity dilution.


