
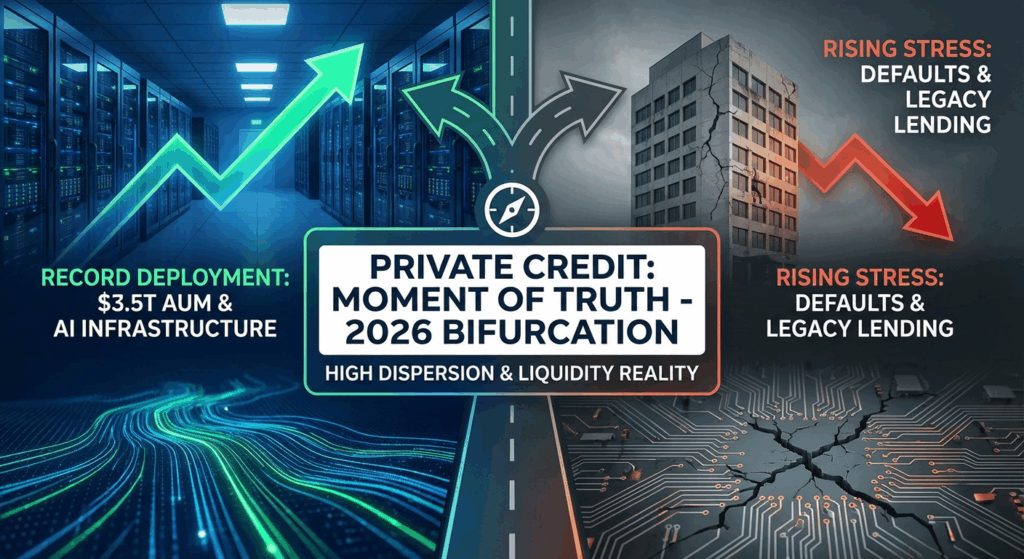
The Bifurcation of 2026: Record Deployment Meets Rising Credit Stress
By March 2026, the private credit market has reached a pivotal “moment of truth.” While the asset class has surged to $3.5 trillion in assets under management (AUM), a distinct bifurcation is emerging between booming infrastructure financing and stress in legacy corporate lending portfolios. The market is characterized by record capital deployment juxtaposed with visibly deteriorating borrower fundamentals, creating a complex environment for allocators and borrowers alike.
As of Q1 2026, the ease of the “scarcity era” has ended. We have entered a regime of high dispersion, where massive capital requirements for AI infrastructure are competing for liquidity against a backdrop of rising defaults in lower-middle-market software and unparalleled retail redemption pressures.
Quantitative Market Snapshot: Q1 2026
| Metric | Current Level | Trend / Comparison | Source |
|---|---|---|---|
| Private Credit AUM | $3.5 Trillion | +17% YoY (proj. $5T by 2029) | LongYield |
| Default Rate (Proskauer Index) | 2.46% (Q4 ’25) | Unknown rise from 1.84% in Q3 | LongYield |
| Borrower Health | 40% Negative FCF | Deteriorating coverage ratios | LongYield |
| New Capital Deployment | $592.8 Billion (2024 total) | +78% vs. prior year | LongYield |
| Hyperscaler Debt Issuance | $37 Billion (Amazon) | Shift from cash-flow to debt capex | AInvest |
Sector Analysis: The AI Diversion
Hot: AI Infrastructure & Asset-Based Finance (ABF)
The dominant narrative for 2026 is the structural shift in Artificial Intelligence financing. While hyperscalers historically funded CapEx via internal cash flow, the sheer scale of the buildout, projected to exceed $2.7 trillion through 2029, has forced a pivot to debt markets. Amazon’s recent $37 billion bond sale signals that even the most cash-rich firms are soaking up credit liquidity. For private credit, this opens opportunities in data center project finance and equipment leasing (ABF) as PIMCO notes that ABF is becoming a critical diversifier against corporate credit risks.
Cold/Watch: Legacy Software & Tech Lending
The “Golden Child” of private credit, recurring revenue loans to software companies, is facing headwinds. PIMCO analysts warn that heavy exposure to software in direct lending portfolios is constraining performance. Additionally, LongYield data indicates that 46% of software loans face maturities within four years, coinciding with a period where 40% of borrowers report negative free cash flow. Lenders are increasingly wary of “extended and pretend” tactics in this sector, evidenced by rising Payment-in-Kind (PIK) usage which now accounts for over 8% of BDC income.
Implications for Market Participants
For Borrowers:
We are witnessing a “flight to quality.” Borrowers with tangible assets (infrastructure, real estate, data centers) or strong positive cash flows will find aggressive lender appetite and tightening spreads. Conversely, highly leveraged corporates relying on EBITDA accreditations will face wider spreads and stricter covenants. The “borrower-friendly” documentation of 2024-2025 is tightening for credits perceived as late-cycle risks.
For Lenders & Investors:
Liquidity management is the renewed focus. The closure of redemption windows at major funds (e.g., Blue Owl in Feb 2026) highlights the duration mismatch inherent in semi-liquid vehicles. Lenders are pivoting toward Asset-Based Finance (ABF) to secure collateral that is uncorrelated to corporate EBITDA. Apollo Academy emphasizes that 2026 will be defined by “dispersion, not distress,” meaning fund performance will vary wildly based on sector selection rather than broad market beta.
Key Market Insights
- Default Normalization: The Proskauer Default Index rising to 2.46% signals the end of the benign credit environment; expect stress to manifest in Q2/Q3 earnings.
- Retail Liquidity Risk: Redemption gates in semi-liquid funds are forcing a re-evaluation of the “democratization of private credit” thesis.
- AI as a Debt Driver: The $2T+ AI CapEx cycle is transitioning from equity-funded to debt-funded, creating massive new supply in investment-grade and private infrastructure debt.
- PIK Warning Signs: With PIK income rising to >8% of BDC revenue, the quality of earnings for many lenders is lower than headline yields suggest.
- M&A Revival: A resurgence in M&A is driving fresh deal flow, allowing lenders to rotate out of vintage 2021-2022 credits into fresher, better-structured paper.


