
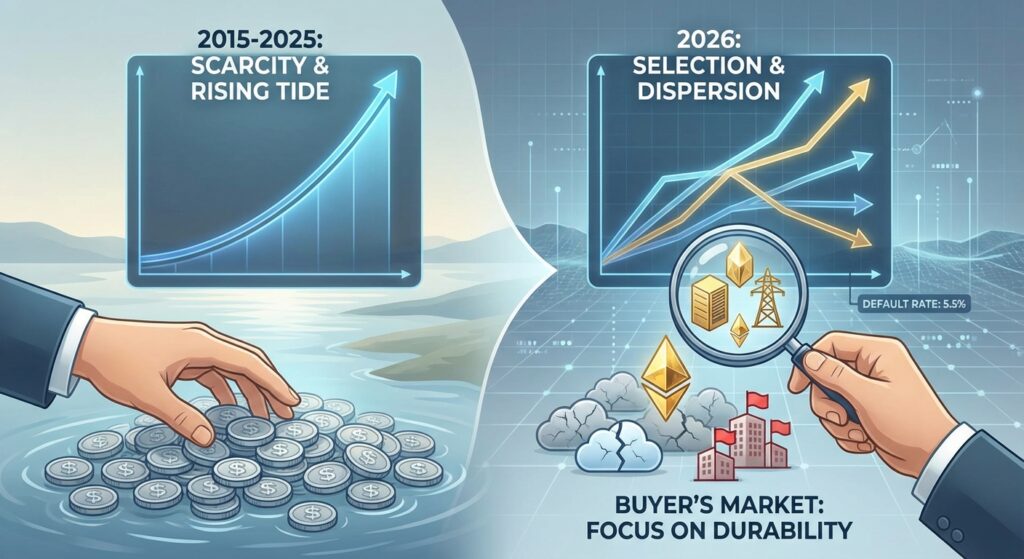
Market Headline: The Regime Shift from Scarcity to Selection
As of March 2026, the private credit market has officially surpassed the $3.5 trillion AUM milestone, cementing its status as a mainstream asset class. However, the benign conditions of the last decade have evaporated. We are witnessing a fundamental regime shift from a “seller’s market” defined by scarcity to a “buyer’s market” defined by dispersion and selection.
While capital deployment remains robust, growing 78% in the last annual cycle, underwriting discipline faces its first true systemic test. Middle market default rates have climbed to 5.5%, driven by a refinancing wall of approximately $350 billion in loans originated during the 2020-2021 peak. Simultaneously, liquidity pressure is mounting on semi-liquid funds, with headline stress at major managers like Blue Owl underscoring the risks of asset-liability mismatches in retail products.
The prevailing theme for Q1 2026 is dispersion. The “rising tide lifts all boats” era is over. Lenders are increasingly differentiating between issuers with genuine cash flow durability and those relying on recurring revenue models now threatened by AI disruption.
Quantitative Snapshot: Q1 2026
The following metrics highlight the divergence between asset accumulation and underlying credit performance.
| Metric | Current Level | Trend / Comparison | Source |
|---|---|---|---|
| Global Private Credit AUM | $3.5 Trillion | Mainstream adoption; Retail/Wealth is fastest growing channel | PRISM / PMI |
| 1st Lien Direct Loan Yields | 8.0% – 8.5% | Down from 10%+ peaks; margin compression evident | Private Markets Insights |
| Middle Market Default Rate | 5.5% | Rising; 65% of managers expect further loss rate increases | Morningstar DBRS / PMI |
| Refinancing Wall | $300 – $350 Billion | Loans entering 5th year; facing “refi window” stress | Verdence |
| LBO Volume | +40% YoY | Late 2025 growth signaling M&A revival | Private Markets Insights |
Sector Analysis: The AI Divergence
Sector rotation is currently driven by a single dominant force: Artificial Intelligence. However, its impact is bifurcated, creating distinct distinct winners and losers.
Software: Under Scrutiny (Cold)
Historically the darling of private credit, the software sector is facing a sharp re-evaluation. Approximately 20% of BDC and private credit loans are tied to software companies. Lenders are growing concerned that Generative AI could erode the “moats” of traditional B2B SaaS models, leading to questions about the durability of Annual Recurring Revenue (ARR).
- Data Point: The S&P 500 Software Index has corrected ~30% from recent highs, signaling public market skepticism that is bleeding into private valuations.
- Lender Appetite: Tightening significantly for non-AI-native software firms. Managers are actively re-underwriting portfolios to assess displacement risk.
Asset-Based Finance (ABF) & Infrastructure: High Demand (Hot)
Conversely, the physical build-out required to support AI is driving massive demand for capital. 65% of managers now identify Asset-Based Finance (ABF) as offering the highest growth potential, with Apollo projecting a $40 trillion Total Addressable Market (TAM).
- Data Point: Hyperscaler investment (Capex for data centers/power) has tripled since 2023.
- Lender Appetite: Strong. Lenders are pivoting toward data centers, power infrastructure, and equipment finance where collateral is tangible and unconnected to software obsolescence risks.
Implications for the Market
For Borrowers
The “Refinancing Wall” is the primary challenge. Borrowers with loans originating in 2020-2021 are facing a market with stricter covenants and lower leverage tolerance for C-minus credits. While yields have compressed slightly to the 8.0–8.5% range, the “dispersion” in pricing has widened. Strong credits with “AI-proof” business models will find ample liquidity from banks partnering with private capital, while lower-tier credits may face forced asset sales or PIK (Payment-in-Kind) restructuring to conserve cash.
For Lenders & Investors
We are seeing a return to “Active Management.” The passive deployment of capital into diversified pools is risky in a 5.5% default rate environment. The liquidity issues at firms like Blue Owl serve as a cautionary tale regarding sem-liquid structures. Investors are increasingly favoring managers with strong workout capabilities and distinct sector expertise (e.g., ABF) rather than generalist direct lenders. Bank partnerships (e.g., JPMorgan’s $50B commitment) are providing a new exit route and liquidity source for larger deals, potentially stabilizing the upper end of the market.
Key Market Insights
- Default Normalization: Prepare for middle-market defaults to stabilize near 5.5% as the cycle weeds out “COVID-era” vintage loans with loose covenants.
- The “Anti-Software” Rotate: Expect capital flows to shift from generic SaaS lending toward hard-asset backed finance (infrastructure, power, equipment).
- Retail Liquidity Risk: Semi-liquid funds are facing redemption stress; avoid funds with significant asset-liability duration mismatches.
- Bank Re-entry: Traditional banks are no longer just competitors; they are becoming the largest LPs and partners, creating a hybrid financing model for large-cap deals.
- Yield Compression: With yields compressing to ~8%, the “alpha” will come from avoiding losses (credit selection) rather than high spreads.


