
The Story: A Pandemic Pivot and a Capital Conundrum
In the high-stakes world of SaaS, the default playbook often reads like a single track: raise venture capital, burn it for growth, and repeat until IPO or exit. But for Simon Turner, co-founder of retail sales enablement platform Myagi, the playbook needed a rewrite.
By 2020, Myagi had established itself as a digital connector between brands, retailers, and distributors. When the COVID-19 pandemic hit, global retail operations were thrown into chaos, driving a sudden, intense demand for digital transformation in sales processes. Myagi was perfectly positioned to capture this wave. The company experienced its best six months of growth to date, signaling a clear opportunity to scale.
However, growth requires fuel. In March 2020, Myagi had plans for a significant equity round, but the pandemic’s economic uncertainty complicated valuations and timelines. By early 2021, Turner faced a classic founder’s dilemma: the company needed a cash injection to seize the market momentum, but selling more equity at that stage meant permanently diluting the founders and early investors just as the business was hitting its stride.
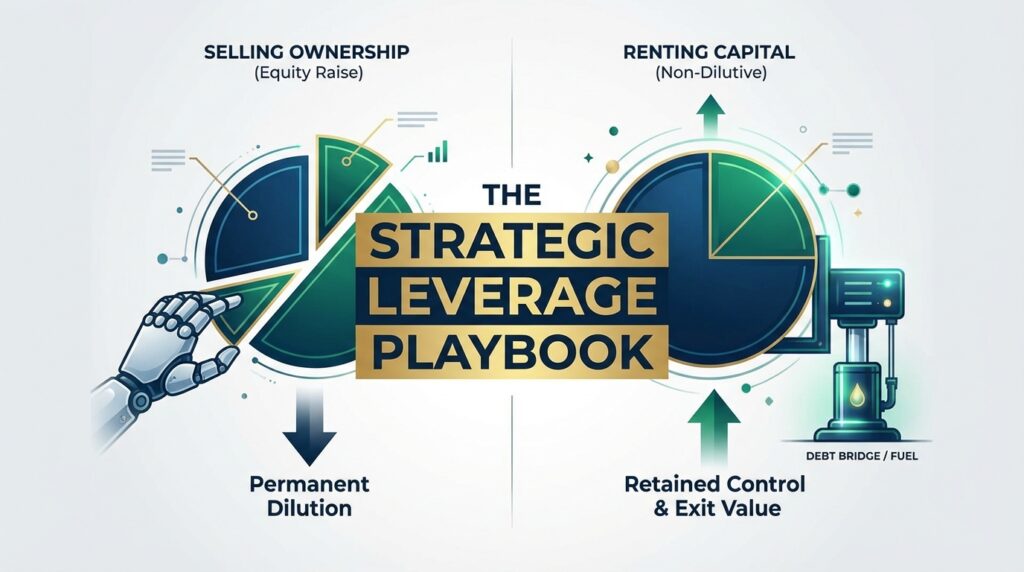
The Decision: Renting Capital vs. Selling Ownership
Turner analyzed the cost of capital through a lens often overlooked by founders chasing unicorn status: control and retention. A venture capital round would bring not just cash, but a new board presence, liquidation preferences, and a permanent reduction in the founders’ slice of the pie. If the company doubled in value, that equity slice would be gone forever.
Instead of forcing a square peg into a round hole, Turner turned to the private credit market. He sought a partner that understood the predictability of SaaS recurring revenue. In early 2021, Myagi secured a $2.5 million investment facility from TIMIA Capital.
The logic was purely economic. Debt (even venture debt or revenue-based financing) has a fixed cost. It is capital you "rent" for a period of time. Equity is capital you "sell." If you believe your equity is going to appreciate significantly, renting capital is almost always cheaper than selling it. As Turner later noted, "Debt is a powerful tool for capital-efficient businesses when used under the right circumstances."
The Outcome: A Clean Exit Without the Drag
The injection of $2.5 million allowed Myagi to invest heavily in sales enablement and product development without altering the cap table. The company used the funds to execute on its roadmap, driving revenue and market position upward.
The strategy paid off. Roughly two years after securing the non-dilutive capital, Myagi was acquired by Rallyware, a performance enablement platform. Because the growth was funded by debt rather than a Series B or C equity round, the exit proceeds were not diluted by a new layer of preference stacks or venture investors.
The debt facility did exactly what leverage is designed to do: it bridged the gap between a growth opportunity and a liquidity event. The lender was repaid, and the remaining value flowed to the shareholders. Had Myagi raised a $5 million or $10 million equity round in 2021, the founders would have owned significantly less of the company at the moment of sale, potentially changing the economics of the exit entirely.
The Lessons: Anatomy of a Non-Dilutive Win
The Myagi case illustrates a sophisticated approach to capital allocation that more founders are beginning to embrace. It highlights that the "VC or bust" mentality is often a false dichotomy.
When this approach works:
- Predictable Revenue: Private credit providers lend against future cash flows. High-retention SaaS models are ideal candidates because the risk of default is lower.
- Bridge to Value: Debt serves as an excellent bridge to a specific milestone, in this case, an acquisition. It prevents selling equity at a discount right before a value-creating event.
- Capital Efficiency: Companies that have already found product-market fit and need fuel for fire (sales/marketing) are better suited for debt than pre-revenue startups searching for a business model.
Conversely, this strategy fails when companies over-leverage without a clear path to repayment or exit. As seen in other sectors, such as crypto mining (e.g., TeraWulf’s high-stakes debt expansion), leverage increases risk. If the growth doesn’t materialize, the fixed costs of debt can suffocate the business. Myagi succeeded because the underlying business fundamentals were sound, and the leverage ratio was manageable.
Key Insights
- Cost of Capital is Relative: Equity is the most expensive form of capital for a successful company; debt is often the cheapest.
- Preserve Optionality: Debt facilities rarely come with the board seats or control provisions that accompany venture capital, leaving operators in the driver’s seat.
- Timing is Everything: Myagi utilized debt specifically to capture a demand surge (COVID-19 digitization), aligning the capital inflow with a high-probability growth period.
- The Exit Multiplier: By avoiding dilution in the final years before an exit, founders can increase their personal outcome largely irrespective of the headline exit price.
- Know Your Metrics: Successful leverage requires rock-solid churn and retention metrics. You cannot leverage a leaky bucket.


