
The Architecture of Risk: Why “Where” You Sit Matters More Than “What” You Earn
In private credit, the most critical question isn’t always “what is the yield?” typically, it is “where do we sit?” The answer lies in the Capital Stack: the hierarchical structure that defines who gets paid first, who gets paid last, and who absorbs the losses when plans go awry.
For investors, the capital stack is the map of risk protection. For business operators, it is the menu of dilution and cost. Understanding this structure is the single most important fundamental concept in alternative financing. It separates standard banking relationships from the complex, bespoke world of private credit.
The Concept: The Payment Waterfall
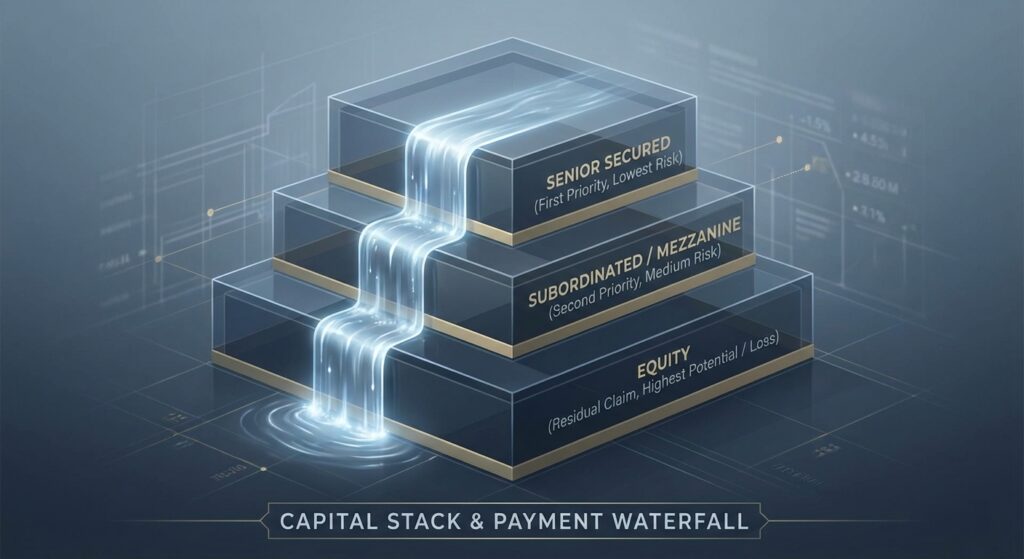
The capital stack represents the layers of capital used to finance a company, organized by priority of repayment. Think of it as a waterfall: cash flows from the business pour over the top, filling the first bucket completely before spilling over into the next.
According to a November 2025 industry primer by Umbrex, the stack is generally divided into three primary tiers:
- Senior Secured Debt: The top of the stack. These lenders have the first claim on assets and cash flow. In the event of liquidation, they are paid before anyone else. Because they take the least risk, they accept the lowest relative returns.
- Subordinated (Mezzanine) Debt: The middle layer. This sits below senior debt but above equity. These lenders only get paid after senior lenders are satisfied. To compensate for this “second-in-line” risk, they command higher interest rates and often “equity kickers” like warrants.
- Equity: The bottom of the stack (Common and Preferred). This is the ownership layer. Equity holders have the last claim on assets but unlimited upside potential. If the company fails, they are the first to lose their capital.
How It Works: The $100 Million Scenario
Abstract definitions often fail to convey the brutal math of subordination. Let’s apply this to a concrete example of a fictional manufacturing company valued at $100 million.
The company finances this $100 million valuation with the following structure:
- $50 Million Senior Loan (50% Loan-to-Value)
- $20 Million Mezzanine Debt
- $30 Million Sponsor Equity
The Downside Protection Mechanism
Imagine the company faces severe headwinds (supply chain issues or a market downturn) and is forced to liquidate or sell for a distressed price of $60 million (a 40% drop in value).
Here is how the waterfall dictates the payout:
- Senior Lenders: They are owed $50M. The sale generated $60M. The senior lenders are repaid in full (100% recovery), despite the company losing 40% of its value. Their “equity cushion” protected them.
- Mezzanine Lenders: They are owed $20M. After paying the senior lenders, only $10M remains ($60M sale – $50M senior debt). The mezzanine lenders receive $10M, resulting in a 50% loss of principal.
- Equity Holders: They are owed the residual. Since the debt claims ($70M total) exceeded the sale price ($60M), the equity holders receive $0. They suffer a 100% loss.
This mechanism highlights why private credit investors heavily scrutinize the “attachment point” (where their loan starts) and the “detachment point” (where their protection ends).
Current Market Relevance
The structure of the capital stack has evolved significantly in the current vintage of private credit deals.
1. The Rise of Unitranche
Historically, borrowers had to negotiate separately with senior banks and mezzanine lenders. Today, data from late 2025 indicates a shift toward Unitranche facilities. These structures combine senior and junior risk into a single loan instrument with a blended interest rate. This simplifies execution for operators while giving lenders a higher weighted average yield.
2. Dominance of Senior Secured Strategies
Despite the allure of high returns in distressed debt, the bulk of the market remains focused on safety. According to a February 2025 report by Adams Street Partners, the “predominant form” of private credit remains senior secured direct lending. Investors are prioritizing position at the top of the stack over reaching for yield in the middle.
3. Institutional Scale
The asset class has matured from a niche to a cornerstone. PitchBook reported that private debt had grown to account for over 16% of total private market assets under management. This influx of capital allows for larger, more resilient capital stacks that can support borrowers through economic volatility.
Decision Framework
Both investors and operators must evaluate the capital stack, but they view it through opposing lenses.
For Investors: The Safety vs. Yield Trade-off
When allocating to private credit, the primary decision is where to attach risk.
- Senior Allocation: Choose this for capital preservation and consistent income. The primary risk metric is Loan-to-Value (LTV). If LTV is 50%, the enterprise value must drop by half before your principal is threatened.
- Junior/Mezzanine Allocation: Choose this for equity-like returns without the full volatility of equity. The key metric here is Debt Service Coverage Ratio (DSCR): can the company’s cash flow support the higher interest burden?
For Operators: Cost vs. Dilution
Business owners often fear debt, but the capital stack reveals why it can be efficient.
- Cheaper than Equity: Senior debt might cost 10-12%, while equity investors typically target 20-30% returns (IRR). Using the top of the capital stack (senior debt) to fund growth is “non-dilutive,” preserving ownership for the founders.
- Flexibility: Using a Unitranche structure can provide more leverage (money) than a traditional bank would offer, allowing for larger acquisitions without needing to raise expensive equity capital.
Key Takeaways
- Seniority is Safety: In a liquidation scenario, senior lenders are paid first. Junior lenders and equity holders absorb losses from the bottom up.
- Equity Cushion Matters: The value of the equity beneath the debt layer acts as a shock absorber for lenders. A 40-50% equity cushion is standard in healthy deal structures.
- Unitranche Simplifies the Stack: Modern private credit often blends senior and junior debt into one instrument, offering speed and certainty of closing.
- Cost of Capital Increases with Risk: As you move down the stack (from Senior to Mezzanine to Equity), the required return increases to compensate for the higher risk of loss.
- Alignment of Interest: A proper capital stack ensures the operator has enough “skin in the game” (equity) to stay motivated, while the lender is protected against moderate downturns.


