
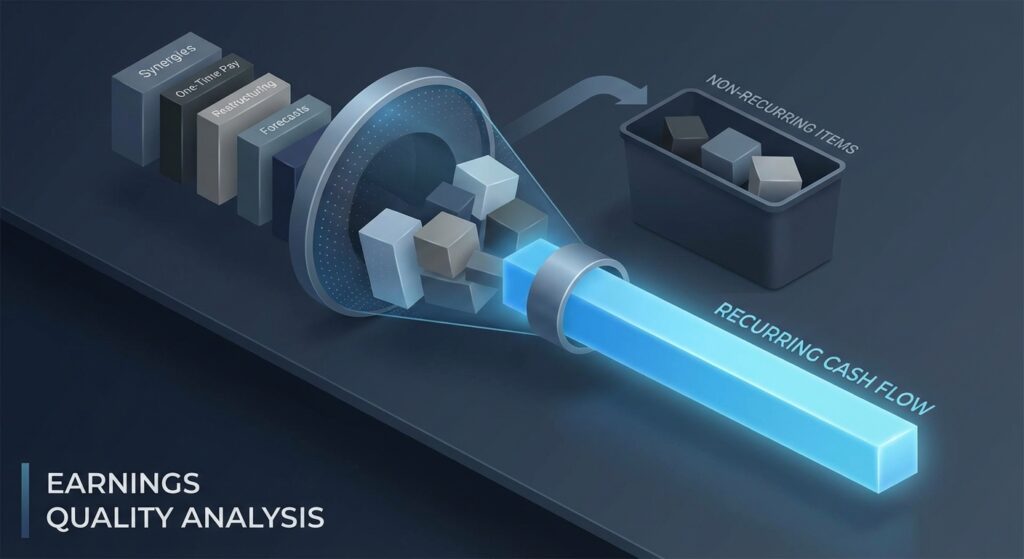
The Underwriting Challenge: The Reality of Adjusted EBITDA
In modern credit markets, the distance between reported Generally Accepted Accounting Principles (GAAP) Net Income and the “Marketing EBITDA” presented in a Confidential Information Memorandum (CIM) has arguably never been wider. For lenders and credit risk professionals, the underwriting challenge often relies less on the headline number and more on the forensic reconstruction of cash flow quality.
The reliance on “Adjusted EBITDA” to justify leverage multiples introduces significant latency into risk detection. If a borrower requests a loan based on $15 million of Adjusted EBITDA, but the trailing twelve-month (TTM) cash flow available for debt service is closer to $10 million, the pro forma leverage ratio of 3.0x is practically operating at 4.5x. This discrepancy removes the buffer against economic volatility, turning minor operational hiccups into covenant breaches or payment defaults.
Effective underwriting requires a disciplined framework to separate legitimate one-time add-backs from recurring operational costs masquerading as “extraordinary” expenses. This article outlines a rigorous methodology for normalization and stress testing cash flow adjustments.
The Framework: Categorizing and Validating Adjustments
To analyze EBITDA adjustments effectively, underwriters must move beyond the “management definition” and apply a credit-specific lens. We categorize adjustments into three tiers of reliability:
- Tier 1: Standard & Non-Cash (High Reliability) – Depreciation, amortization, stock-based compensation, and proven non-cash charges. These are standard and widely accepted.
- Tier 2: Transactional & One-Time (Moderate Reliability) – M&A transaction fees, severance from a specific restructuring event, or losses from a discontinued line of business. These require invoice verification to ensure they are truly non-recurring.
- Tier 3: Pro Forma & Synergies (Low Reliability) – Projected cost savings, “run-rate” adjustments for new contracts not yet active, and expense reductions from efficiency initiatives. These are highly speculative and often behave like equity stories rather than credit facts.
According to Fitch Ratings in their Corporate Rating Criteria, projections are typically developed with a three- to five-year horizon, but the weighting of factors changes based on weakness. When financial flexibility is dependent on speculative adjustments, the risk weight increases significantly. Underwriters should view Tier 3 adjustments with extreme skepticism, often capping them at a percentage of EBITDA (e.g., 10-15%) or excluding them entirely for base-case scenarios.
The Analysis: Normalizing a $10M Manufacturing Company
Consider a manufacturing borrower presenting a TTM Adjusted EBITDA of $10 million to support a $35 million term loan (3.5x leverage). The reconciliation table provided in the CIM is as follows:
- Net Income: $2.5 million
- Interest/Taxes/D&A: +$3.5 million
- Reported EBITDA: $6.0 million
- Adjustment A (Owner’s Personal Expenses): +$1.0 million
- Adjustment B (ERP Implementation Costs): +$1.5 million
- Adjustment C (Future Plant Synergies): +$1.5 million
- Total Adjusted EBITDA: $10.0 million
The Lender’s View:
- Adjustment A ($1.0M): Valid if the owner is exiting or expenses are contractually eliminated post-close. If the owner stays, these often “leak” back into the P&L as increased salary or dividends.
- Adjustment B ($1.5M): “One-time” technology implementations often bleed into recurring IT maintenance costs. A risk-adjusted approach treats only the external consultant fees as one-time, while retaining software licensing fees as an operating expense.
- Adjustment C ($1.5M): Future synergies are 0% value in a liquidation scenario. A conservative underwriter removes this entirely for the primary leverage calculation, recalculating the risk.
Revised Calculation: Removing the synergies and half the ERP costs reduces EBITDA to roughly $7.75 million. The requested $35 million debt now represents 4.5x leverage, not 3.5x. This fundamentally changes the pricing model and required covenant structure.
Industry Standards & Red Flags
Institutional lenders and regulators have sharpened their focus on asset quality and income verification. The FDIC notes in its Risk Management Manual of Examination Policies that asset quality enables management to identify and manage credit risk, emphasizing that examiners should not look at data in a vacuum. A high volume of soft adjustments is often a red flag for management’s inability to control core costs.
Recent principles from the Basel Committee also highlight the necessity of an appropriate credit administration and monitoring process. Relying on inflated EBITDA definitions undermines the accuracy of risk ratings and capital provisioning.
Common Red Flags in Quality of Earnings (QoE):
- “Headline” vs. “Bank” EBITDA: Significant deviation between the EBITDA shown in management slides and the definition in the credit facility compliance certificate.
- Recurring “Non-Recurring” Charges: Restructuring charges that appear every year for three years running. This suggests restructuring is actually the company’s standard operating procedure.
- Uncapped Synergies: Adjustments for cost savings that do not have a corresponding dollar-for-dollar reduction in historical expense lines.
Underwriting Checklist: Validating Cash Flow
When assessing the validity of EBITDA add-backs, the credit team should execute the following diligence steps:
- Review the Quality of Earnings (QoE) Report: Ensure a reputable third-party accounting firm has validated the “proof of cash” for historical adjustments.
- Cap Speculative Add-Backs: Structure the credit agreement to cap “expected cost savings” at 10%–20% of Adjusted EBITDA and restrict the time window for realization (e.g., must be realized within 12 months).
- Request Invoices for Major One-Timers: Do not accept a spreadsheet line item for “Consulting Fees” without sampling the underlying invoices to ensure they aren’t recurring retainers.
- Stress Test the “Unadjusted” Scenario: Run debt service coverage ratios (DSCR) using raw Reported EBITDA. If the company cannot service debt without the add-backs, the structure is likely untenable.
Key Risk Management Takeaways
- Cash Flow Over Accounting: EBITDA is a proxy for cash flow, not cash flow itself. Capital expenditures and working capital changes must still be deducted to find true repayment capacity.
- Skepticism is Safety: Assume “future synergies” will not materialize in year one. Underwrite based on what the company is, not what it hopes to be.
- Covenant Definitions Matter: The definition of EBITDA in the legal documentation is as important as the interest rate. Loose definitions allow leverage creep.
- Watch for Frequency: If an expense happens two years in a row, it is an operating expense, not an extraordinary item.
- Macro Context: In high-rate environments, the margin for error shrinks. Inflated EBITDA denominators can mask dangerous leverage numerators.


