
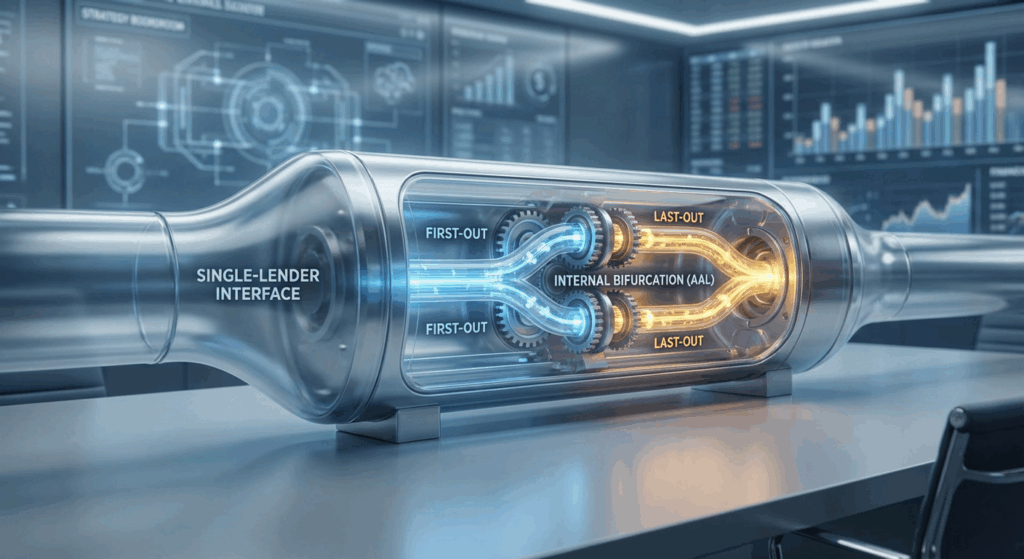
The Financing Challenge
For middle-market operators and private equity sponsors, the friction of arranging multiple tranches of capital has historically been a significant deal risk. Traditional structures required negotiating separate senior and mezzanine facilities, often with competing creditors and complex intercreditor agreements that could stall execution. In the current 2026 landscape, the unitranche facility has emerged not just as an alternative, but as the dominant structure for sponsor-backed buyouts, driven by a premium placed on speed and certainty of closing.
However, the simplicity of a unitranche facility (one loan, one rate, one agent) is often an optical illusion. While the borrower faces a single interface, the internal engineering of these facilities frequently involves a sophisticated bifurcation of risk and return between lenders. Understanding these mechanics is critical for CFOs and sponsors to effectively negotiate terms and anticipate how lenders will behave in downside scenarios.
Structure Breakdown: The Hidden Waterfall
A unitranche facility blends senior and subordinated debt into a single instrument. From the borrower’s perspective, there is one credit agreement, one amortization schedule, and one blended interest rate. Behind the scenes, however, lenders often utilize an Agreement Among Lenders (AAL) to split the loan into tranches with different risk profiles.
The Mechanics of the AAL
The AAL creates a "First-Out" (FO) and "Last-Out" (LO) structure without the borrower needing to be a party to the segmentation:
- First-Out Tranche: typically held by banks or lower-cost-of-capital providers. This tranche has super-senior priority on payment waterfalls and liquidation but receives a lower yield.
- Last-Out Tranche: typically held by private credit funds or BDCs. This tranche absorbs the first loss after equity and carries a higher risk-adjusted return, effectively functioning like mezzanine debt.
Detailed Deal Example
Consider a hypothetical leveraged washout for a software company with $10 million in EBITDA and a $100 million Enterprise Value.
- Structure: $55 million Unitranche Term Loan (5.5x Turn).
- Borrower Rate: SOFR + 625 bps (blended).
- Upfront Fee: 2.0% OID.
Behind the Curtain (The Lender Split):
- First-Out ($30M): Provided by a commercial bank at SOFR + 350 bps.
- Last-Out ($25M): Provided by a direct lender. To achieve the blended rate of S+625 on the total facility, the Last-Out lender is effectively earning significantly higher spread, often pushing into low double-digit returns when leverage is applied.
If the borrower defaults and the assets are liquidated for $40 million, the First-Out lender is made whole ($30M), while the Last-Out lender recovers only $10M of their $25M principal, mimicking the risk profile of subordinated debt.
How It Compares: Unitranche vs. Traditional Structures
When evaluating a unitranche against a traditional Senior/Mezzanine split, the trade-offs center on cost versus execution risk.
| Feature | Unitranche | Traditional Senior + Mezz |
|---|---|---|
| Execution Speed | High (30-45 days faster). One set of docs. | Medium/Low. Two sets of docs, intercreditor negotiation. |
| Cost of Capital | Moderate Blended Rate. Includes "convenience premium." | Potentially lower weighted average cost (Senior is cheap). |
| Amortization | Typically 1% per annum. | Senior amortizes heavily; Mezz is bullet. |
| Covenants | Usually one financial maintenance covenant (Leverage). | Senior has maintenance; Mezz has incurrence. |
Private lenders have noted that sponsors are often willing to pay a premium of 50 to 100 basis points in spread for the unitranche structure to avoid the risk of "market flex" terms or broken syndications common in traditional bank processes [privateequitybro.com].
Current Market Terms (2024-2026 Data)
Recent data indicates that private credit and unitranche facilities continue to command a significant share of the buyout market, accounting for roughly 80% of North American buyout financing by deal count in recent periods. Market participants should utilize the following benchmarks for 2026 planning:
- All-In Yields: New private credit deals have seen average all-in yields hovering between 12% and 13% [privateequitybro.com].
- Leverage Profiles: Total leverage in sponsored middle-market deals is averaging roughly 5.0x EBITDA, with lenders increasingly focused on free cash flow coverage rather than just enterprise value coverage.
- Jumbo Unitranches: The market has seen a rise in "mega-unitranche" facilities exceeding $2 billion, proving this structure is no longer limited to the lower middle market. These are often syndicated among a "club" of direct lenders [lexisnexis.co.uk].
Structuring Guidance
For Operators and Borrowers
While the AAL is technically a lender-side document, its terms affect you. In a workout scenario, voting rights matter. Typically, the "Last-Out" lender (the credit fund) controls the vote on waivers and amendments because they hold the riskiest position. However, "First-Out" lenders may have blocking rights on specific material changes (e.g., interest rate reductions, releasing collateral).
Negotiation Tip: Focus on Call Protection. Unitranche lenders often demand stricter prepayment penalties (e.g., 102/101/Par soft calls) compared to bank loans. Operators should negotiate for "hard" call protection to essentially vanish after year two to allow for refinancing if rates drop or credit improves.
For Investors
When participating in a club unitranche, the definition of "Required Lenders" is paramount. Ensure the AAL aligns voting thresholds so that a minority First-Out holder cannot hold the structure hostage during a necessary restructuring, while still protecting their priority status.
Key Takeaways
- Unified Interface: Unitranche offers borrowers a single point of contact and documentation, heavily reducing closing friction compared to syndicated execution.
- Hidden Complexity: An Agreement Among Lenders (AAL) typically bifurcates risk into super-senior and junior tranches behind the scenes.
- Premium Pricing: Borrowers pay a premium (spread and call protection) for the speed and certainty of the structure.
- Scale: The structure has scaled up, with facilities now regularly exceeding $1 billion, effectively competing with the High Yield bond market.
- Voting Rights: In distress, the "Last-Out" lender usually controls the process, aligning the controlling class with the economic risk.


